Stephanie Stevens is an associate writer with TPG's credit cards team. She focuses on creating timely credit cards content for TPG readers.
October 20, 2025 • 9 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.
Editorial note: This is a recurring post, regularly updated with new information and offers.
Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
Premium credit cards offer extensive travel perks such as lounge access, statement credits and elite status, but come with high annual fees.
These cards are best suited for frequent travelers and those who can maximize the value of included benefits.
If you regularly use travel credits, airport lounges and elite status upgrades, the value can outweigh the cost.
For those who travel infrequently or prefer simpler rewards, mid-tier or straightforward cash-back cards may be a better fit.
What to consider
Maximizing value requires active use of benefits like statement credits, lounge access and elite status perks.
Premium cards often have complex benefit structures that may not suit those seeking simplicity or minimal effort.
Lower-fee or no-fee cards may provide better value for individuals who do not travel often or prefer uncomplicated rewards.
What you'll miss from the article
A detailed breakdown of which types of travelers benefit most from premium cards and how to assess if the perks align with your habits.
Generated by AI with support from our editorial team.
Premium credit cards are often marketed as the ultimate tool for travelers, packed with perks like airport lounge access, travel credits, elite status and elevated earning rates. But with annual fees that can reach almost $900, many people wonder: Are these cards truly worth the cost?
The truth is, these cards can deliver tremendous value — or end up costing you more than they're worth. It all depends on your travel habits, spending patterns and how much you'll take advantage of what's offered.
Here's how to tell whether a premium card deserves a spot in your wallet.
Before we dive into the details, let’s take a moment to understand what makes a credit card premium.
Premium credit cards represent the top tier of the rewards card ecosystem. These high-end cards typically come with hefty annual fees (from $395 to nearly $900) but also offer an impressive lineup of perks. Think: airport lounge access, elite hotel or airline status, generous statement credits, enhanced travel protections and accelerated points earning.
RISKA/GETTY IMAGES
They're designed for frequent travelers and big spenders who can maximize the value of the benefits. But premium doesn’t mean one-size-fits-all; what’s valuable to one cardholder might not be worth it to another.
Some of the most popular premium credit cards on the market include:
When a premium credit card is worth the annual fee
When are premium credit cards worth the fee? Here are a few signs a premium credit card might belong in your wallet.
You'll use the statement credits
Many premium cards make it surprisingly easy to offset most (if not all) of your annual fee through statement credits alone. But these credits only have value if you actually use them.
For example, the offers an up to $300 annual travel credit that automatically applies to a wide range of purchases, from airfare and hotels to parking and tolls.
If those credits match your lifestyle, your annual fee could easily pay for itself. But if you won't use them — say, you rarely use ride-hailing services or don't stay in hotels often — the value disappears quickly.
You value airport lounge access and travel perks
For many travelers, airport lounge access alone can make a premium card worth keeping. The offers the most comprehensive access of the cards above, including to Centurion Lounges, Delta Sky Clubs (when flying Delta) and Priority Pass lounges (enrollment required).
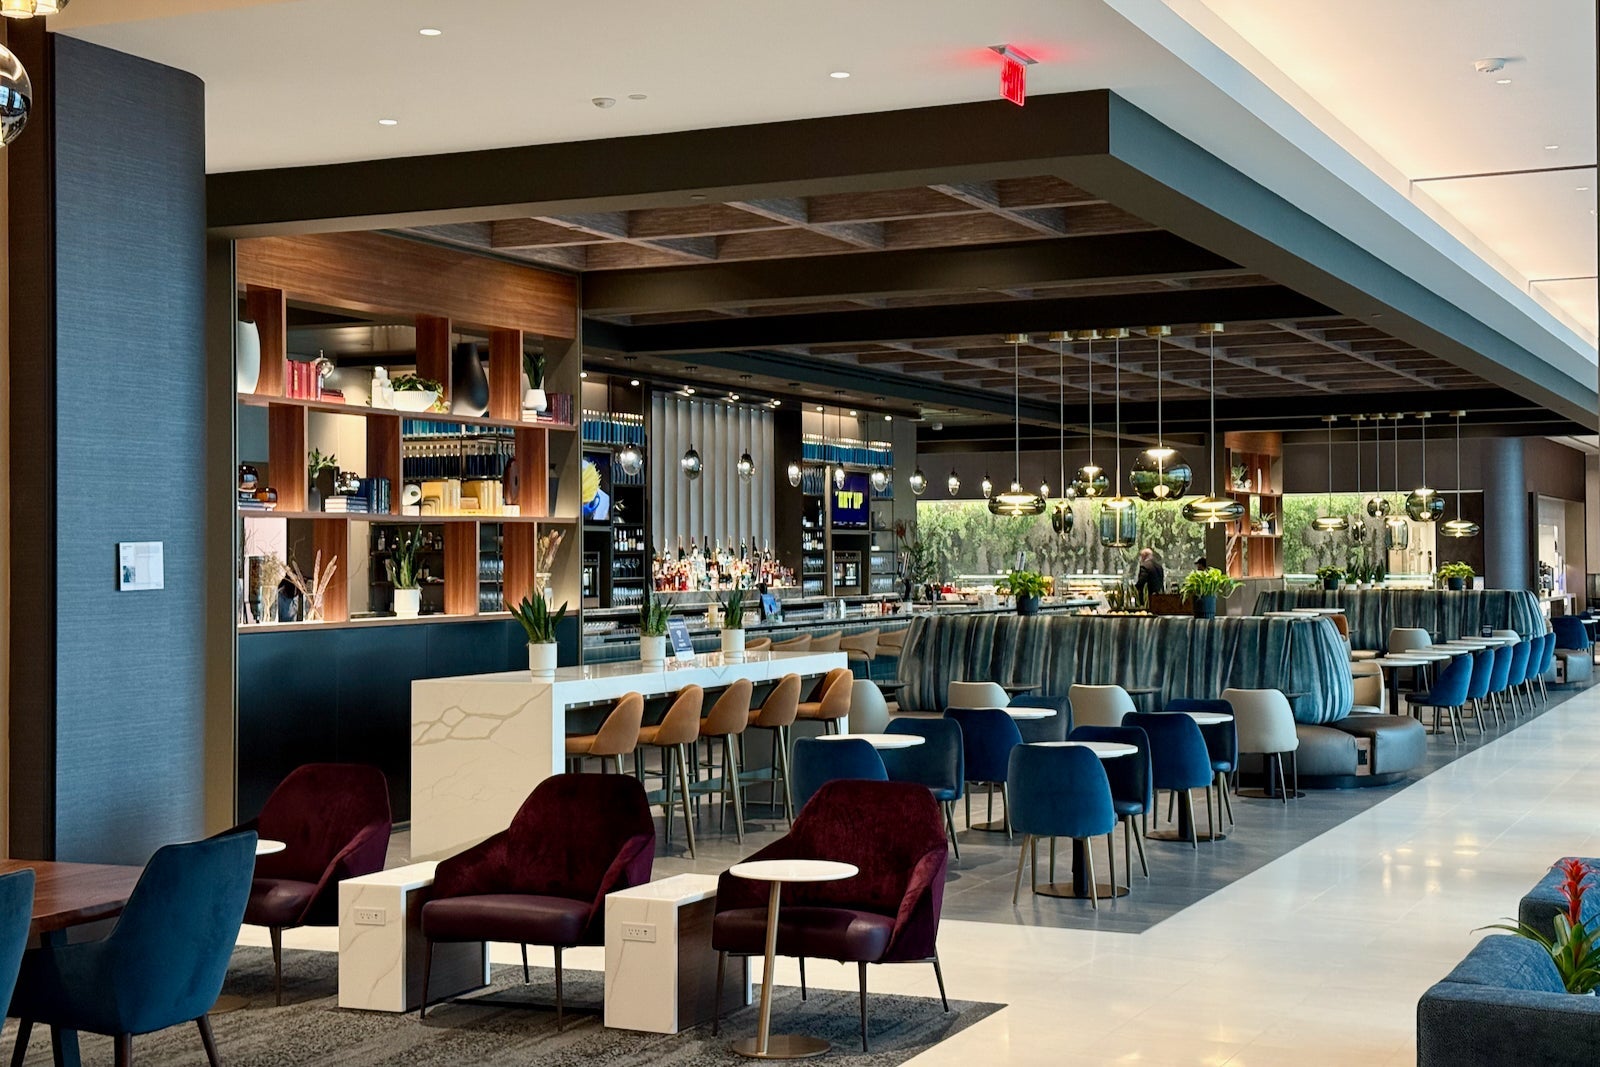
ZACH GRIFF/THE POINTS GUY
The and both come with unlimited access to their respective airline lounges, which is a huge perk if you regularly fly American Airlines or United Airlines.
If you're someone who spends hours in airports each month, these perks can easily outweigh the annual fee. However, if you only travel once or twice a year, it might be smarter to opt for a lower-tier travel rewards card, such as the (see rates and fees) instead.
Premium cards often offer automatic elite status with airline or hotel partners, which is a benefit that can elevate your travel experience even further.
For example, the includes complimentary Hilton Diamond status, offering complimentary breakfast, and room upgrades and late checkout (subject to availability). The automatically grants Platinum Elite status (and a path to higher tiers through spending).
HILTON
Meanwhile, premium cobranded airline cards like the and the help you spend toward status and move you higher up the upgrade list.
If you fly or stay at hotels regularly, these perks can deliver hundreds (or even thousands) of dollars in added value each year.
Premium cards tend to offer higher earning rates and more flexible redemption options than lower-tier travel rewards cards. The , for instance, earns 3 points per dollar on dining and 8 points per dollar on Chase Travel℠ bookings.
Meanwhile, cardholders earn 5 points per dollar on flights booked directly with airlines or through American Express Travel® (on up to $500,000 per calendar year, then 1 point per dollar), which is a high rate of return for frequent flyers.
For instance, Chase Ultimate Rewards points can be transferred to programs like Air France-KLM Flying Blue and World of Hyatt, where they can unlock significantly more value than a simple cash-back redemption.
This is especially true when a transfer bonus is in play. I recently took advantage of a 25% transfer bonus while booking a flight to Paris. The flight cost 18,750 Flying Blue miles, but thanks to the bonus, I only needed to transfer 15,000 Chase points to cover it.
When a premium credit card is not worth the annual fee
Premium credit cards come packed with perks, but those benefits only matter if you actually use them. For some cardholders, the high annual fee just doesn’t make sense based on their spending or travel habits.
Here are a few signs a premium credit card might not be the right fit for you.
You won't use the travel perks
At the end of the day, premium cards are designed for people who travel and travel often. If your lifestyle doesn't include regular flights, hotel stays or time spent at airports, many of these benefits will go unused.
You'll likely be better off with a mid-tier travel card that still earns value points but has a lower annual fee, like the (see rates and fees) — one of our favorite starter travel cards here at TPG — and one of the top cards in my wallet.
Premium card annual fees reach into the hundreds of dollars (and potentially soon into the thousands). Those fees can be worth it if you can maximize credits, lounge access and transfer partners, but if you don't, the math may not add up.
PEKIC/GETTY IMAGES
If you want to keep your costs low, a no-annual-fee card like the (see rates and fees) may be a better fit.
Premium cards often come with complex benefits, earning structures, and redemption options that can be overwhelming if you're not deep into the points and miles world. If that sounds like you, a premium card might not be the best fit — though there are a few exceptions.
For example, the Capital One Venture X offers one of the more straightforward earning structures, earning at least 2 miles per dollar on every purchase and 5-10 miles per dollar spent on travel booked through Capital One's travel booking site. You'll still enjoy premium perks like airport lounge access and travel protections without the need to memorize bonus categories or monthly credits.
However, if you prefer to skip the premium tier and annual fees entirely, the (see rates and fees) is a strong choice, earning at least 1.5% cash back on every purchase.
Between monthly credits, lounge access rules, bonus categories and elite status requirements, maximizing a premium card requires some effort. If you don't want to monitor expiring credits or jump through hoops to activate perks, you might not get full value out of a premium card.
Instead, you might try a straightforward card like the (see rates and fees), which has no rotating categories and no travel credits to remember.
Premium credit cards can absolutely be worth the annual fee, but only if you'll take advantage of what they offer. Frequent travelers who use the statement credits, enjoy lounge access and maximize reward redemptions will easily come out ahead.
If those perks align with your spending habits, a premium card like the , or can pay for itself year after year. But if you're not likely to use the benefits, consider a lower-fee option and save your money for your next trip instead.
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.