The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Stephanie Stevens is an associate writer with TPG's credit cards team. She focuses on creating timely credit cards content for TPG readers.
October 20, 2025 • 9 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.
Editorial note: This is a recurring post, regularly updated with new information and offers.
Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
Premium credit cards offer extensive travel perks such as lounge access, travel credits, elite status and enhanced travel protections, but typically come with high annual fees.
These cards are best suited for frequent travelers and those who can fully utilize benefits like statement credits and flexible reward redemptions.
Maximizing value from premium cards requires regular use of travel perks and strategic points redemption, especially through transfer partners and bonus opportunities.
For those who travel infrequently or prefer simplicity, mid-tier or straightforward rewards cards may be a better fit.
What to consider
Premium cards often require tracking multiple benefits, including monthly credits, lounge access rules and elite status requirements, which may not appeal to everyone.
The value of perks like statement credits or elite status depends entirely on your personal travel and spending habits—unused benefits can negate the card's appeal.
Some cards offer more straightforward earning and redemption structures, which may suit those who prefer less complexity.
What you'll miss from the article
A detailed breakdown of how to evaluate whether a premium credit card aligns with your travel habits and spending patterns to maximize value.
Generated by AI with support from our editorial team.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Premium credit cards are often marketed as the ultimate tool for travelers, packed with perks like airport lounge access, travel credits, elite status and elevated earning rates. But with annual fees that can reach almost $900, many people wonder: Are these cards truly worth the cost?
The truth is, these cards can deliver tremendous value — or end up costing you more than they're worth. It all depends on your travel habits, spending patterns and how much you'll take advantage of what's offered.
Here's how to tell whether a premium card deserves a spot in your wallet.
Before we dive into the details, let’s take a moment to understand what makes a credit card premium.
Premium credit cards represent the top tier of the rewards card ecosystem. These high-end cards typically come with hefty annual fees (from $395 to nearly $900) but also offer an impressive lineup of perks. Think: airport lounge access, elite hotel or airline status, generous statement credits, enhanced travel protections and accelerated points earning.
RISKA/GETTY IMAGES
They're designed for frequent travelers and big spenders who can maximize the value of the benefits. But premium doesn’t mean one-size-fits-all; what’s valuable to one cardholder might not be worth it to another.
Some of the most popular premium credit cards on the market include:
When a premium credit card is worth the annual fee
When are premium credit cards worth the fee? Here are a few signs a premium credit card might belong in your wallet.
You'll use the statement credits
Many premium cards make it surprisingly easy to offset most (if not all) of your annual fee through statement credits alone. But these credits only have value if you actually use them.
For example, the Chase Sapphire Reserve offers an up to $300 annual travel credit that automatically applies to a wide range of purchases, from airfare and hotels to parking and tolls.
If those credits match your lifestyle, your annual fee could easily pay for itself. But if you won't use them — say, you rarely use ride-hailing services or don't stay in hotels often — the value disappears quickly.
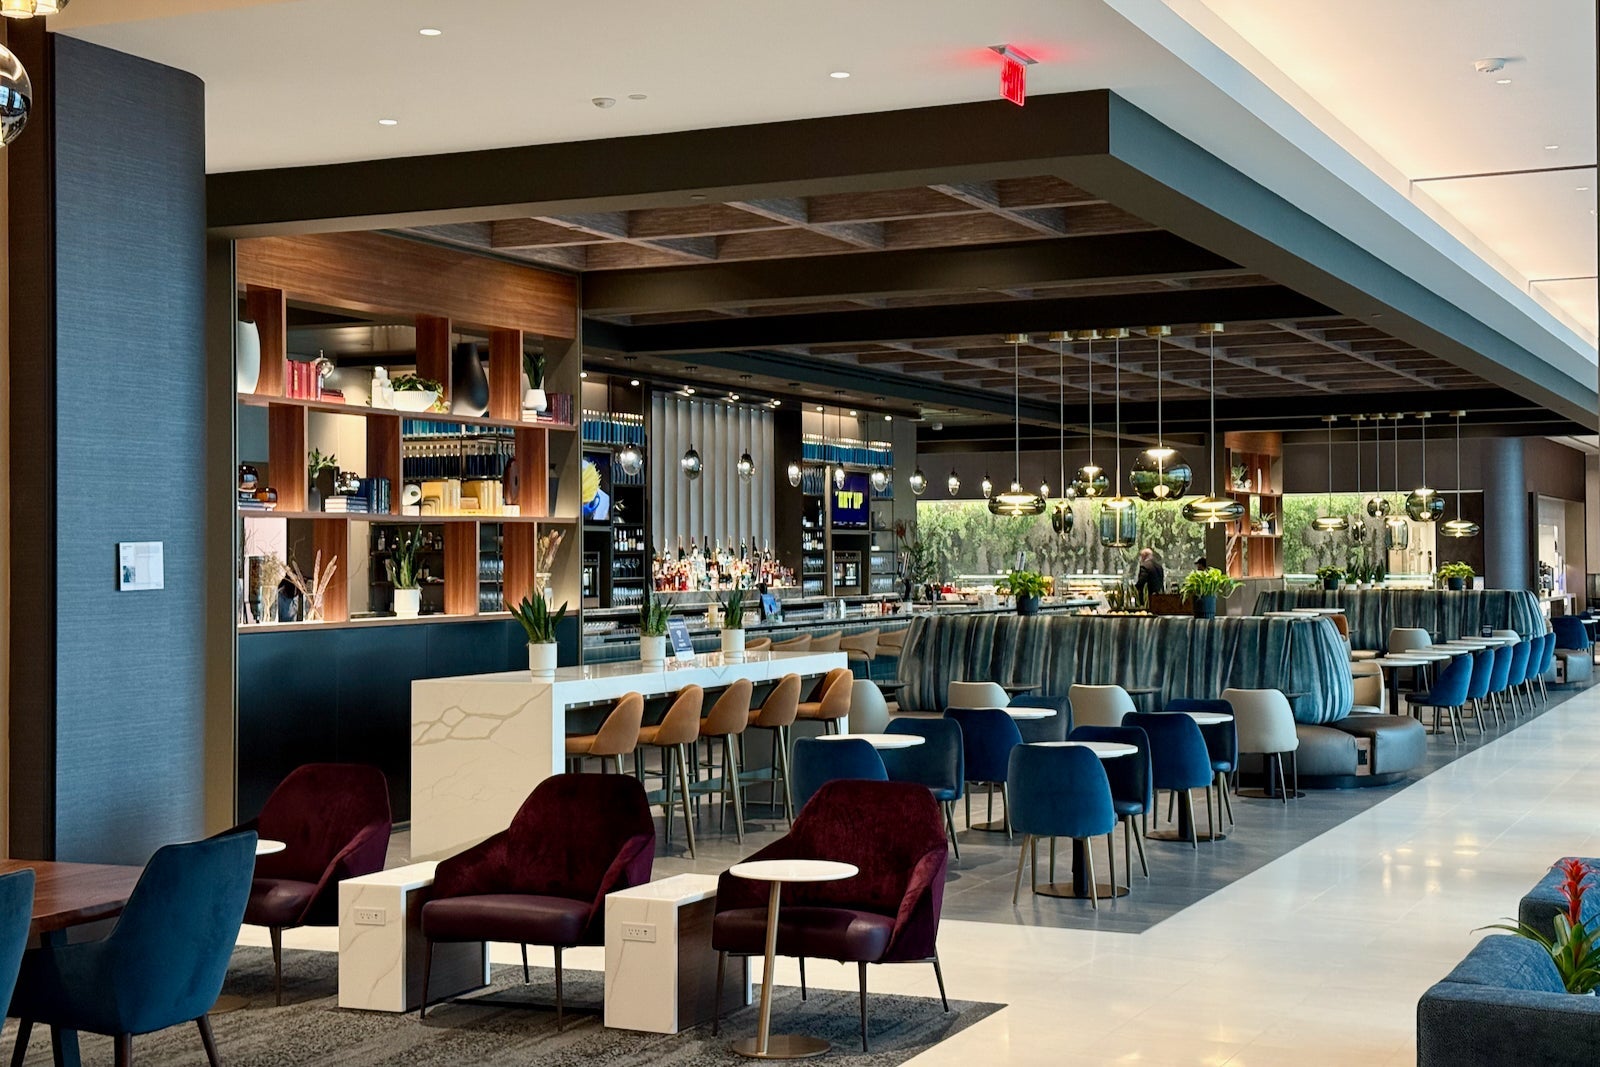
You value airport lounge access and travel perks
For many travelers, airport lounge access alone can make a premium card worth keeping. The Amex Platinum offers the most comprehensive access of the cards above, including to Centurion Lounges, Delta Sky Clubs (when flying Delta) and Priority Pass lounges (enrollment required).
If you're someone who spends hours in airports each month, these perks can easily outweigh the annual fee. However, if you only travel once or twice a year, it might be smarter to opt for a lower-tier travel rewards card, such as the Citi Strata Premier® Card (see ) instead.
Premium cards often offer automatic elite status with airline or hotel partners, which is a benefit that can elevate your travel experience even further.
Premium cards tend to offer higher earning rates and more flexible redemption options than lower-tier travel rewards cards. The Sapphire Reserve, for instance, earns 3 points per dollar on dining and 8 points per dollar on Chase Travel℠ bookings.
Meanwhile, Amex Platinum cardholders earn 5 points per dollar on flights booked directly with airlines or through American Express Travel® (on up to $500,000 per calendar year, then 1 point per dollar), which is a high rate of return for frequent flyers.
For instance, Chase Ultimate Rewards points can be transferred to programs like Air France-KLM Flying Blue and World of Hyatt, where they can unlock significantly more value than a simple cash-back redemption.
This is especially true when a transfer bonus is in play. I recently took advantage of a 25% transfer bonus while booking a flight to Paris. The flight cost 18,750 Flying Blue miles, but thanks to the bonus, I only needed to transfer 15,000 Chase points to cover it.
When a premium credit card is not worth the annual fee
Premium credit cards come packed with perks, but those benefits only matter if you actually use them. For some cardholders, the high annual fee just doesn’t make sense based on their spending or travel habits.
Here are a few signs a premium credit card might not be the right fit for you.
You won't use the travel perks
At the end of the day, premium cards are designed for people who travel and travel often. If your lifestyle doesn't include regular flights, hotel stays or time spent at airports, many of these benefits will go unused.
You'll likely be better off with a mid-tier travel card that still earns value points but has a lower annual fee, like the Chase Sapphire Preferred® Card (see ) — one of our favorite starter travel cards here at TPG — and one of the top cards in my wallet.
Premium card annual fees reach into the hundreds of dollars (and potentially soon into the thousands). Those fees can be worth it if you can maximize credits, lounge access and transfer partners, but if you don't, the math may not add up.
PEKIC/GETTY IMAGES
If you want to keep your costs low, a no-annual-fee card like the Citi Double Cash® Card (see ) may be a better fit.
Premium cards often come with complex benefits, earning structures, and redemption options that can be overwhelming if you're not deep into the points and miles world. If that sounds like you, a premium card might not be the best fit — though there are a few exceptions.
For example, the Capital One Venture X offers one of the more straightforward earning structures, earning at least 2 miles per dollar on every purchase and 5-10 miles per dollar spent on travel booked through Capital One's travel booking site. You'll still enjoy premium perks like airport lounge access and travel protections without the need to memorize bonus categories or monthly credits.
However, if you prefer to skip the premium tier and annual fees entirely, the Chase Freedom Unlimited® (see ) is a strong choice, earning at least 1.5% cash back on every purchase.
Between monthly credits, lounge access rules, bonus categories and elite status requirements, maximizing a premium card requires some effort. If you don't want to monitor expiring credits or jump through hoops to activate perks, you might not get full value out of a premium card.
Instead, you might try a straightforward card like the Wells Fargo Active Cash® Card (see ), which has no rotating categories and no travel credits to remember.
Premium credit cards can absolutely be worth the annual fee, but only if you'll take advantage of what they offer. Frequent travelers who use the statement credits, enjoy lounge access and maximize reward redemptions will easily come out ahead.
If those perks align with your spending habits, a premium card like the Amex Platinum, Chase Sapphire Reserve or Hilton Aspire can pay for itself year after year. But if you're not likely to use the benefits, consider a lower-fee option and save your money for your next trip instead.