The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Guides
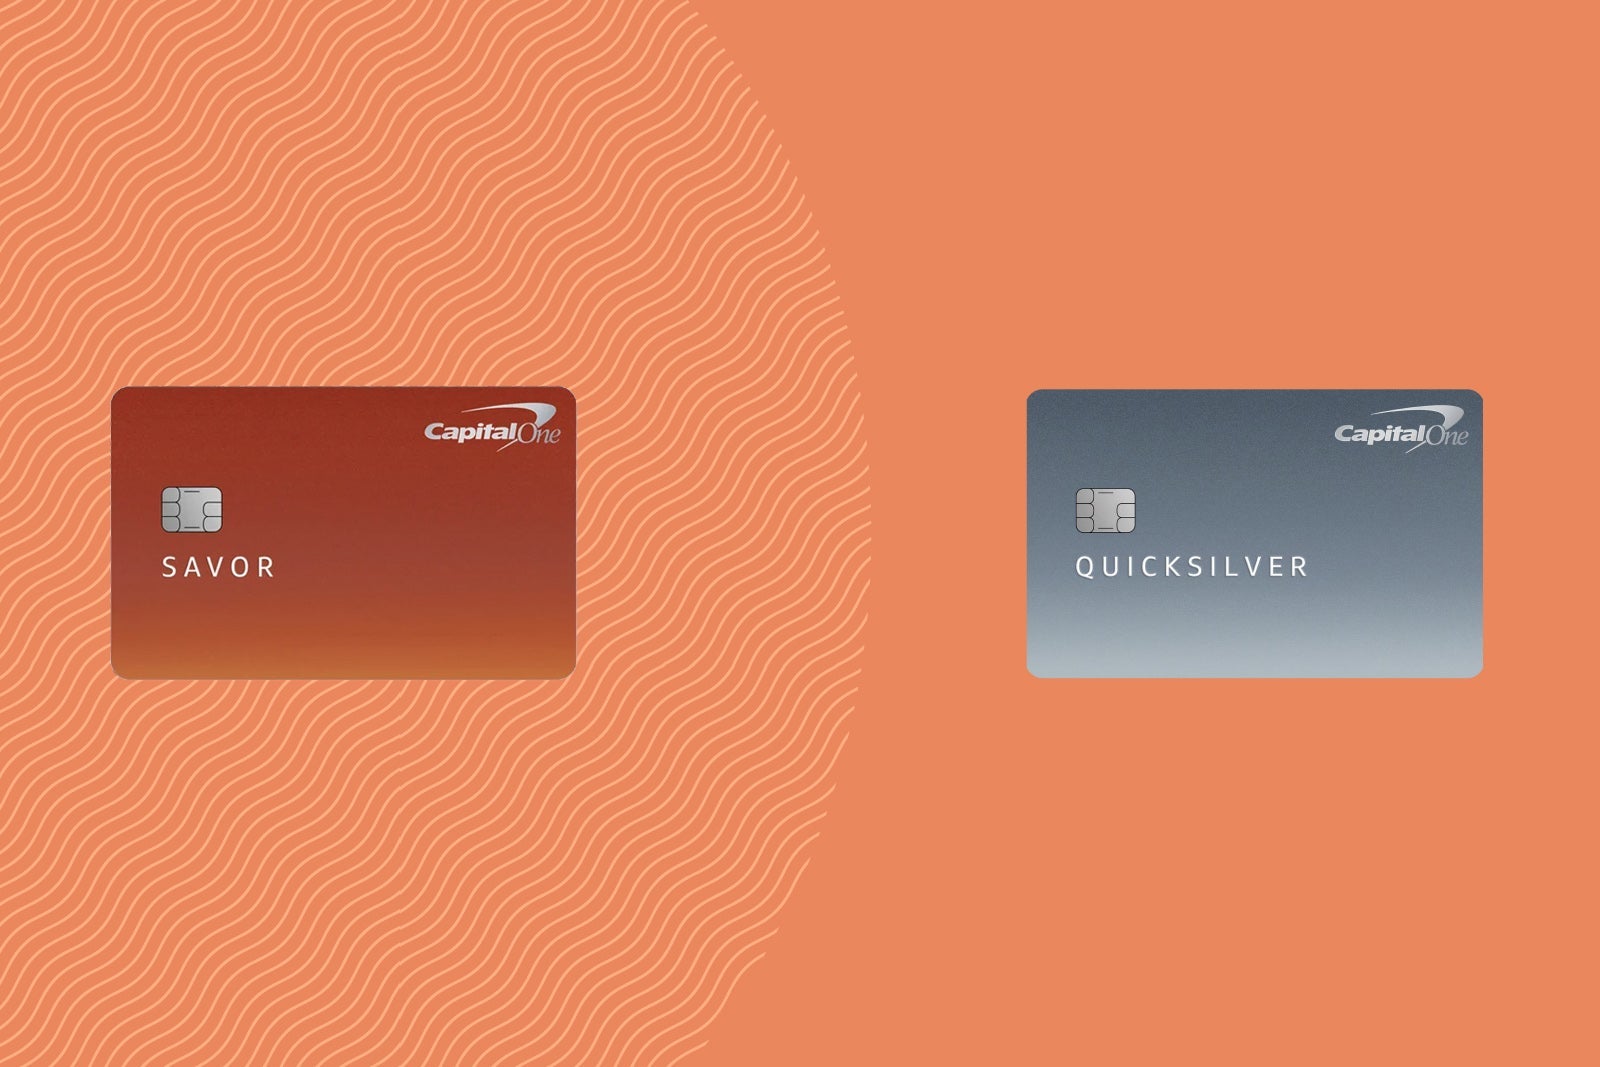
Capital One Savor vs. Capital One Quicksilver: Supercharge your leisure spending, or earn flat cash back?
Augusta Stone is a credit cards writer for TPG. She joined the TPG team in 2023 and is excited to take points and miles beginners with her on a journey toward maximizing rewards.
Credit card writer Danyal Ahmed is an avid traveler, averaging about 100,000 aeronautical miles per year. He regularly applies that knowledge and his expertise in credit cards to his role as a credit card writer at TPG.
also contributed to this story
March 13, 2025 • 7 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.
Editorial note: This is a recurring post, regularly updated with new information and offers.
Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
Cash-back cards appeal to those seeking straightforward rewards and flexible redemption options.
Two leading cash-back options are compared, both offering similar perks and no annual fee.
One card provides higher rewards at select merchants like grocery stores, dining, entertainment and streaming, while the other offers a fixed rate at all merchants.
Both cards allow cash-back redemption as statement credits, credits toward purchases, shopping at select online retailers or as gift cards.
What to consider
Eligibility for these cards may be affected by application rules, including limits on how frequently you can open new accounts.
Both cards waive foreign transaction fees and offer benefits such as concierge services, extended warranty protection and travel accident insurance.
The main difference lies in earning rates: one card is better for maximizing select categories, while the other suits those preferring simplicity across all merchants.
What you'll miss from the article
A detailed side-by-side comparison of earning rates, benefits and ideal user profiles for each cash-back card.
Generated by AI with support from our editorial team.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
With the Capital One Savor, you can earn a one-time $200 cash-back bonus after spending $500 on purchases in three months from account opening. With the Capital One Quicksilver, you can earn a one-time $200 cash-back bonus after spending $500 on purchases in three months from account opening.
When you go to apply, remember that Capital One has some potentially confusing application rules that might restrict your eligibility for either card.
The issuer is also known to restrict consumers to opening just one new card every six months, so if you’ve applied for another Capital One product within that time frame, you might want to hold off.
Winner: Tie. The same offer is available on both cards.
Capital One Savor vs. Capital One Quicksilver benefits
Earning cash back with the Capital One Savor vs. Capital One Quicksilver
The real difference between these two cards comes into play with their earning rates.
The Capital One Quicksilver is an appealing option for anyone looking for simplicity, as the card earns at least 1.5% cash back on all purchases.
This falls in line with competitors from other issuers, such as the Chase Freedom Unlimited® (see ), but it’s less than you can expect with other cards, such as the Citi Double Cash® Card (see ).
PIXDELUXE/GETTY IMAGES
By contrast, the Capital One Savor could be a better choice for those willing to manage bonus categories in their card strategy. The card is also a good option if you frequently dine out, shop for groceries or attend live events.
When you pay with the Savor Rewards, you'll earn:
3% cash back on purchases at grocery stores (excluding superstores like Walmart and Target)
3% cash back on dining
3% cash back on entertainment
3% cash back on popular streaming services
Both cards will earn 5% on hotels, vacation rentals and rental cars booked through Capital One Travel.
Winner: Savor. You have more opportunities to earn bonus cash back than with the Quicksilver.
Redeeming cash back with the Capital One Savor vs. the Capital One Quicksilver
Both are cash-back cards, plain and simple. You can redeem your cash back in different ways, including as statement credits, as credits toward previous purchases, by shopping at Amazon, by checking out with PayPal or as gift cards.
MARKO GEBER/GETTY IMAGES
These are all good redemption options for cash-back credit cards. Since you aren't dealing with points and miles, you don't need to worry about picking the right redemption option for maximizing value. Your cash back will always be worth the same amount, regardless of how you redeem it.
Winner: Tie. The two cards have the same redemption options.
Should I get the Capital One Savor or the Capital One Quicksilver?
It depends on where you spend your money. Since the cards have so many similarities outside of their earning rates, consider your spending habits before you make a decision. The Capital One Quicksilver is a great option for folks who tend to make purchases at a wide variety of merchants. Conversely, the Capital One Savor is tailor-made for people who spend a lot on dining, entertainment and groceries.
Both the Savor and the Quicksilver are strong cash-back options with many similarities. The decision will come down to whether you'll maximize the Savor's bonus categories or appreciate the Quicksilver's fixed-rate cash back.
Consider how you spend before you make a choice, and you'll be set to rack up cash-back rewards.
For Capital One products listed on this page, some of the benefits may be provided by Visa® or Mastercard® and may vary by product. See the respective Guide to Benefits for details, as terms and exclusions apply.