The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Guides
How this mom and business owner improved her credit score from 550 to 800
Stella is a full-time writer with expertise in credit cards, points and miles, and all things travel. She is a journalism graduate of the University of North Carolina, Chapel Hill and previously worked as a copywriter at JetBlue Airways and as a credit cards writer at LendingTree.
September 21, 2021 • 8 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
The article shares Dayna Bolden's journey from a low credit score to financial stability and entrepreneurship.
Dayna emphasizes the importance of paying balances in full and keeping credit utilization low to rebuild credit.
She highlights the value of educational resources and tools for managing credit and finances, especially for students and new credit users.
Her story illustrates how responsible credit management can support both personal and business financial goals.
What to consider
Some offers and products mentioned may no longer be available, as noted in the article update.
High interest rates and missed payments can significantly hinder credit-building efforts, especially for those starting out.
Educational resources and preapproval tools can help consumers make informed decisions without impacting their credit scores.
What you'll miss from the article
Personal strategies and actionable tips for rebuilding credit and leveraging financial tools for business and personal growth.
Generated by AI with support from our editorial team.
Update: Some offers mentioned below are no longer available. View the current offers here.
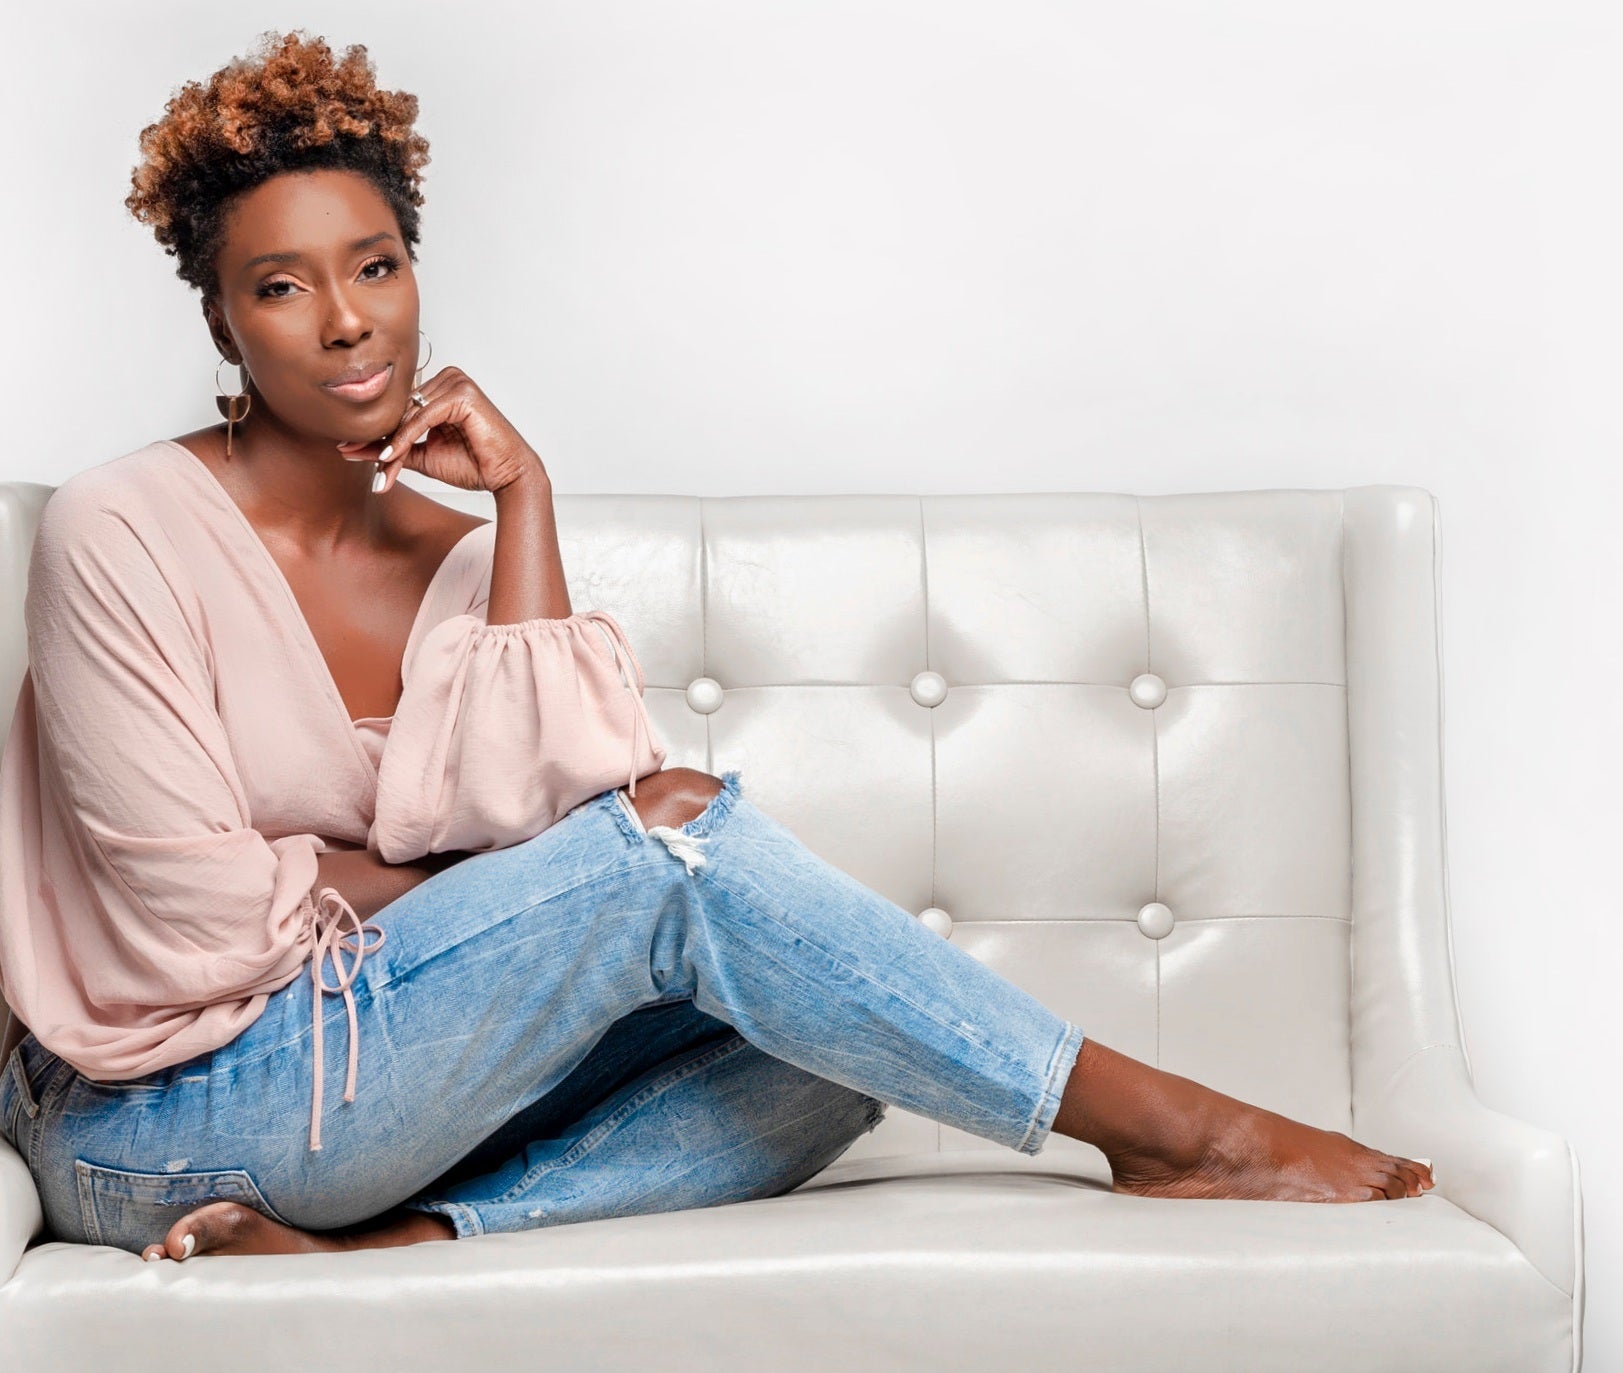
If your credit score is less than ideal, you're not alone. Lifestyle blogger Dayna Bolden graciously shared her financial journey with TPG — initially off to a rocky start, she held a credit score of 550 due to missed payments on her first credit card.
One of Dayna's passions is financial literacy, and her credit journey is an integral part of pursuing her dream to work for herself full time. After hearing about her path to financial freedom and entrepreneurship, I was inspired as I talked to Dayna about all things credit and small business-related.
Credit mistakes early on
Dayna's success wasn't linear. She opened her first credit card as a college student: The Capital One Platinum Credit Card. With no credit history beforehand, the Capital One Platinum is an easier card to get approved for and even comes with a preapproval tool to see in advance if you'll qualify.
While this card offers a line of credit for those who may have a challenging time seeking approval from other top rewards credit cards, the annual percentage rate is quite high. With a 30.74% variable APR (see rates and fees), the Platinum Mastercard comes with one of the highest interest rates — which brought Dayna into trouble as she missed payments early on in her credit journey.
Avoid paying interest by making sure you pay in full on time. (Photo by Pormezz/Shutterstock)
"My biggest mistake was keeping high balances," said Bolden. "I kept my credit card balances at almost 100% maxed out, and I only paid the minimum. But now, I want to educate everyone that paying on time is absolutely crucial, and you'll never want to keep those high balances."
If you're new to credit — or perhaps you're rebuilding your credit if you've fallen victim to similar mistakes — you'll want to review TPG's 10 commandments for credit cards. While all the commandments are essential reads, the first one is the most crucial: "Thou shalt pay thy balance in full."
While Dayna wasn't informed about points and miles back in the day (her Platinum Mastercard didn't offer rewards). Capital One actually has several student cards in its lineup that offer easy approval for college students and the opportunity to earn rewards at the same time. Dayna has even partnered with Capital One to share the recent release of the two new student credit cards, the Capital One SavorOne Student Cash Rewards Credit Card and the Capital One Quicksilver Student Rewards Credit Card.
The Capital One SavorOne Student offers $50 when you spend $100 in the first three months and 3% cash-back rewards on dining, entertainment, popular streaming services, and grocery stores (excluding superstores like Walmart® and Target®) and 1% on all other eligible purchases. On the other hand, the Capital One Quicksilver Student offers $50 when you spend $100 in the first three months and a simple 1.5% cash-back rewards rate on other eligible purchases. Both cards have no annual fee and even waive foreign transaction fees if you're a college student thinking about studying abroad.
The rewards aren't the only persuading aspect of these two student-centric cards. Dayna also shares Capital One's free resource hub for money management, offering dozens of articles that help consumers learn how to check their credit scores, pay off debt, and more.
"I'm able to share and educate my community — whether they are college students or if they're parents of college-aged kids," said Bolden. "I'm able to properly educate them of financial wellness based on my own experiences and mistakes."
Starting her business
(Photo by Dayna Bolden)
Years later, she worked on rebuilding her credit but learned to manage her finances better thanks to checking her credit score right on the Capital One app and setting up autopay. She also kept her utilization ratio low and was steadfast about never missing a payment — which helped her see gains in her credit score.
"Once I got to the credit building stage and wanted to open my business, I applied for a business bank account through Capital One because of my long-standing relationship with the bank," said Bolden. "I also opened a Capital One business cash-back card, which helps me earn cash-back rewards on all my business expenses, again because I was comfortable and trusted the issuer since I started with bad credit."
Dayna loves using her cash-back rewards to treat herself or her family to a nice dinner or help with travel expenses. While it took her almost a decade, her determination to always pay bills on time and in full has paved the way to a fantastic credit score — all of which are important for securing mortgages, business and car loans and so much more.
Bottom line
Your credit is one of the pillars of financial excellence, and Dayna's story demonstrates how it's never too late to get back on the right track. Brian Kelly, The Points Guy himself, started on a similar path with bad credit. With patience and hard work, Dayna not only raised her credit score but was eventually able to become a full-time entrepreneur. Now, she's earning cash-back rewards that help her family offset those extra expenses or buy something fancy, all thanks to various tools and resources that helped her reset.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.