The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Guides
Why I pay $890 a year to carry 2 Chase Sapphire cards
Augusta Stone is a credit cards writer for TPG. She joined the TPG team in 2023 and is excited to take points and miles beginners with her on a journey toward maximizing rewards.
June 30, 2026 • 10 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
Holding two premium travel cards with a combined annual fee near $900 can seem excessive, but strategic use of their benefits can yield over $2,000 in value annually.
One card is used for major travel bookings and offers premium perks like airport lounge access, while the other is favored for everyday purchases such as rideshares, gas and online groceries.
Statement credits for travel, dining, entertainment and hotel bookings can significantly offset the total annual cost if fully utilized.
Maximizing both cards requires careful tracking of credits and spending categories, but can be worthwhile for frequent travelers.
What to consider
The value of holding both cards depends on your ability to maximize statement credits and use travel-related perks.
Some benefits, such as monthly ride credits and hotel credits, have specific eligibility windows and usage restrictions.
Those who prefer simplicity or do not travel often may find a single card or a different rewards structure more suitable.
What you'll miss from the article
A detailed breakdown of how to divide spending between two premium cards and real-world examples from multiple users on maximizing combined benefits.
Generated by AI with support from our editorial team.
An $890 price tag for two cards appears quite jarring.
Since they're both Sapphire cards, it would be reasonable to assume there's too much overlap to justify carrying both.
But I'll let you in on my strategy: Between the statement credits and benefits I actually use, I get more than $2,000 in value each year before I even factor in welcome bonuses or the value of the Chase Ultimate Rewards points I earn.
Here's why carrying both Sapphire cards works for me.
How I divide spending between the Sapphire Reserve and Sapphire Preferred
I pair the Sapphire Reserve with the Sapphire Preferred to supercharge my points earning. I don't think of them as competitors; I think of them as teammates.
I use the Sapphire Reserve for big travel purchases
Whenever I'm booking flights or hotels directly, I reach for my Sapphire Reserve. Earning 4 points per dollar on those purchases is one of the biggest reasons I keep the card.
Since Hilton is the only hotel brand where I have a cobranded card, I turn to my Sapphire Reserve whenever I'm booking directly with Hyatt, Marriott or IHG. Booking directly also means I don't have to worry about the downfalls of using a travel portal, such as missing out on elite-qualifying credits, benefits or hotel points.
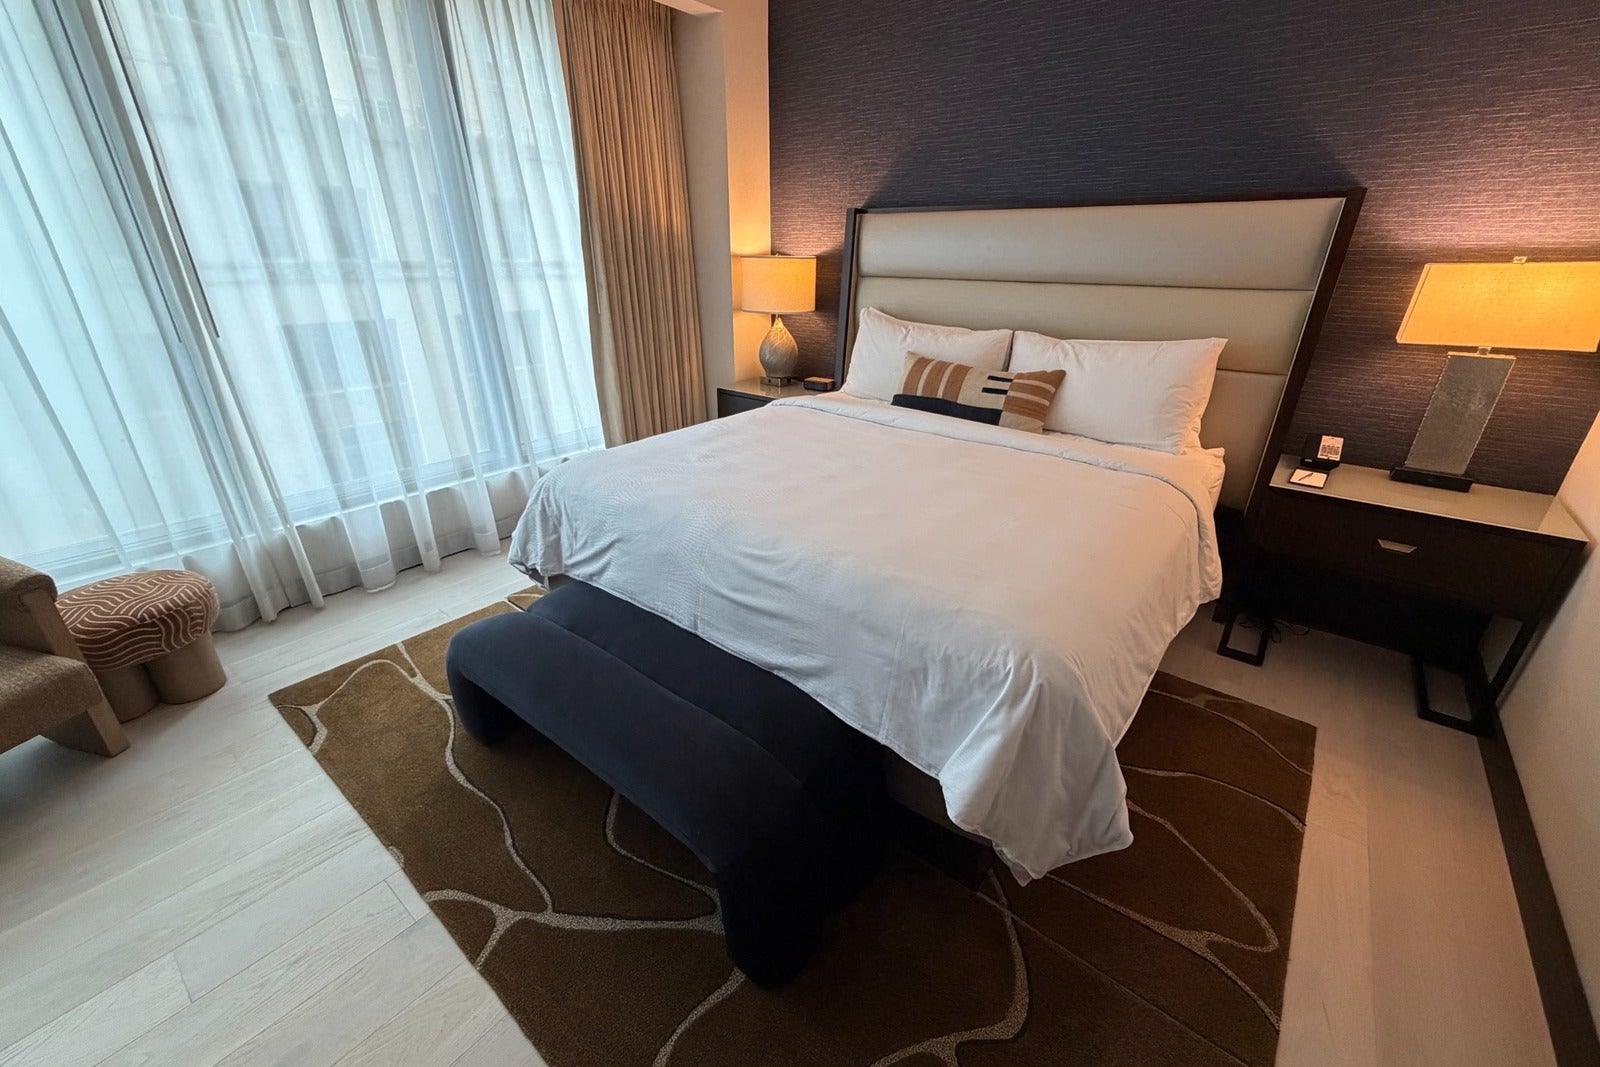
JW Marriott Houston Downtown. SUMMER HULL/THE POINTS GUY
I also reach for the Sapphire Reserve whenever I'm booking through Chase Travel℠ because it earns 8 points per dollar spent. If I'm staying through The Edit, I can stack those bookings with my annual statement credits* while still earning 8 points per dollar on eligible purchases beyond the credit.
*Two up to $250 credits that can be used any time, but cannot be combined; minimum two-night stay required, must be prepaid
I use the Sapphire Preferred for everyday spending
The Sapphire Preferred is my default card forgeneral travel (excluding flights and hotels booked directly) because it earns 2 points per dollar spent on purchases like ride-hailing, car rentals, trains and subways. Those expenses add up quickly when I travel, so this is a game changer for me.
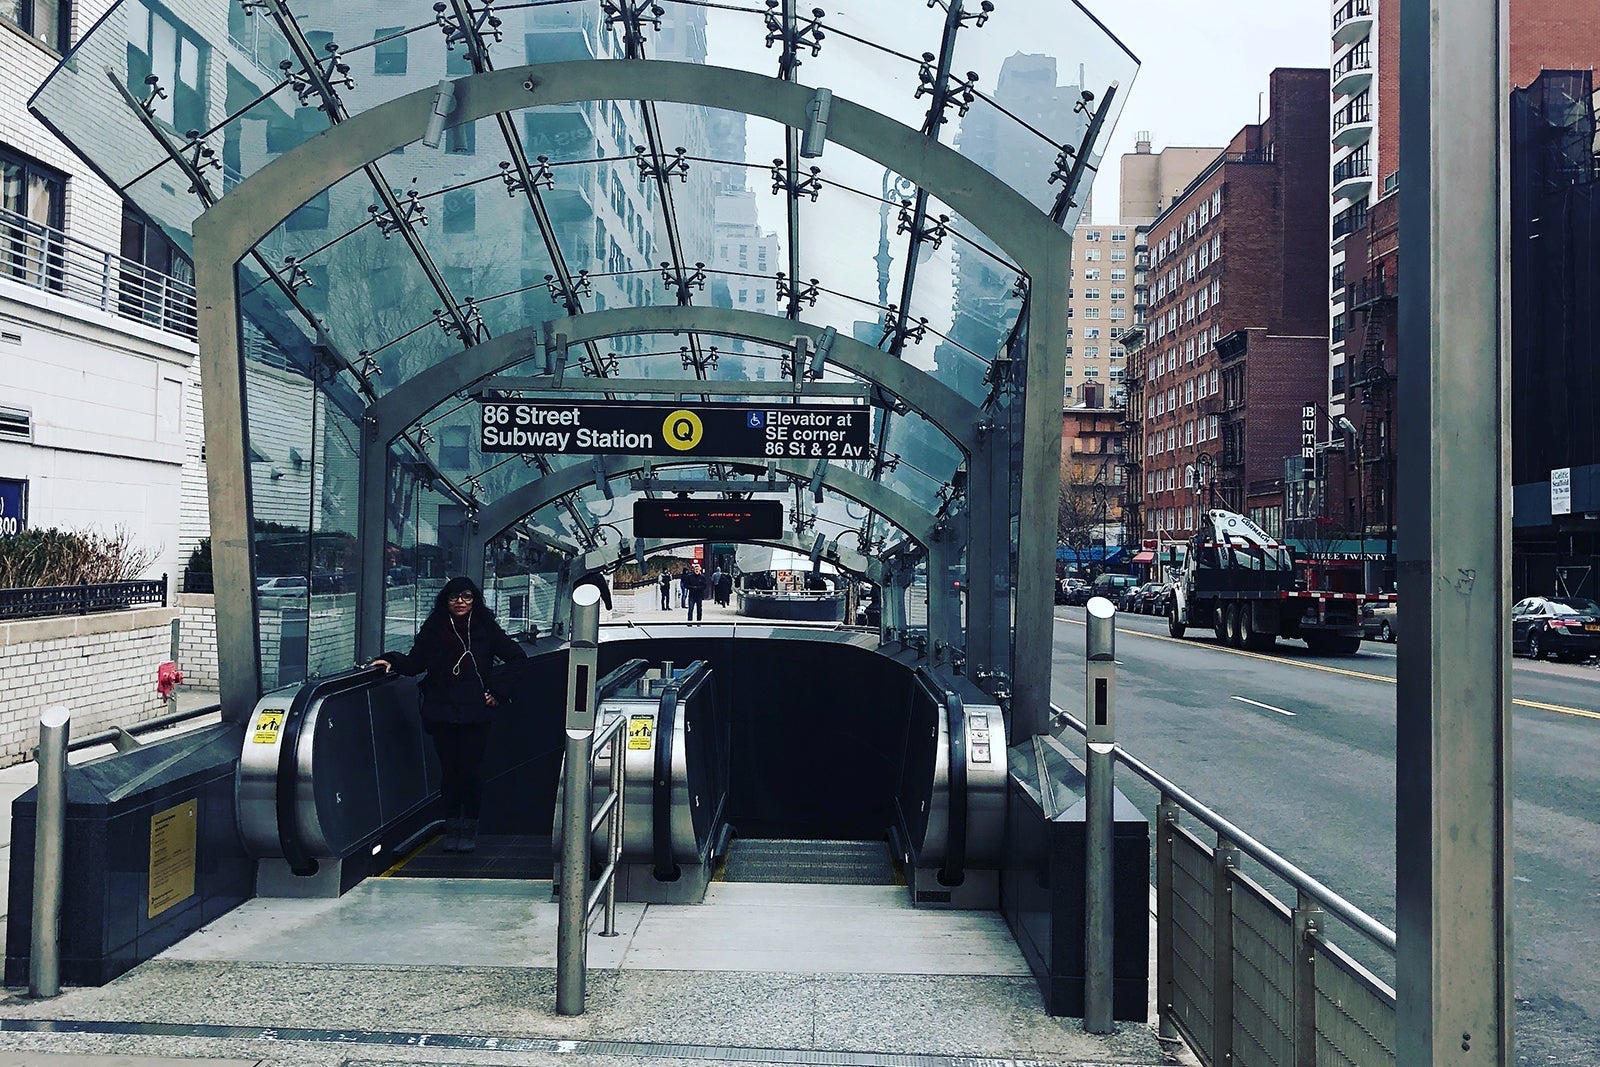
The 86th Street Station of the Second Avenue subway. CLINT HENDERSON/THE POINTS GUY
I also use the Sapphire Preferred for purchases that fit naturally into my day-to-day routine.
It earns 3 points per dollar spent on online groceries (excluding Target, Walmart and wholesale clubs), which is perfect since I enjoy cooking at home. I'm also frequently hitting the road, so it's nice to now earn 3 points per dollar spent on gas purchases made with the Sapphire Preferred.
Finally, I rely on it when booking eligible vacation rentals through brands like Airbnb, Vrbo, Plum Guide, HomeAway, Homestay.com and Vacasa, where it also earns 3 points per dollar.
When both cards work
I can use either the Sapphire Preferred or the Sapphire Reserve when dining out, as both earn 3 points per dollar spent on dining worldwide (including takeout and eligible delivery services).
The exception is when I'm using the Sapphire Reserve's $150 biannual statement credit for Sapphire Reserve Exclusive Tables, since that requires paying with the Reserve. (Note that your Sapphire Reserve must be added to your OpenTable account to earn this credit.)
I also keep the Sapphire Reserve in my Lyft account because I receive up to $10 in monthly in-app credits on Lyft rides (through Sept. 30, 2027, does not apply to Wait & Save, bike or scooter rides), even though it has the same earning rate as the Sapphire Preferred.
How I get value from each Sapphire card
I'm the type of cardholder who's going to maximize as many benefits as possible. If I'm paying annual fees, I'm going to get the most out of them.
Why the Sapphire Reserve earns its annual fee
The Sapphire Reserve does most of the heavy lifting.
I plan to use the Sapphire Reserve's statement credit on The Edit later this year. Since the benefit comes as two up-to-$250 credits that can be used any time throughout the year (but can't be combined), I can use it at any time throughout the rest of 2026.
LONDON MARRIOTT HOTEL PARK LANE/FACEBOOK
Beyond travel, I also get plenty of value from the Reserve's entertainment and dining perks.
I redeemed the first $150 of the card's up to $300 StubHub and Viagogo statement credit (activation required) to see Sombr this fall. I plan to use the next half for football tickets.
I also take advantage of the Sapphire Reserve Exclusive Tables dining credit (split into a $150 credit from January through June and $150 from July through December) at one of my favorite restaurants in Greenville, South Carolina.
Even though I use Uber and Lyft in tandem, I'll go with Lyft if I haven't used my $10 monthly in-app credit yet. I also find it easy to redeem the $15 monthly promo for DoorDash restaurants (through Dec. 31, 2029).
Beyond statement credits, the Sapphire Reserve also offers travel perks I use on nearly every trip.
CARLY HELFAND/THE POINTS GUY
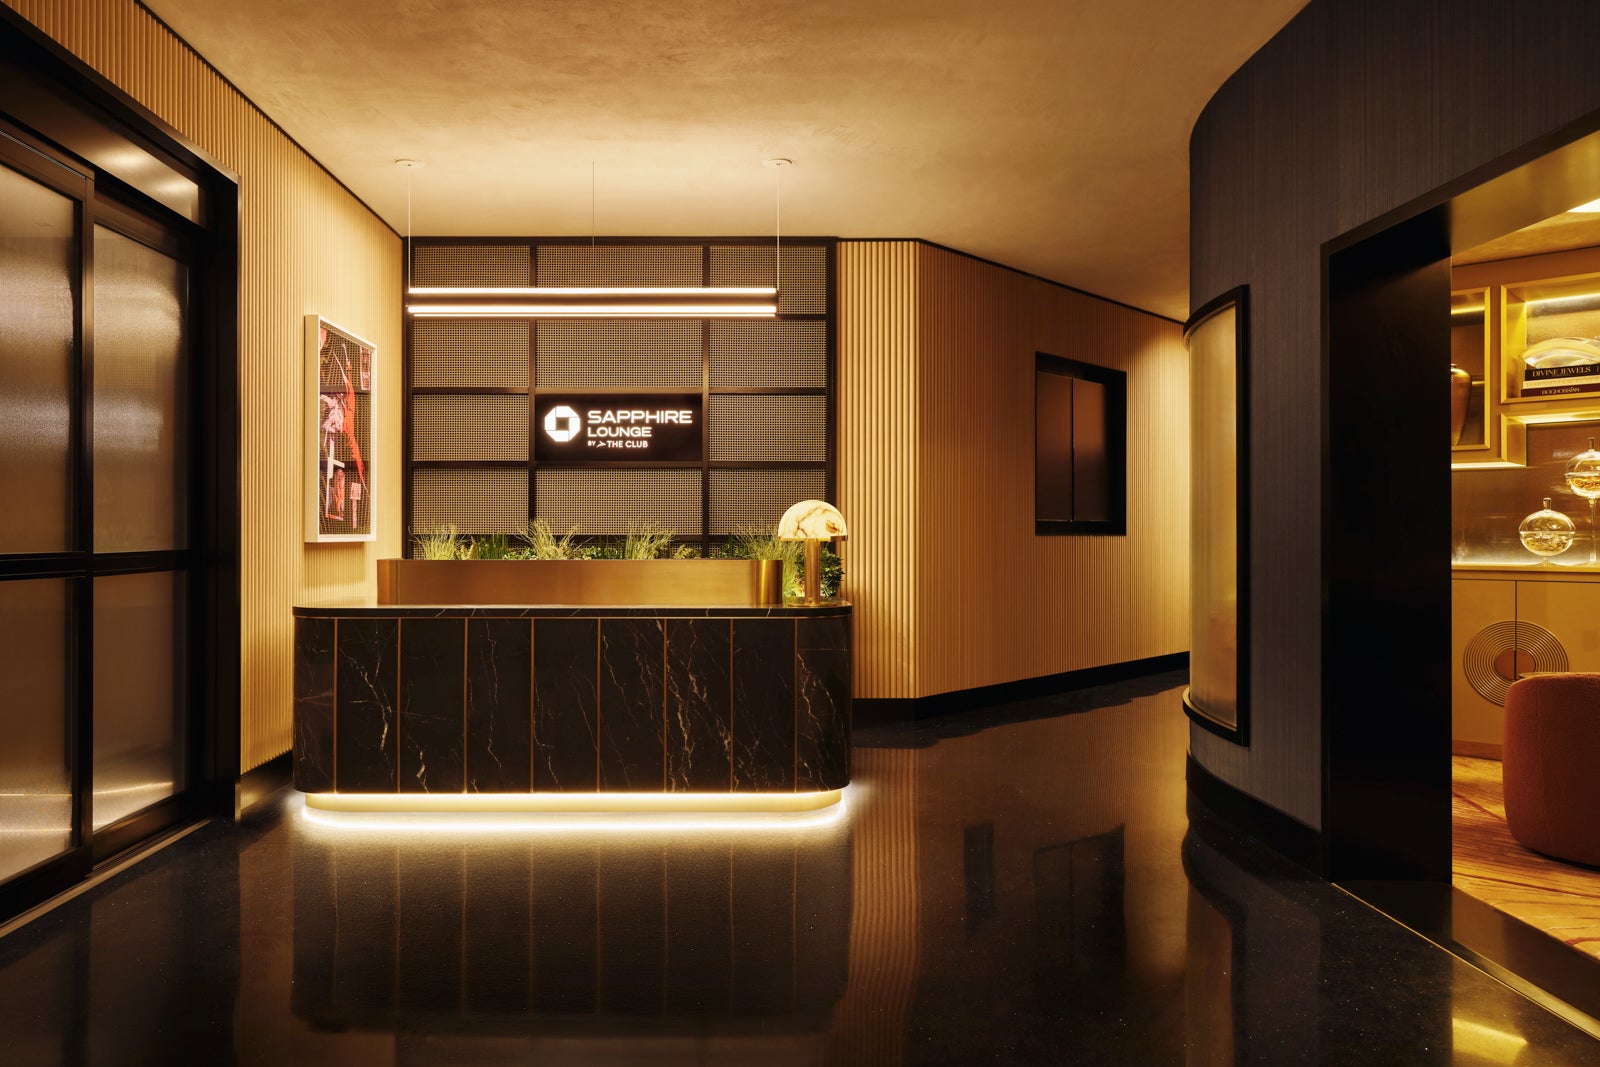
The premium Sapphire Reserve comes with airport lounge access that the Sapphire Preferred lacks.
I am a big fan of lounges, especially the TPG Award-winning Chase Sapphire Lounges,so this is a major factor in my decision to keep the premium card open.
I lean on the Sapphire Reserve to redeem Chase points through Chase Travel. Thanks to Points Boost, I get up to 2.5 cents per point on select hotel and flight bookings made through Chase Travel.
The Sapphire Preferred's $100 annual hotel credit on prepaid Chase Travel bookings more than offsets the card's $95 annual fee for me. This is awarded every anniversary year.
Paying nearly $900 for two credit cards may seem excessive to some, but the math works out easily for me.
For one, I redeem up to $1,580 back each year just from maximizing the statement credits that I use on the premium Sapphire Reserve. Plus, that's not even factoring in the value of the points I earn when I pay with the card or the value I place on airport lounge access.
Even though the Sapphire Preferred doesn't offer as many unique statement credits, its $100 annual Chase Travel hotel credit offsets the $95 annual fee on its own.
If you add in the value of the card's overlapping benefits: two Global Entry, TSA PreCheck or Nexus statement credits (worth up to $120 each every four years), one DoorDash DashPass membership (up to $120 each year, activation required) and the $180 Apple TV subscription (activate by Dec. 31), I've gotten about $2,140 in easy-to-redeem value from both of these cards (in years when I use the Global Entry credit).
I don't use Apple Music, so I don't factor that in here.
Compare that to the $890 in annual fees I pay, and it's easy to see why I keep both cards. That's before I even factor in the value I get from airport lounge access or the Ultimate Rewards points I earn through everyday spending.
This article focuses on my strategy, but I'm not the only TPGer who has both. Here are some examples from my colleagues:
Lyndsey Matthews, points and loyalty programs managing editor
Lyndsey said she got the Sapphire Reserve because of its bonus and the ability to offset a chunk of the annual fee by using the $300 travel credit immediately to "soften the blow" of a last-minute flight she booked to Key West.
LYNDSEY MATTHEWS/THE POINTS GUY
She also easily maximizes the dining and StubHub credits as a New York City resident who frequents Broadway shows.
Christine Gallipeau, points and loyalty programs senior editor
Christinesaid her Sapphire Reserve has become the go-to card for major travel purchases — namely, flight and boutique hotel bookings made outside Chase Travel due to its 4 points per dollar spent earning rate.
The Sapphire Preferred has been the card she leans on for many everyday purchases, including Lyft rides (through Sept. 30, 2027), streaming service subscriptions and eligible online grocery orders.
Olivia Mittak, credit cards editor
Olivia said it's very easy for her to justify keeping the Sapphire Preferred thanks to its recent refresh.
Olivia plans to use the Sapphire Preferred's upgraded $100 Chase Travel hotel credit alongside her new Sapphire Reserve's multiple travel credits to save a lot of money on her travels.
Who shouldn't hold both the Sapphire Preferred and Sapphire Reserve?
For me, the cards are certainly worth it. But if you aren't willing to maximize their benefits, this combination may not be for you. Here are some examples of spenders who shouldn't hold both cards:
If you aren't interested in tracking statement credits or managing bonus categories across two cards, this combination isn't for you.
If you don't travel often, you'll miss out on the most valuable perks, including lounge access, earning bonuses and travel-related statement credits.
If you don't value transferable points or partners like World of Hyatt, a simpler cash-back card may serve you better.
If you're above Chase's 5/24 limit, you won't be approved for either card until you're back under it.
This is one of my favorite card combinations on the market. With the Sapphire Reserve offering premium travel benefits and the Sapphire Preferred providing bonus points on a wide range of everyday purchases, these cards easily earn their spots in my wallet.
If you're unsure if this strategy would work for you, consider running the math on your own spending. A combined $890 in annual fees could sound steep, but once you add up the statement credits and benefits you get access to, it could make sense for the right kind of spender.
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.