The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Guides
How to find the best pre-qualified credit card offers
Madison Blancaflor is the managing editor for TPG's content operations team. She focuses on helping TPG's broader editorial team bring news, features and advice to readers. She has nearly six years of experience covering the credit cards and travel industries.
Stella is a full-time writer with expertise in credit cards, points and miles, and all things travel. She is a journalism graduate of the University of North Carolina, Chapel Hill and previously worked as a copywriter at JetBlue Airways and as a credit cards writer at LendingTree.
also contributed to this story
May 13, 2024 • 10 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
Pre-qualified credit card offers help applicants identify cards they are likely to be approved for without a hard inquiry on their credit report.
Tools like CardMatch and issuer-specific pre-qualification portals can reveal targeted or elevated offers not available to all applicants.
Pre-qualified offers are based on a soft credit pull and do not guarantee approval; a formal application is still required for final approval.
Pre-qualification is distinct from preapproval, with each carrying different implications for targeted marketing and approval likelihood.
What to consider
Pre-qualified and preapproved offers result from a soft credit pull and do not impact your credit score.
Offers found through pre-qualification tools can change at any time and may not always match public promotions.
Receiving a pre-qualified or preapproved offer does not guarantee approval, as a formal application and full review are still required.
What you'll miss from the article
A detailed guide to using pre-qualification tools and understanding the differences between pre-qualified and preapproved offers.
Generated by AI with support from our editorial team.
Update: Some offers mentioned below are no longer available. View the current offers here.
With each issuer using its own approval criteria for applications, it can be hard to know which credit card offers you are likely eligible to receive. This can be especially difficult if you don’t have a long credit history or a good credit score.
That’s where pre-qualified offers — and the tools you use to find them — can come in handy. Not only do pre-qualified offers help you figure out which cards you are most likely to be approved for, but they can also help you find targeted offers that aren’t available to every applicant.
Today, we'll walk you through how pre-qualified offers work and how you can use tools such as CardMatch to find elevated bonuses and other special offers.
What is a pre-qualified offer?
When you receive a pre-qualified credit card offer, an issuer has reviewed your basic financial information and determined you are a good candidate for a specific credit card. Sometimes, issuers send out pre-qualified or even preapproved offers via snail mail, but you can also request pre-qualified offers using different online tools.
A pre-qualified offer differs from being approved for a credit card upon filling out an application. While issuers will typically look at an overview of your creditworthiness, they don’t pull your full credit report when you go through a pre-qualification process.
Instead, a pre-qualified offer is simply meant to indicate that you are a strong candidate for approval if you were to apply officially. To open a new line of credit, you will have to actually go through an official application process.
In other words, just because you were given a pre-qualified offer doesn’t automatically mean you’re guaranteed approval for a specific card.
width="1600px
SHUTTERSTOCK
There are multiple ways for you to get a pre-qualified credit card offer. As annoying as mail offers can be when they crowd your mailbox, don’t be too quick to shred them all. You can get great personalized offers with elevated bonuses, extended low-interest introductory periods and more.
Many issuers also have a pre-qualification tool on their website, including Capital One.
These tools can help those with midrange credit scores determine which cards they are most likely to be approved for without having to submit applications that could temporarily ding their credit score.
Using CardMatch to find pre-qualified offers
One of the best resources for pre-qualified offers is the CardMatch tool. This can help you filter and compare pre-qualified offers for cards like the Capital One Venture X Rewards Credit Card, The Platinum Card® from American Express and the American Express® Gold Card — and in some cases, these are even higher than the standard public offer.
Check the CardMatch tool to see which card you pre-qualify for. Keep in mind these offers are targeted and subject to change at any time.
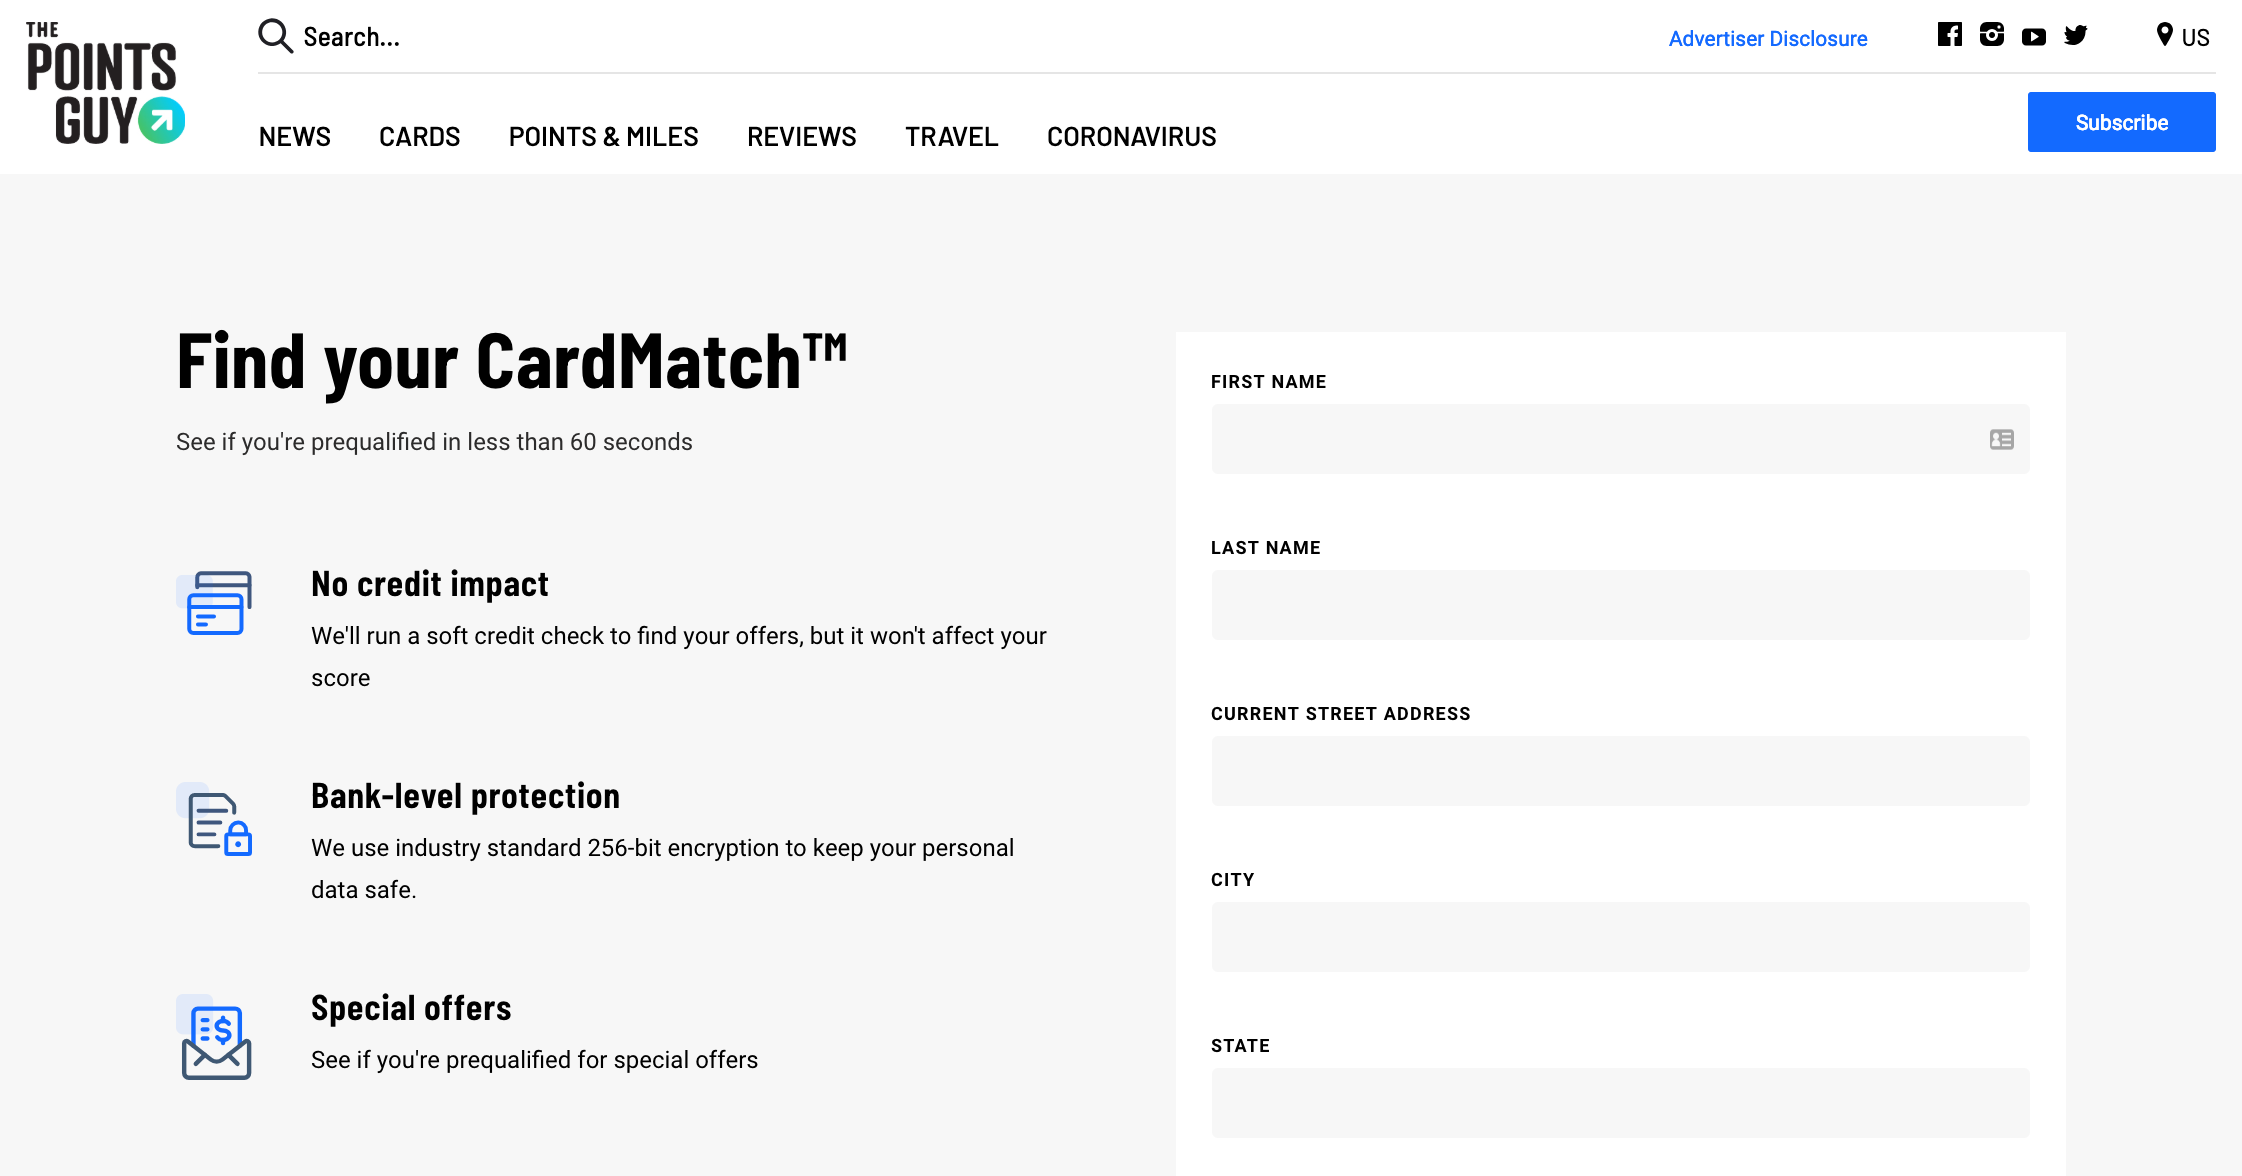
How to use the CardMatch tool
First, you fill out your information within the CardMatch tool.
THE POINTS GUY
From there, you’ll be taken to a results page with the relevant offers. Your results will, of course, be catered to you, and this all happens without a formal hard inquiry against your credit report.
We’ve seen offers as high as 175,000 Membership Rewards points for the Amex Platinum and 90,000 points for the Amex Gold after meeting minimum spending requirements.
Compare that to their publicly available welcome offers: the Amex Gold card is currently offering new applicants to earn 60,000 membership rewards points after spending $6,000 in purchases in the first six months of card membership. The Amex Platinum is currently offering a public welcome offer of 80,000 Membership Rewards Points after you spend $8,000 on purchases within the first six months of card membership.
Many issuers provide their own pre-qualification tools to help potential applicants understand whether they are likely to be approved for certain cards. Generally speaking, you may not find the best welcome offers through this method. However, with limited credit histories and less-than-stellar credit scores can utilize these tools to see which cards they may be able to get.
Currently, you can't use this tool to see if you are qualified for Capital One’s premium product — the Capital One Venture X Rewards Credit Card — but it displays your odds of approval at many other of the issuer’s cards.
The pre-qualification application is short, but you must provide your annual income, Social Security number, address and housing situation.
I was pre-qualified for the Quicksilver, Savor and Platinum cards. As an aside, I am currently a cardholder of the Venture Rewards card.
When I went through the process, I was pre-qualified for the Discover it Miles and the Discover it Cash Back cards. I’ve never owned a Discover card, potentially explaining why (and how) I qualified for these “top” Discover cards.
The information for the Discover it Miles and the Discover it Cash Back has been collected independently by The Points Guy. The card details on this page have not been reviewed or provided by the card issuer.
Credit One Bank offers several credit card options. However, this issuer certainly isn’t anywhere near the level of Chase or Amex in terms of benefits offered or potential rewards earned.
I actually went through this process and was only pre-qualified to apply for the Credit One Bank® Platinum Visa® for Rebuilding Credit. This could be because I recently opened another credit card within the past few months.
Note that Credit One Bank lists its full credit card lineup as potential options for pre-qualification (unlike Capital One, which only checks pre-qualification for select cards).
The information for the Credit One Bank Platinum Visa for Rebuilding credit card has been collected independently by The Points Guy. The card details on this page have not been reviewed or provided by the card issuer.
Does a pre-qualified offer cause a hard pull on my credit report?
A pre-qualified offer is based on a soft pull on your credit report. Going through the CardMatch tool or an issuer’s pre-qualification tool to check for targeted offers will not affect your credit score, nor will it appear as a hard pull on your credit report. This is because the issuer only receives a summary of your credit score and accompanying report.
While the information gathered at this stage can give a bank a solid picture of whether you would be approved based on certain criteria, your full report isn’t pulled.
Pre-qualified offers aren’t the same as official applications. If you decide to apply for a new line of credit, that will result in a hard inquiry on your credit report, regardless of whether you went through the pre-qualification process. And receiving a pre-qualified offer doesn’t guarantee you’ll be approved for a new account.
What's the difference between pre-qualified and preapproved?
Though some issuers use these terms interchangeably, there is a distinction between pre-qualified and preapproved offers.
A pre-qualified offer is based on a soft pull done on your credit report where you’ve met certain criteria that may make you eligible for a certain card or offer. Generally, a pre-qualification offer results from a consumer submitting a pre-qualification application (separate from an official credit application).
On the other hand, a preapproved offer is typically a prescreened offer that is targeted to you. When you accept a preapproval offer and apply, the issuer must honor the offer it sent you should you be approved for the card.
These are more common via direct mail, either through email or snail mail. Issuers with a pre-qualification portal will generally have a section where you can input an ID or invitation number from a mail-in offer to identify your targeted offer within the system.
CNYTHZL/GETTY
Neither preapproved nor pre-qualified offers will hurt your credit score because they result from a soft pull on your credit report.
However, if you decide to go forward with an application after either of these types of offers, it will result in a hard inquiry once you officially apply and give the credit issuer permission to pull your full report.
Neither a preapproved nor a pre-qualified offer counts as an official approval for a card. While it might mean that your credit profile is more likely to be approved, there is no guarantee.
There is a possibility that you could still be denied a credit card for a host of reasons. The only way to find out if you are officially approved for a credit card is to apply formally.
Similarly, just because you aren’t pre-qualified for an offer doesn’t mean you wouldn’t be approved for a certain card if you formally applied.
Whether you’re looking for the best-targeted offers or simply want a better idea of which cards you are likely to be approved for, there is a lot of value in searching for pre-qualified offers. Sometimes, like with the Amex Platinum offer through CardMatch, you can even find lucrative sign-up bonuses or welcome offers that you otherwise would miss out on.
Check the CardMatch tool to see which cards you pre-qualify for. Keep in mind these offers are subject to change at any time.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.