The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
News
Here’s why I buy an annual travel insurance policy, even though my credit cards offer travel protections
Ryan is a former TPG credit cards writer who has been around points and miles for several years and has published content at Miles to Memories, AwardWallet and The Points Guy. His wife joins him on many of his trips, and they enjoy snowboarding, diving, and seeing animals in the wild. When not traveling, Ryan is probably answering questions from his family about how he travels so much and whether this points & miles stuff is illegal.
October 2, 2024 • 10 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
Many travel-focused credit cards offer trip protections such as trip delay reimbursement, lost luggage insurance and limited emergency medical evacuation coverage.
Despite these protections, there are significant gaps—such as exclusions for preexisting conditions, adventure activities and some medical emergencies—that may not be covered by credit card insurance.
Annual travel insurance policies can provide broader coverage, including for medical issues, adventure sports and re-depositing points or miles lost from canceled trips.
Opting for an annual policy can also simplify coverage, as it applies regardless of which payment method is used for travel bookings.
What to consider
Credit card protections typically require you to pay for the trip with the specific card to activate benefits, which can be difficult to track if you use multiple cards.
Many credit card policies exclude coverage for illness, hospitalization, adventure sports and preexisting conditions, and do not reimburse points or miles lost due to cancellations.
Annual travel insurance may be more cost-effective than purchasing individual policies for each trip, especially for frequent travelers or those engaging in higher-risk activities.
What you'll miss from the article
A detailed comparison of what credit card travel protections do and do not cover, and real-world scenarios where annual travel insurance offers crucial advantages.
Generated by AI with support from our editorial team.
Update: Some offers mentioned below are no longer available. View the current offers here.
Chances are you have a credit card that offers some type of travel insurance or trip protection. This could be for benefits like trip delay reimbursement or lost luggage insurance. With these protections, purchasing a travel insurance policy may seem unnecessary.
When I first got into the world of credit card points and miles, I thought, “I’m never buying travel insurance again because my credit cards cover it!”
So why do I buy an annual travel insurance policy for myself and my wife? Isn’t that an unnecessary expense? Here’s why I buy an annual travel insurance plan, even though my credit cards offer numerous trip protections.
What is travel insurance?
Before we understand which credit cards offer travel insurance benefits and why I carry an annual policy, let’s define travel insurance.
Travel insurance is a catch-all term for a policy that covers you against financial losses during travel. This could include things such as lost property, lost money from accidents or delays, unforeseen medical bills and even serious injuries — or accidental death.
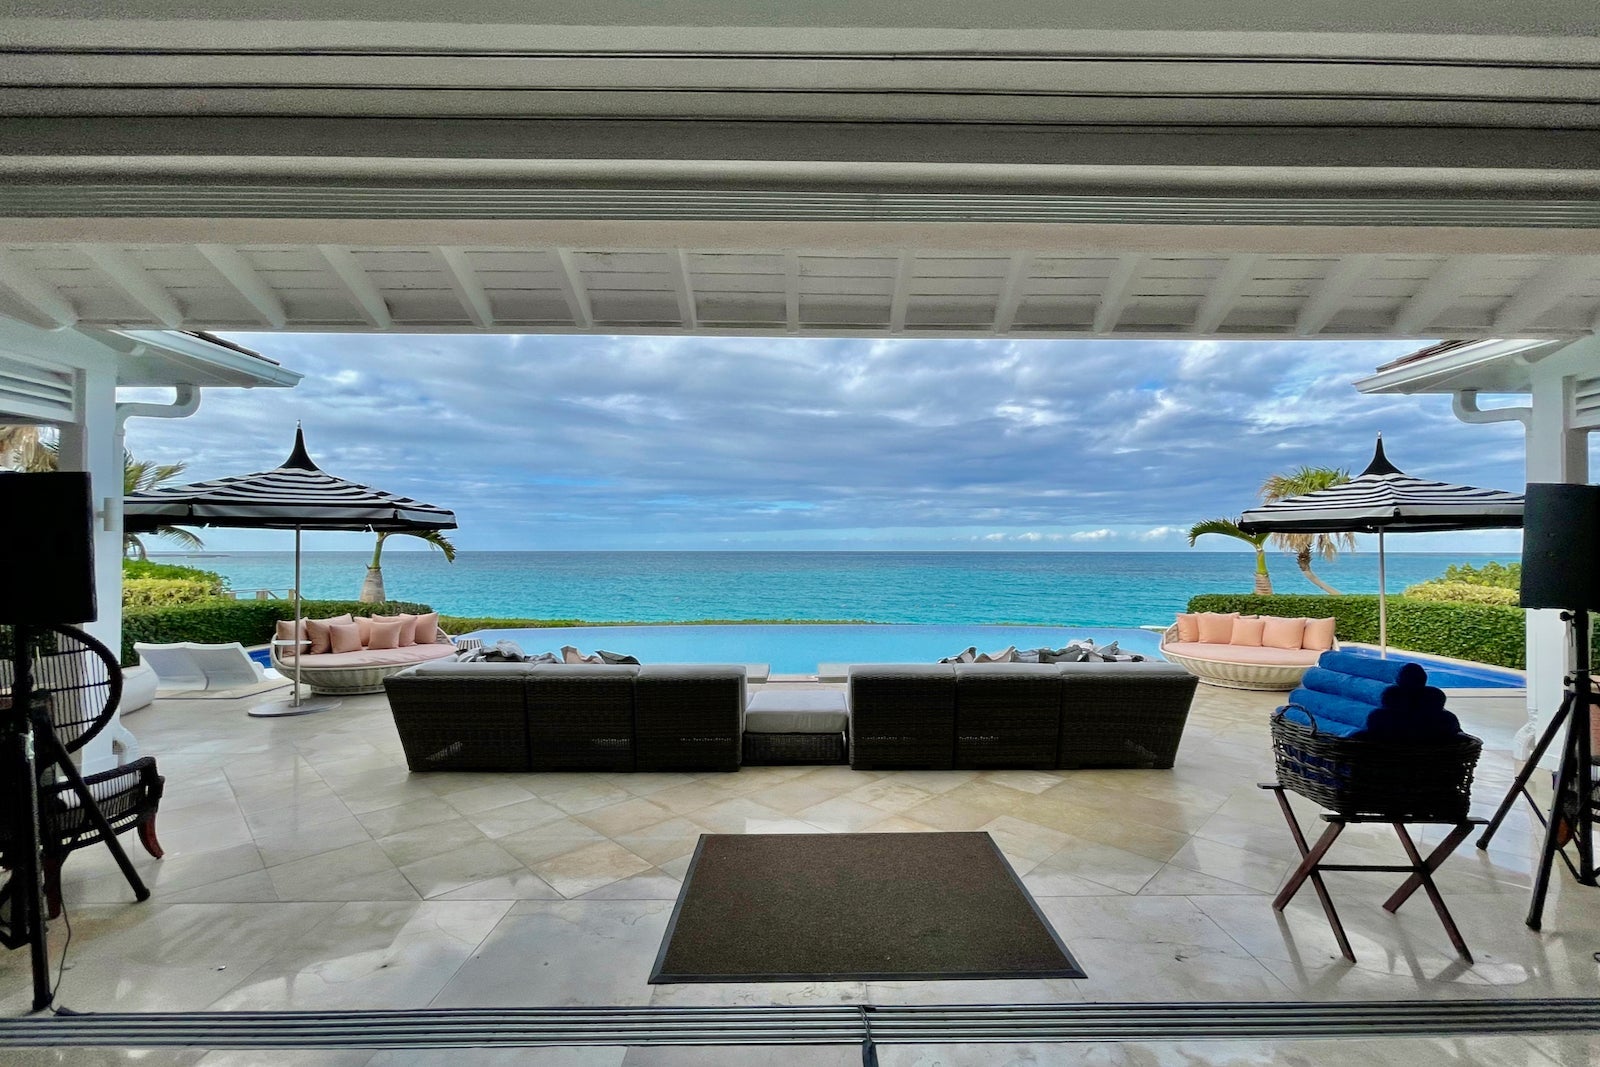
The Ocean Club, a Four Seasons Resort in Nassau, Bahamas. ZACH GRIFF/THE POINTS GUY
Policies vary in what they cover, when the coverage becomes active, which events trigger your policy’s coverage and other intricacies. There’s also an add-on “cancel for any reason” insurance on some policies.
An overview of travel protections on popular credit cards
Before discussing why I carry an annual travel insurance policy, let’s look at some popular travel credit cards to see what protections they offer. We can then use this to see what they don’t cover, as well as to understand when coverage is and isn’t in effect.
Here are four popular travel credit cards and the coverage they provide for travel mishaps:
Capital One Venture X Rewards Credit Card
Chase Sapphire Preferred® Card
Chase Sapphire Reserve®
The Platinum Card® from American Express
Annual fee
$395
$95 (see rates and fees)
$795 (see rates and fees)
$895 (see rates and fees)
Trip cancellation reimbursement for lost money
Up to $2,000 per person for you and immediate family members for prepaid, nonrefundable tickets
Up to $10,000 per person and $20,000 per trip for your pre-paid, nonrefundable travel
Up to $10,000 per person and $20,000 per trip for your pre-paid, nonrefundable travel
Up to a maximum of $10,000 per covered trip and a maximum of $20,000 per eligible card in a 12-month period*
Trip delay coverage for extra expenses
Up to $500 per person for reasonable expenses like hotel rooms, food, toiletries or clothes when your flight is delayed overnight or by six hours or more
Up to $500 per person for non-reimbursed expenses like meals and lodging when your flight is delayed overnight or by 12 hours or more
Up to $500 per person for non-reimbursed expenses like meals and lodging when your flight is delayed overnight or by six hours or more
Up to $500 per covered trip that is delayed for more than six hours, capped at two claims per eligible card per 12 consecutive months*
Emergency medical evacuation
Can facilitate, but you will still pay for it
Can facilitate, but you will still pay for it
Up to $100,000 in emergency evacuation coverage, but it must be coordinated by the benefits administrator to be covered
If approved and coordinated by the Premium Global Assist Hotline, assistance may be provided at no cost to you**
Lost or delayed luggage
Lost luggage covered; delayed luggage not covered
Both are included
Both are included
Lost luggage covered; delayed luggage not covered***
Emergency medical / dental coverage
Not included
Not included
Up to $2,500, subject to a $50 deductible. Up to $75 per day for up to 5 days for a hotel room after a hospital stay
Not included
Accidental death / dismemberment reimbursement
Up to $1 million
Up to $500,000
Up to $1 million
None
Requires paying for full trip on this card to activate benefits?
*Eligibility and benefit level varies by card. Terms, conditions and limitations apply. Visit americanexpress.com/benefitsguide for details. Policies are underwritten by New Hampshire Insurance Company, an AIG Company.
**Eligibility and benefit level varies by card. Terms, conditions and limitations apply. Visit americanexpress.com/benefitsguide for details. Cardmembers are
responsible for the costs charged by third-party service providers.
***Eligibility and benefit level varies by card. Terms, conditions and limitations apply. Visit americanexpress.com/benefitsguide for details. Policies are underwritten by AMEX Assurance Company.
From the chart above, the list of travel protections and trip insurance provided by credit cards appears quite robust at first. Unfortunately, there are parts of your upcoming trip that may not be covered by your credit card’s travel protections — which is why I carry an annual travel insurance policy. Let’s look at what isn’t covered by your credit card travel insurance because some of this information may surprise you.
Firstly, your credit card protections won’t apply if you don’t pay for your trip with that particular credit card. Simply having the Chase Sapphire Reserve in your wallet won’t help you during a delay on your next vacation unless you pay for at least part of the trip with that card. While that sounds easy enough, those of us who hold many credit cards and constantly open new cards to earn sign-up bonuses often put our expenses on those newer cards instead of the card with the best protections.
Moreover, if you have many credit cards, it could be quite difficult to remember exactly which expenses you paid for with which card when you’re in an urgent situation. However, you’ll need to know that information to understand which benefits are available to you at that critical moment.
Additionally, many credit cards do not cover illness and hospitalization. If you become ill and need to spend a few nights in a hospital — such as when I got malaria in Tanzania in 2021 and then needed another week of recuperation at a hotel before I was able to fly home — credit card travel insurance could leave you footing the bill.
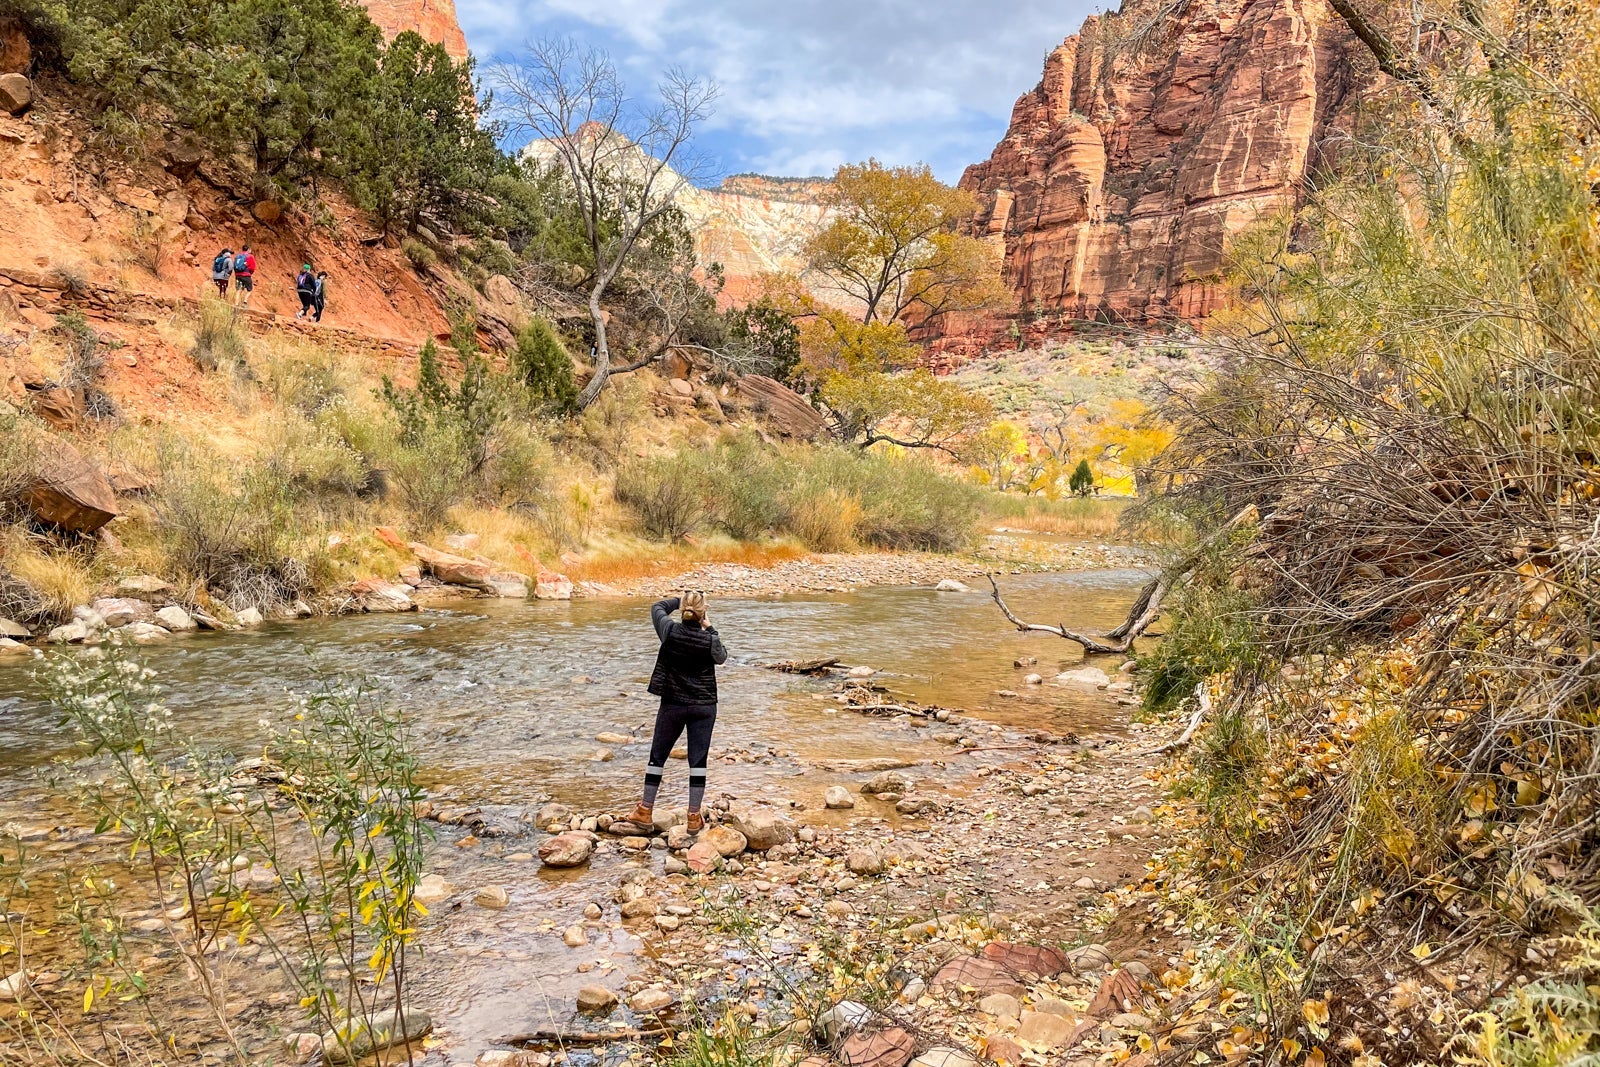
Zion National Park. SUMMER HULL/THE POINTS GUY
Speaking of bills you don’t want to hold, consider that emergency medical evacuation may not be covered by your credit card. If you’re hiking in a remote area and have a bad fall, the average cost of medical evacuation by helicopter is over $30,000, according to the American Journal of Managed Care. Two cards may cover this: the Chase Sapphire Reserve and Amex Platinum. However, it must be coordinated by your benefits administrator — not by you calling the service provider yourself — or you will be stuck with the bill.
Lastly, there are multiple exclusions for what’s not covered by most credit card travel insurance policies:
Preexisting conditions that lead to problems during your trip.
Any injuries related to adventure activities such as scuba diving, skiing or snowboarding during your trip.
It’s also worth pointing out that none of these policies will reimburse the points and miles you lose along the way from canceled trips. If you want to splurge and cover the fees for re-depositing your points and miles after canceled trips, you can do that with some annual travel insurance plans. Allianz features this on its All Trips Executive plan. You won’t find this option with credit card travel insurance. With credit card protection, only your out-of-pocket cash losses are covered.
I currently have more than 20 credit cards. I’m of the mentality that you should always be opening a new credit card and working on the sign-up bonus. This means the trips I’m planning for this year probably aren’t paid for with my best credit card for flights but rather with a new credit card, helping me earn bonus points from a welcome offer.
The advantage to this is earning lots of extra points and miles while not worrying about what credit card I’m using for my spending. The downside is that my credit card’s travel protections likely aren’t in effect. When buying an annual travel insurance policy, I don’t need to worry about which credit cards I’m using when making reservations for an upcoming trip.
I also take a yearly snowboarding and scuba diving trip with my wife. Neither of these activities would be covered by credit card travel insurance. One year, I spent three nights in a hospital in Arusha, Tanzania. Evacuation coverage is important for those “just-in-case” situations.
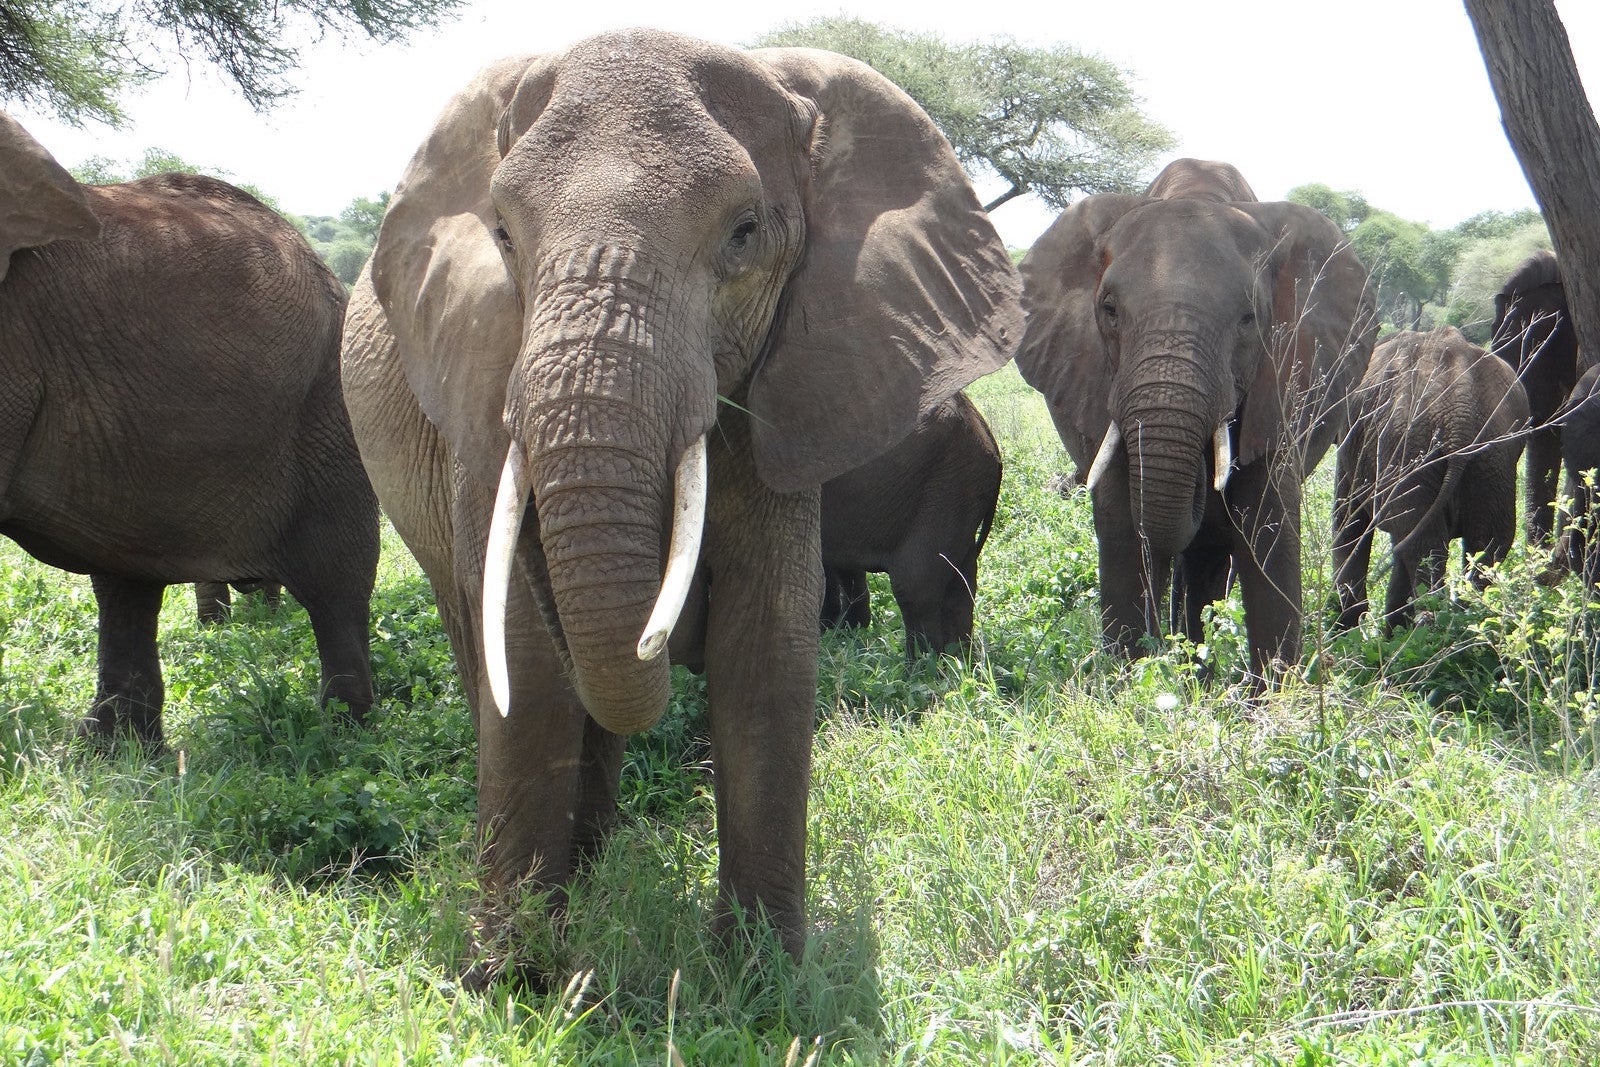
Elephants in Tanzania. RYAN SMITH/THE POINTS GUY
My annual travel insurance policy met this requirement; credit card insurance wouldn’t cover it though, so you would need to purchase an additional health plan if your standard health insurance policy didn’t meet the requirements.
For me, purchasing an annual travel insurance policy makes sense. That’s after considering what’s covered, what isn’t covered and the fact I often don’t use the best card with the best coverage to pay for my trips (because I’m putting my spending on a new credit card for a new sign-up bonus). Plus, carrying an annual policy is cheaper than buying per-trip policies every time I leave home.
No two people’s lives are the same, and neither are their travel needs. Even though we have numerous credit cards that offer various travel protections, it makes sense for me and my wife to buy an annual travel insurance policy.
Consider the limitations on coverage that your credit card offers and how the coverage goes into effect before getting a separate travel insurance policy. Rather than purchasing a new plan for each trip, you can save money by taking out an annual plan each year.
For rates and fees of the Amex Platinum card, click here.
For Capital One products listed on this page, some of the benefits may be provided by Visa® or Mastercard® and may vary by product. See the respective Guide to Benefits for details, as terms and exclusions apply.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.