The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Katie Genter is a digital nomad who has traveled full time since June 2017. She writes and edits stories about points and miles, and loyalty programs, often letting her personal experiences color these stories.
May 27, 2020 • 23 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
HSBC offers six credit cards in the U.S., but most require an existing banking relationship to apply.
Two cards are available to the general public, focusing on introductory APR and straightforward cash-back rewards.
Other cards target HSBC clients, with enhanced benefits for dining, travel and premium travel perks.
All cards include standard features such as no foreign transaction fees, rental car coverage and access to Mastercard travel and shopping programs.
What to consider
Eligibility for most cards depends on having an HSBC Advance or Premier account, which may involve maintaining certain deposit or direct deposit levels.
Some offers and benefits are not available to Wisconsin residents, and certain introductory offers have expired or changed.
Balance transfer fees and redemption values for rewards points vary, so comparing options is important.
What you'll miss from the article
A detailed comparison of each card's benefits, eligibility requirements and which audiences are best suited for each option.
Generated by AI with support from our editorial team.
Update: Some offers mentioned below are no longer available. View the current offers here.
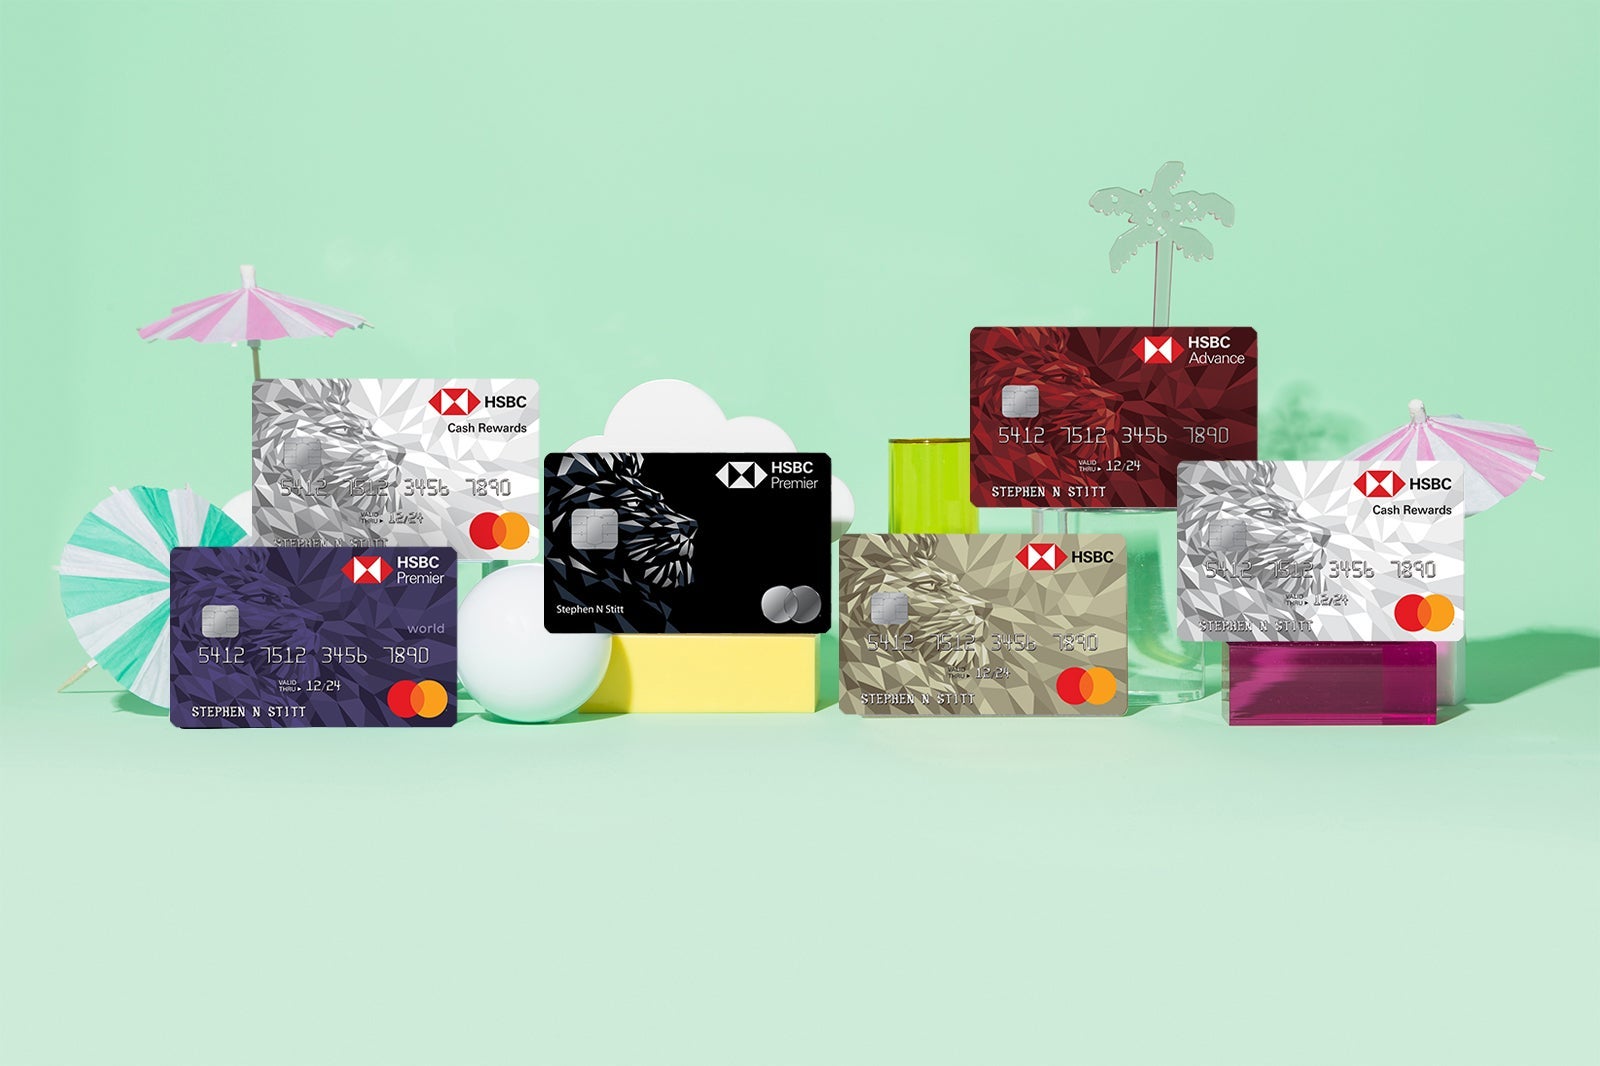
HSBC is one of the world’s largest banking and financial services institutions. Yet many U.S. consumers don’t think of the company when shopping for a new rewards credit card. HSBC currently only offers six credit cards to U.S. consumers, so let’s take a detailed look at these six cards and answer some common questions about them.
Students who have a consumer deposit relationship with HSBC
HSBC Advance Mastercard® credit card
Dining and entertainment
2x points on dining and select entertainment
1x on all other purchases
None for Advance and Premier clients, otherwise $45
HSBC Advance or Premier relationship
HSBC Premier World Mastercard® credit card
Travel
2x points on travel
1x on all other purchases
None for Premier clients, otherwise $95
HSBC Premier relationship
HSBC Premier World Elite Mastercard® credit card
Premium travel rewards
3x points on travel
2x on dining
1x on all other purchases
$395
HSBC Premier relationship
More details on the best HSBC credit cards
Let's take a look at the details of each of these HSBC credit cards and offers, including rewards rates, benefits and annual fees.
HSBC Gold Mastercard credit card: Best for 0% introductory APR
(Photo by John Gribben/The Points Guy)
Why this is the best for 0% introductory APR: This card offers 0% introductory APR on purchases and balance transfers for the first 18 months after account opening.
Introductory offer: 0% introductory APR on purchases and balance transfers for the first 18 months from account opening. Balance transfers must be posted within the first 60 days following account opening. Once the introductory period is over, a variable APR of 12.99%, 16.99% or 22.99% will apply. A balance transfer fee of either $10 or 4%, whichever is greater, applies on each balance transfer.
Is this card worth it? Whether you’re looking to delay payment of a large purchase or you’re working to pay off debt, the HSBC Gold Mastercard may be able to help with its 0% introductory APR on purchases and balance transfers for the first 18 months. However, some other cards offer lower balance transfer fees, so it may be worth considering other options.
HSBC Cash Rewards Mastercard credit card: Best for cash-back rewards
(Photo by John Gribben/The Points Guy)
Why this is the best for cash-back rewards: This card provides 3% cash back on up to $10,000 in purchases made within your first 12 months and 1.5% cash back after that.
Introductory offer: Earn 3% cash back on up to $10,000 in purchases within your first 12 months from account opening. Plus, get 0% introductory APR on purchases and balance transfers for the first 12 months from account opening. Balance transfers must be posted within the first 60 days following account opening. After that, a variable APR of 12.99%, 16.99% or 22.99% will apply. A balance transfer fee of either $10 or 4%, whichever is greater, applies on each balance transfer.
Rewards rate: Earn 1.5% cash back on all purchases (after the 3% introductory period ends)
Top benefits and perks:
MasterRental coverage, which provides protection for physical damage and theft to most rental vehicles
Is this card worth it? The introductory 3% offer provides solid cash-back earning during your first year, and 1.5% cash back long-term is also strong. If you’re looking for a simple no annual fee card that earns flat-rate cash back, this is a solid choice. However, you can do slightly better with some other cards such as the Citi® Double Cash Card that provides up to 2% cash back on everything as 1% when you buy and 1% as you pay.
HSBC Cash Rewards Mastercard credit card Student Account: Best for cash-back rewards for students
(Photo by John Gribben/The Points Guy)
Why this is the best for cash-back rewards for students: Students can be approved without any credit history. Plus, the card offers 1.5% cash back on all purchases.
Introductory offer: None
Rewards rate: Earn 1.5% cash back on all purchases
Is this card worth it? The HSBC Cash Rewards Mastercard credit card Student Account can be a good option for students who have an existing HSBC deposit account. Eligible students may be able to open this unsecured credit card without credit history and earn 1.5% cash back while building their credit.
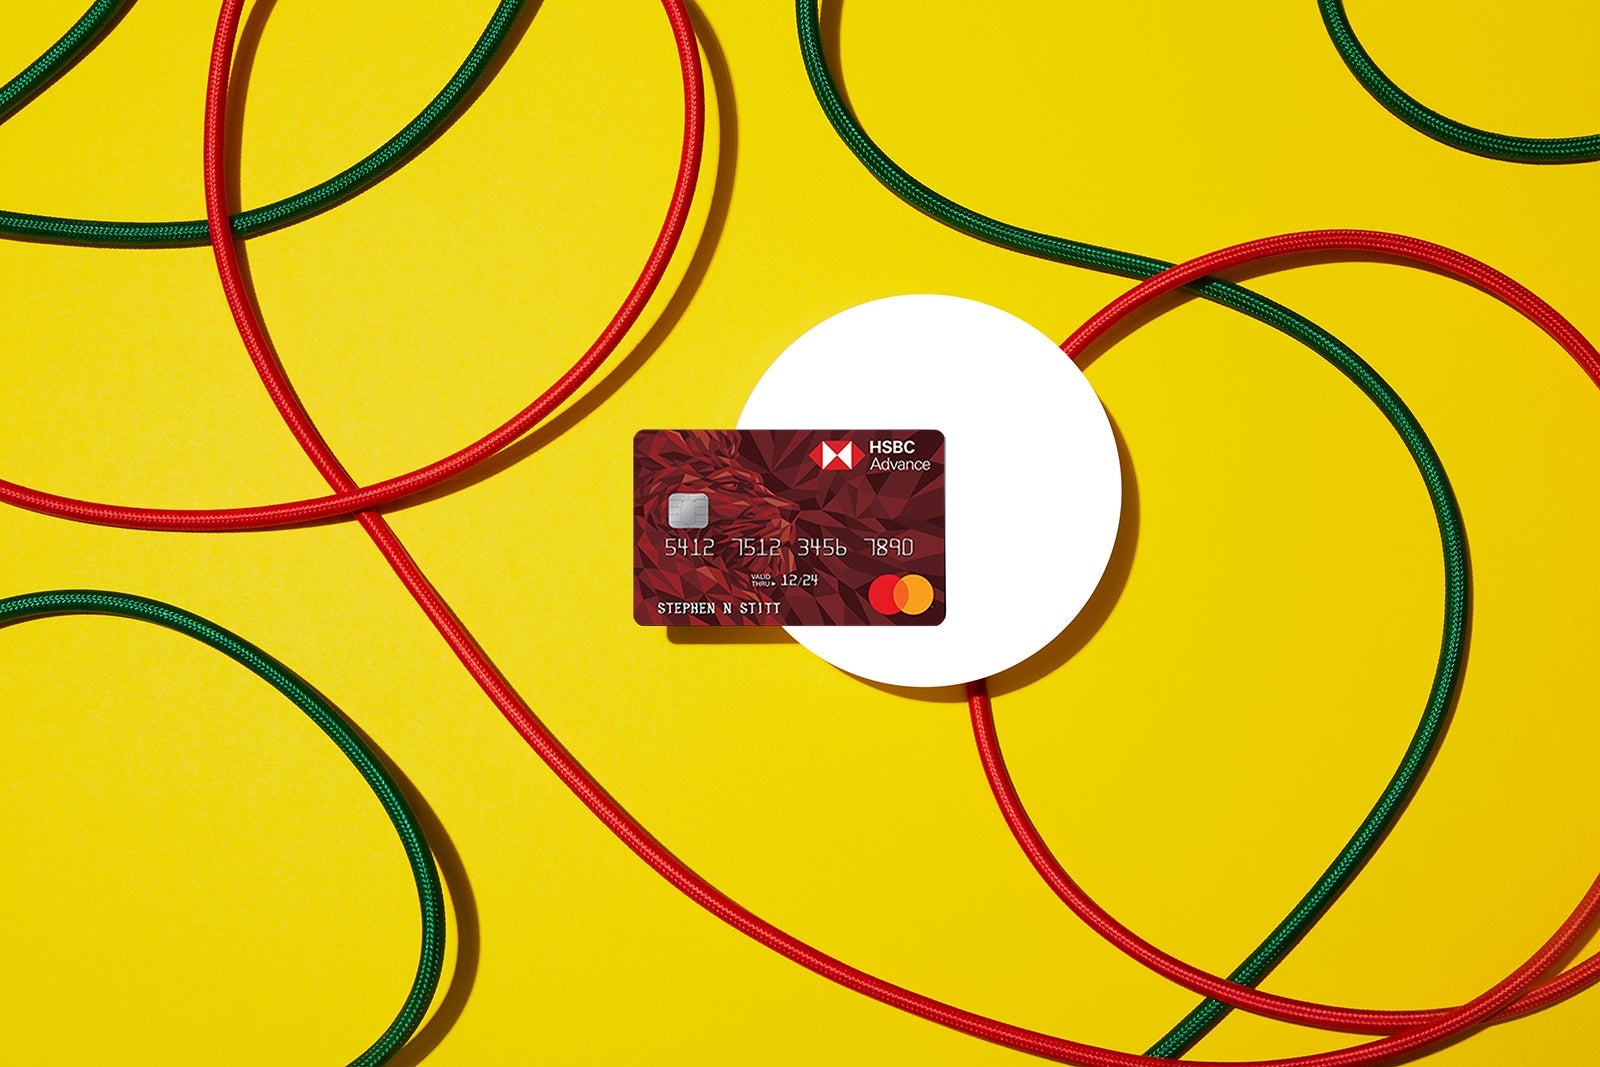
HSBC Advance Mastercard credit card: Best for dining and entertainment
(Photo by John Gribben/The Points Guy)
Why this is the best for dining and entertainment: This card earns 3x points on dining and select entertainment during your first 12 months and then 2x points once the introductory period is complete. You must have a qualifying HSBC Advance or Premier checking account relationship to be eligible for this card.
Introductory offer: Earn an introductory 3x points on dining and select entertainment purchases plus 2x points on all other purchases in the first 12 months from account opening, up to the first $25,000 in purchases. Plus, get 0% introductory APR on credit card purchases and balance transfers for the first 12 months from account opening.
Balance transfers must be posted within the first 60 days following account opening. After that, a variable APR of 14.99% or 18.99% will apply. A balance transfer fee of either $10 or 4%, whichever is greater, applies on each balance transfer.
Rewards rate: Earn 2x Rewards Program Points on dining and select entertainment purchases after the intro period. Plus, earn 1x on all other purchases after the intro period.
Top benefits and perks:
MasterRental coverage, which provides protection for physical damage and theft to most rental vehicles
10% off when booking luxury hotel stays through onefinestay
$5 off on Postmates orders of $25 or more for delivery of food, drinks and groceries (not including taxes, delivery fees, and tips)
Annual fee: $0 during the first year of account opening, then $0 for cardholders who have a qualifying U.S. HSBC Advance or Premier checking account relationship and $45 for cardholders who no longer have a qualifying checking account relationship
Is this card worth it? If you are eligible for this card with a $0 annual fee, it can be a good way to earn bonus points on dining and entertainment. But, it’s unclear from publicly available materials what type of redemption value you’ll get from Rewards Program Points. So, it may be better to opt for a more straightforward rewards credit card that earns bonus rewards on dining and/or entertainment such as the Capital One Savor Cash Rewards Credit Card or the Capital One SavorOne Cash Rewards Credit Card.
The information for the Capital One Savor card has been collected independently by The Points Guy. The card details on this page have not been reviewed or provided by the card issuer.
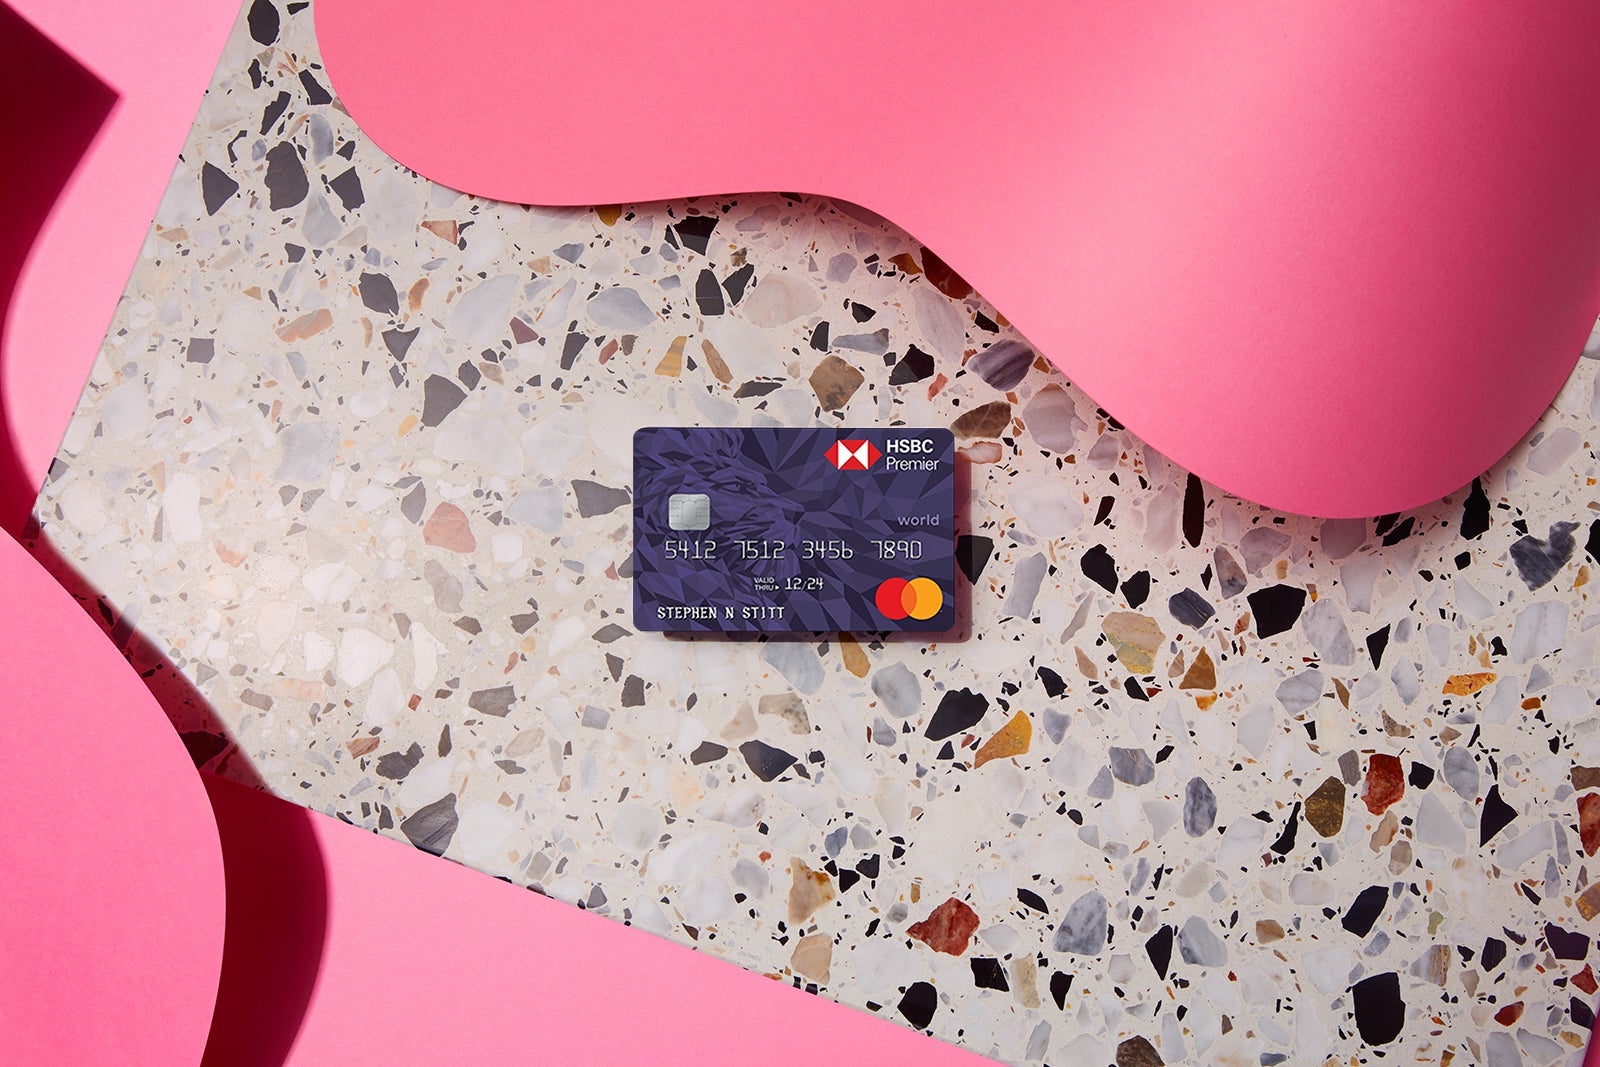
HSBC Premier World Mastercard credit card: Best for travel
(Photo by John Gribben/The Points Guy)
Why this is the best for travel: This card offers 2x points on travel purchases as well as various travel-related perks. You must have a qualifying HSBC Premier checking account to be eligible for this card.
Introductory offer: Earn 35,000 Rewards Program Bonus Points -- worth at least $400 in air travel -- after spending $3,000 in the first three months from account opening.
Rewards rate: Earn 2x Rewards Program Points on travel purchases and 1x Points on all other purchases.
Top benefits and perks:
Enjoy complimentary unlimited premium Wi-Fi at over a million secure hotspots worldwide with Boingo. Get simultaneous access for up to four devices.
$5 off on Postmates orders of $25 or more for delivery of food, drinks and groceries (not including taxes, delivery fees, and tips)
10% discount when you book your hotel or vacation home stay through Expedia, Agoda or onefinestay
Trip cancelation insurance that may reimburse you for your prepaid, non-refundable expenses in case you have to cancel your trip for a covered reason
Hotel and motel burglary insurance that may reimburse you up to $1,500 per claim for personal property stolen or damaged from your hotel or motel room as a result of burglary by forcible entry
Lost luggage insurance that may reimburse you up to $1,500 per claim for checked or carry-on luggage that is lost or damaged while traveling on a common carrier
Baggage delay insurance that may reimburse you up to $250 per claim for the cost of essential items such as clothing and toiletries if your luggage is delayed in getting to your scheduled destination
Purchase assurance that may reimburse you when an item you bought with your card is damaged or stolen within 90 days of purchase
Annual fee: $0 during the first year of account opening, then $0 for cardholders who have a qualifying U.S. HSBC Premier checking account relationship and $95 for cardholders who no longer have a qualifying HSBC relationship.
Is this card worth it? If you have a qualifying U.S. Premier checking account with HSBC, you might as well open the HSBC Premier World Mastercard credit card for its travel-related benefits and shopping benefits. But, if you aren’t already an eligible HSBC customer, you may want to consider other travel credit cards with stronger earning rates and additional perks such as a Global Entry application fee credit.
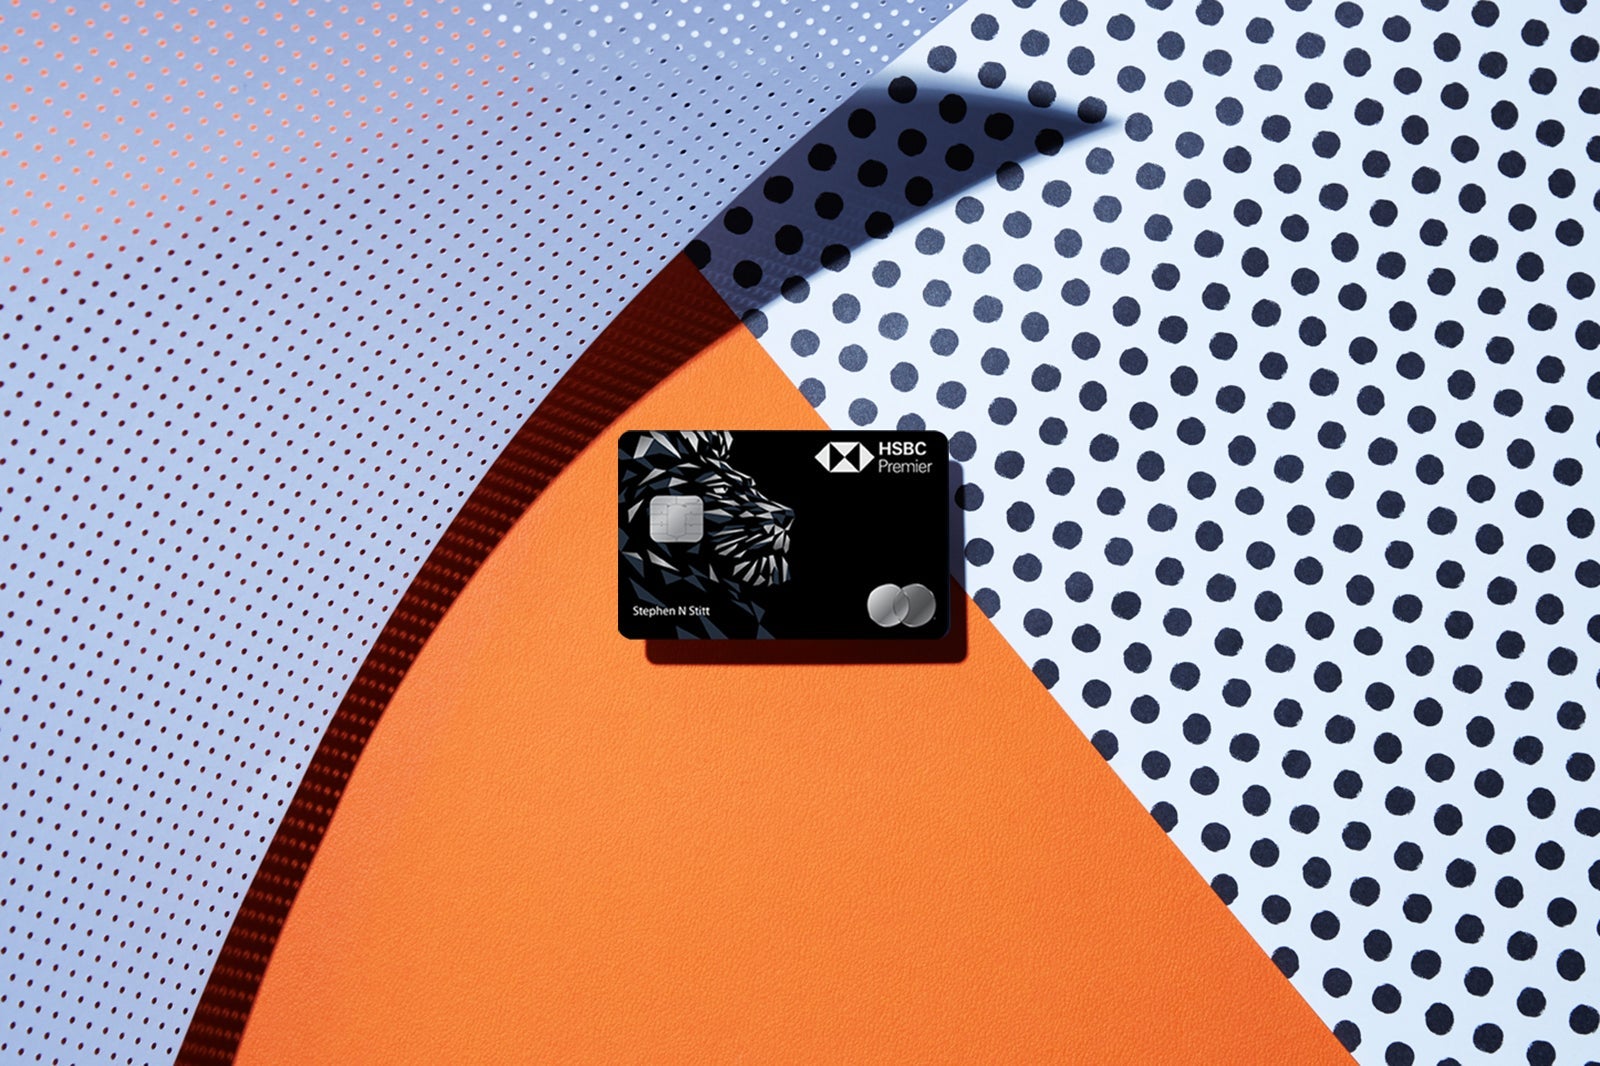
HSBC Premier World Elite Mastercard credit card: Best for premium travel rewards
(Photo by John Gribben/The Points Guy)
Why this is the best for premium travel rewards: This card provides 3x earning on travel purchases, 2x earning on dining purchases and various travel and shopping benefits. You must have a qualifying HSBC Premier checking account to be eligible for this card.
Introductory offer: Earn 50,000 Rewards Program Bonus Points -- worth $750 in airfare when booked online through HSBC Rewards -- after spending $4,000 in the first three months of account opening.
Rewards rate: Earn 3x Rewards Program Points on travel purchases, 2x on dining purchases and 1x on all other purchases.
Top benefits and perks:
Receive up to $100 in statement credits annually as reimbursement for air travel purchases charged to your card
Trip cancelation insurance that may reimburse you for your prepaid, non-refundable expenses in case you have to cancel your trip for a covered reason
Hotel and motel burglary insurance that may reimburse you up to $1,500 per claim for personal property stolen or damaged from your hotel or motel room as a result of burglary by forcible entry
Lost luggage insurance that may reimburse you up to $1,500 per claim for checked or carry-on luggage that is lost or damaged while traveling on a common carrier
Baggage delay insurance that may reimburse you up to $250 per claim for the cost of essential items such as clothing and toiletries if your luggage is delayed in getting to your scheduled destination
Price protection that may reimburse you when you purchase an item with your card and then see a printed advertisement or non-auction Internet advertisement for the same product at a lower price within 60 days from the date of purchase
Extended warranty that may double the original manufacturer warranty up to a maximum of 24 months when you purchase an eligible item with your card
Purchase assurance that may reimburse you when an item you bought with your covered card is damaged or stolen within 90 days of purchase
Is this card worth it? This card offers some perks that aren’t commonly found on credit cards anymore such as Boingo Wi-Fi access and price protection. Plus, the card offers 3x earning on travel purchases as well as 2x earning on dining purchases and allows redemption for 1.5 cents per point when you book through HSBC Rewards. However, you’ll need to have a qualifying HSBC’s Premium checking account to get this card.
HSBC currently only offers six credit cards in the United States. And, only two of these cards are available to consumers without an existing HSBC relationship. So, in this guide we decided to analyze all six of the currently available HSBC credit cards and determine for whom each card might be best.
Benefits available on all HSBC credit cards
(Photo by Orli Friedman/The Points Guy)
All of the currently available HSBC credit cards offer some basic benefits. In particular, you’ll find the following perks available on all of the HSBC cards:
The HSBC Premier World Mastercard and HSBC Premier World Elite Mastercard require you to have an HSBC Premier relationship to apply, while the HSBC Advance Mastercard requires you to have an HSBC Advance relationship to apply. Here’s what you need to know about both of these HSBC relationships.
HSBC Advance
With HSBC Advance, you won’t need to pay any HSBC fees when using a third-party ATM and you can get up to four third-party ATM surcharge fees reimbursed per month. You’ll also get access to preferred saving rates.
However, if you don’t maintain a combined balance of at least $5,000 in your HSBC deposit and investment accounts, have a recurring direct deposit from a third party to an HSBC Advance checking account once per calendar month or have an HSBC U.S. residential mortgage loan, you’ll need to pay a monthly maintenance fee of $25.
With HSBC Premier, you won’t have fees on everyday banking transactions, no HSBC ATM fees worldwide and unlimited third party ATM rebates within the U.S. You can extend your Premier status to up to four family members and you have automatic Premier status in all countries where you bank with HSBC affiliates.
However, to become an HSBC Premier client you must have at least $75,000 in total deposits and/or investments, have at least $5,000 in total direct deposits per month or maintain a U.S. residential mortgage loan with an original loan amount of at least $500,000. A monthly maintenance fee of $50 will be incurred if one of these requirements is not maintained.
Frequently asked questions about HSBC credit cards
What is the best HSBC credit card?
The best HSBC credit card is the HSBC Premier World Elite Mastercard credit card, due to its travel and shopping perks. But, this card requires you to have an HSBC Premier relationship, which may be difficult for many consumers. The best card for you depends on what factors you’re looking for in a card.
If you have an HSBC Premier relationship and will take advantage of the HSBC Premier World Elite Mastercard’s travel and shopping benefits, then the card can certainly be worth it. But, if you don’t already have an HSBC Premier relationship, you may want to consider other premium travel rewards cards such as the Chase Sapphire Reserve or the UBS Visa Infinite Credit Card.
The information for the UBS Visa Infinite card has been collected independently by The Points Guy. The card details on this page have not been reviewed or provided by the card issuer.
Are HSBC credit cards easy to get?
The HSBC Gold Mastercard and HSBC Cash Rewards Mastercard both allow potential applicants to check whether they’re prequalified with just a soft credit pull. So, if you’re worried about whether you’ll be approved for an HSBC credit card, you may want to check whether you’re prequalified for one of these cards.
Alternatively if you’re a student you may want to consider the HSBC Cash Rewards Mastercard credit card Student Account since this card doesn’t require any credit history. However, note that you need to have a consumer deposit relationship with HSBC to qualify for this card.
Can Wisconsin residents get an HSBC credit card?
Currently, all of the HSBC credit cards have a note in their Summary of Terms that states the offer is void in Wisconsin.
Using an HSBC checking or savings account: Log-in to your HSBC account, select your credit card and click Move money
Using a non-HSBC checking or savings account: Log-in to your HSBC account, select your credit card, click My Account, select Payments and then click Make a Payment
By mail: Fill in the remittance stub and mail it along with your payment to HSBC Bank USA, N.A., PO Box 4657, Carol Stream, IL 60197-5255
By phone: Call the number on the back of your credit card
Enroll in autopay: You can enroll in EZ-Pay autopay by logging in to your HSBC account, selecting your credit card, clicking My Account, selecting Payments and then clicking Schedule EZ-Pay
HSBC offers six credit card products currently, although all but two of these products require an existing HSBC relationship. This means that most HSBC credit card products will be primarily useful to existing HSBC clients.
But, if you are looking for a no annual fee card with a 0% introductory APR offer on purchases and balance transfers, it may be worth checking whether you’re prequalified for one of the two credit cards that are open to non-HSBC consumers.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.