Katie Genter is a digital nomad who has traveled full time since June 2017. She writes and edits stories about points and miles, and loyalty programs, often letting her personal experiences color these stories.
April 14, 2021 • 14 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
Travel insurance can be purchased separately or may be provided automatically when booking travel with certain credit cards.
Built-in travel protections from select cards can cover trip delays, baggage issues, cancellations, interruptions, emergency medical needs and car rental damage.
Coverage limits, eligibility and requirements vary, with some protections only applying to trips of specific lengths or when travel is booked using the card.
Comparing card protections to standalone insurance shows differences in coverage amounts and convenience, making the best choice dependent on individual travel needs.
What to consider
Some protections require you to pay for at least part of your travel with the card and may have trip length or distance restrictions.
Filing claims through card benefit administrators can be time-consuming and may not cover all situations, especially during events like pandemics.
Certain destinations or travel circumstances may require standalone insurance for adequate or mandated coverage.
What you'll miss from the article
A detailed comparison of built-in card protections versus standalone travel insurance, including specific coverage scenarios and practical tips for deciding which option best suits your travel plans.
Generated by AI with support from our editorial team.
Update: Some offers mentioned below are no longer available. View the current offers here.
For a while, I thought it was irresponsible to travel without purchasing travel insurance. After all, I'd seen many posts in various online travel communities about instances where travel insurance saved the day. And I'd also read stories from travelers lamenting financial troubles caused by not having insurance.
However, while having a plan for if something goes wrong on the road is indeed prudent, you don't necessarily have to purchase a separate travel insurance plan in every situation. In fact, some credit cards provide automatic travel protections when you put qualifying expenses on your card. So, when my multi-trip annual insurance plan lapsed, I considered whether it made sense to purchase a new policy.
In short, it didn't.
And even as my husband and I look to restart travel once we're fully vaccinated, it still typically won't make sense for us to purchase trip insurance. In this article, I'll describe how we insure ourselves and how you may be able to do the same if you have and use the Chase Sapphire Reserve.
What travel insurance covers
(Photo by Isabelle Raphael/The Points Guy)
Travel insurance often provides the following types of coverage:
You can purchase travel insurance that provides these types of coverage. Or, you can rely on the travel insurance and protections provided by select credit cards. In this guide, I'll describe the protections provided by the Chase Sapphire Reserve. Although some other cards offer similar protections, I believe the Chase Sapphire Reserve provides the most comprehensive travel protection.
As a reminder, the Chase Sapphire Reserve offers the following trip and transit protections:
Trip delay reimbursement: Up to $500 per ticket for reasonable expenses during a delay of more than six hours or overnight. You must currently be on a trip from your residence of 365 days or less. The cardholder, cardholder's spouse or domestic partner and dependent children under 22 are covered.
Baggage delay benefit: Reimbursement of up to $100 per day for up to five days for emergency purchase of essential items when baggage is delayed or misdirected for more than six hours. The cardholder, cardholder's spouse or domestic partner and immediate family members are covered.
Lost luggage benefit: Reimbursement for repair or replacement of checked baggage and/or carry-on baggage that is lost or damaged. Up to $3,000 per covered person, but only up to $500 per person for electronics, watches and jewelry. The cardholder and immediate family members are protected.
Trip cancellation insurance: Reimbursement of up to $10,000 per covered person and up to $20,000 per covered trip when a covered loss prevents you from departing on a covered trip of 60 days or less. The cardholder and immediate family members are protected.
Trip interruption insurance: Reimbursement of up to $10,000 per covered person and up to $20,000 per covered trip when a covered trip of 60 days or less is interrupted by a covered loss. The cardholder and immediate family members are protected.
24-hour travel and emergency assistance services: Assistance and referral services for emergency services. The cardholder, cardholder's spouse or domestic partner and dependent children under 22 may use this benefit.
These benefits cover you as long as you use your Chase Sapphire Reserve to pay for at least part of your common carrier travel. But digital nomads and other long-term travelers should keep in mind the 60-day trip maximum for trip cancellation and interruption insurance as well as the 365-day trip maximum for trip delay insurance.
Suppose you use your Chase Sapphire Reserve to purchase at least part of a covered trip. In that case, the card's emergency medical and dental benefit may protect you, your spouse or domestic partner and dependent children under 18 (or under 25 if enrolled as a full-time student at an accredited university). This benefit provides up to $2,500 (subject to a $50 deductible) for medical or dental expenses not paid by your insurance as a result of emergency treatment of a sickness or accidental injury while on a covered trip.
If you have health insurance that provides coverage outside the U.S. after an "out-of-pocket maximum," then supplementing this coverage with the Chase Sapphire Reserve's emergency medical and dental benefit may provide adequate protection against catastrophic medical expenses. For example, our BlueCross BlueShield of South Carolina PPO plan provides coverage internationally as out-of-network care. We have an out-of-pocket maximum of $8,000 per person for out-of-network care, so our potential financial risk from medical issues is limited to $8,000 per person per year.
If your medical insurance won't cover you at your destination and you aren't going to purchase travel insurance, you should consider purchasing travel medical insurance. GeoBlue and IMG Global are two well-recommended companies that offer competitive travel medical insurance plans.
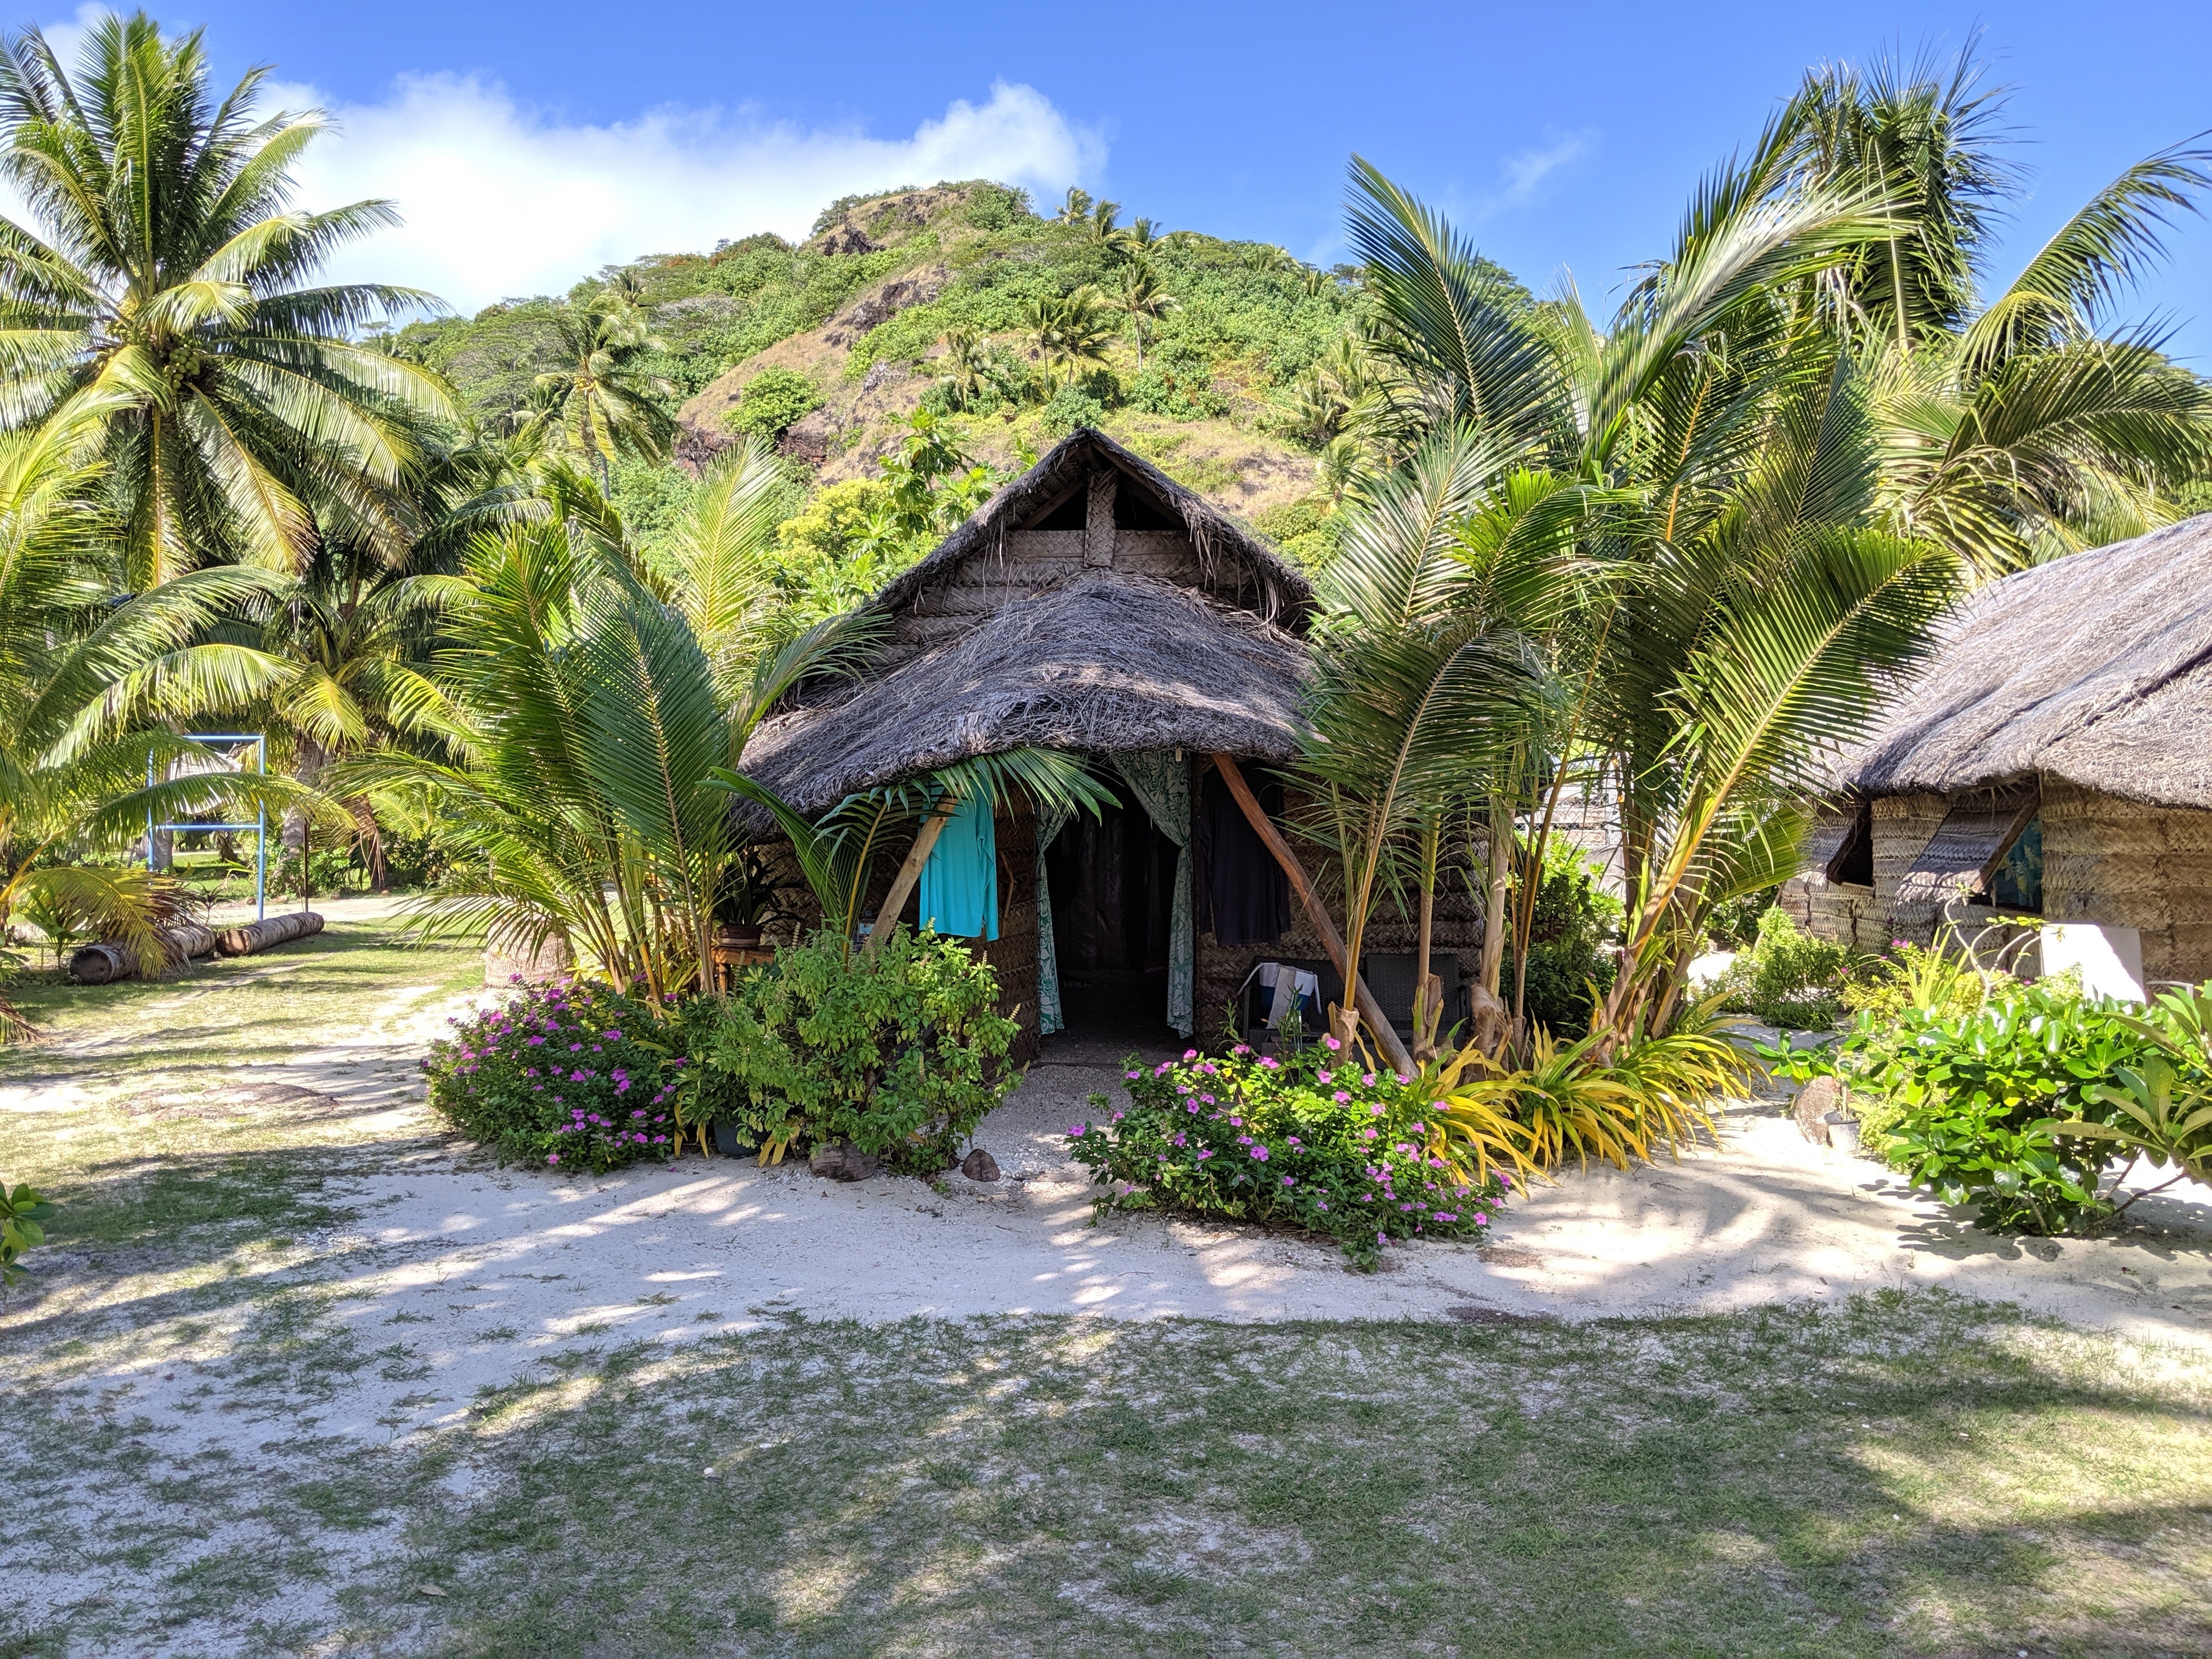
Medical evacuation may be expensive if you're visiting a remote location like Maupiti, French Polynesia. (Photo by Katie Genter/The Points Guy)
Medical evacuation protection is the main reason we initially bought travel insurance. However, by purchasing at least part of your common carrier transport using the Chase Sapphire Reserve, you, your spouse or domestic partner and dependent children under 18 (or under 25 if enrolled as a full-time student at an accredited university) will be covered on trips of five to 60 days for up to $100,000 in emergency medical evacuation coverage.
The main requirements are that the trip is at least 100 miles from your residence and Chase's benefit administrator must make the medical transportation arrangements.
The medical evacuation coverage provided by the Chase Sapphire Reserve should be adequate for most travelers. However, if your trip will last more than 60 days or less than five days — or you are visiting areas where an emergency medical evacuation could cost more than $100,000 — having The Platinum Card® from American Express may be helpful.
With an annual fee of $695 (see rates and fees), the Amex Platinum Card's emergency medical transportation benefit covers the cardmember, the cardmember's spouse or domestic partner and dependent children under the age of 23 (or under the age of 26 if enrolled in school on a full-time basis) if they become injured or ill while traveling on a trip of fewer than 90 days. As with the Chase Sapphire Reserve benefit, the Premium Global Assist Hotline medical department must assess your medical needs and coordinate your transportation. Although there is no cap on the coverage, preexisting conditions are excluded.
However, most medical evacuation protection will only cover your transport if it's medically necessary due to the inadequacy of local facilities. So, you may want to buy a Medjet membership if you'd like to be transported to a different hospital (such as one offering better care or one closer to home), even if not medically necessary.
Various credit cards provide rental car coverage. In most cases, all you have to do is pay for the rental car with your credit card and decline the rental company’s collision loss/damage insurance.
We use the Chase Sapphire Reserve to pay for car rentals because it provides primary collision damage waiver insurance for most rental cars. Specifically, the Chase Sapphire Reserve provides reimbursement for damage due to collision or theft of most rental vehicles up to $75,000 when rented for less than 31 days. And most types of rental cars are eligible.
Admittedly, our situation is different from most travelers. But even as we resume international travel later this year, we believe credit card travel protections and our health insurance will usually provide enough coverage. Although filing claims with Chase's benefits administrator can be time-consuming and frustrating, I've always been successful. And we have an emergency fund and ample points and miles that we can use to self-insure against situations that aren't otherwise covered.
For example, we bought a travel insurance policy from Seven Corners when we visited Liberia in West Africa. After all, Liberia is classified by the United Nations as a least-developed country, had an Ebola outbreak as recently as 2015, had a second civil war that ended in 2003 and has a limited number of flights each day to other countries. So, we wanted additional coverage that included evacuation for non-medical reasons. Additionally, some countries currently require you purchase a trip insurance plan. For example, if you are visiting the Bahamas in the near term, you will need to pay for the country's Travel Health Visa that includes some insurance coverage specific to COVID-19.
And, if you frequently travel from a home base, you may find that an annual travel insurance plan can provide value. Allianz and Seven Corners both offer well-rated annual plans. And many customers find it easier to file successful claims with these providers than with Chase's benefits administrator. So it may be worth buying an annual travel insurance plan simply for the convenience and peace of mind it provides.
However, there are some unique aspects to consider if you plan to travel during the coronavirus pandemic.
If we purchased an annual travel insurance policy, we'd likely buy the AllTrips Premier plan from Allianz. As Florida residents, this plan would cost us $450 per year. However, the plan's cost and details vary depending on your state of residence and age. The following table shows coverage we'd get as Florida residents:
Chase Sapphire Reserve
Allianz AllTrips Premier (Florida residents)
Trip cancellation/interruption
$10,000 per person per trip
$2,000 per year
Emergency medical
$2,500 with a $50 deductible
$50,000 per trip per insured
Emergency transportation
$100,000
$500,000 per trip per insured
Baggage loss/damage
$3,000 per person per trip
$2,000 per trip per insured
Baggage delay
$100 per day for up to 5 days when delayed at least 6 hours
$2,000 per trip per insured when delayed at least 12 hours
Trip delay
$500 per ticket when delayed at least 6 hours or overnight
$300 per day when delayed at least 6 hours (up to $1,500 per trip per insured)
Rental car damage and theft coverage
$75,000
$45,000 per trip per insured
Travel accident coverage
$1,000,000 common carrier loss of life; $100,000 24 hour loss of life
$50,000 per trip per insured
As you can see, the coverage offered is different. But, especially if you have medical insurance that will provide coverage while you're traveling, you may want to pay the Chase Sapphire Reserve's annual fee and use it to book your trips instead of purchasing travel insurance.
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.