The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
News
Credit card strategies for mortgage and home loan applicants
Senitra is a credit cards expert and TPG contributor. Senitra spent seven years working in marketing, has been a freelance writer for numerous websites and worked as a full-time reporter and editor for several daily and weekly newspapers in Texas, New Jersey and Pennsylvania. She has been quoted on her credit card expertise in MarketWatch, Consumer Reports and Kiplinger.
Credit card writer Danyal Ahmed is an avid traveler, averaging about 100,000 aeronautical miles per year. He regularly applies that knowledge and his expertise in credit cards to his role as a credit card writer at TPG.
also contributed to this story
November 1, 2024 • 9 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.
Editorial note: This is a recurring post, regularly updated with new information and offers.
Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
Opening new credit card accounts can temporarily lower your credit score, which may affect your mortgage application if done close to applying for a home loan.
Lenders focus on your down payment, monthly income versus debts, and credit score, with the latter two influenced by your credit card usage and balances.
Paying credit card balances in full before statement closing dates can help minimize the appearance of debt on your credit report, potentially improving your borrowing capacity.
Maintaining a credit score above 740 is generally sufficient to qualify for the best mortgage rates, and further increases often do not yield better terms.
What to consider
Applying for new credit after mortgage preapproval or during the loan process can alter your qualifications and potentially jeopardize your application.
Lenders view reported statement balances as current debt, even if you pay in full monthly, so timing payments before statement closing is crucial.
The impact of new credit applications is more significant for those with limited credit history or non-homeowners.
What you'll miss from the article
Detailed strategies for managing credit card balances and applications to optimize your mortgage approval and secure favorable rates.
Generated by AI with support from our editorial team.
A big part of pursuing travel rewards is learning to take advantage of credit card welcome bonuses. Thanks to a recent rate cut by The Feds and more anticipated cuts to come, home ownership or refinancing is a trending topic these days. If you anticipate applying for a home mortgage or refinance, you might be concerned about how your credit card usage could affect this process.
In this post, we’ll examine how opening new credit card accounts might affect a mortgage loan application and the steps you should take to make sure your credit is in tip-top shape so that you can get the best mortgage rate available.
How the mortgage process works
To plan your credit card strategy before you apply for a mortgage, it helps to understand just how exactly the home loan application and approval process works.
Wynn explained that there are three factors lenders will consider about your personal finances when determining your qualifications: your down payment, your monthly income (minus any existing debts) and your credit score. The second and third factors are the ones that can be affected by your credit card usage.
FOTOSTORM/GETTY IMAGES
When you first speak with a mortgage broker, you’ll give them permission to pull your credit histories and FICO credit scores from all three major consumer credit bureaus. An inquiry to your credit will count as a “hard pull,” but the FICO scoring model will combine all inquiries for home loans made within 14 days. So this is the time when you’ll want to shop around for the best rate.
Brokers pull from all three bureaus because the industry standard is to judge applicants based on the middle of the three scores (or the lower of two), in order to account for any differences in the data collected.
Next, your real estate agent might ask for a pre-qualification or preapproval from your mortgage broker. A pre-qualification is merely the broker’s opinion of your ability to qualify based on the information that you have supplied, while a preapproval generally requires documents such as pay stubs, bank statements and tax returns to be collected.
When you’re ready to make an offer on a home, the additional level of verification from a preapproval can help persuade a seller to choose your offer as they’ll feel more confident your loan will not be denied.
KATHRYN ROMEYN/THE POINTS GUY
Your mortgage broker will then help select the best lender for your needs, and you’ll be asked to submit a formal loan application. Finally, about a week before you close on your loan, your credit will be checked a final time (which is a soft pull), and your employment will be re-verified.
How your credit card accounts shape your credit score
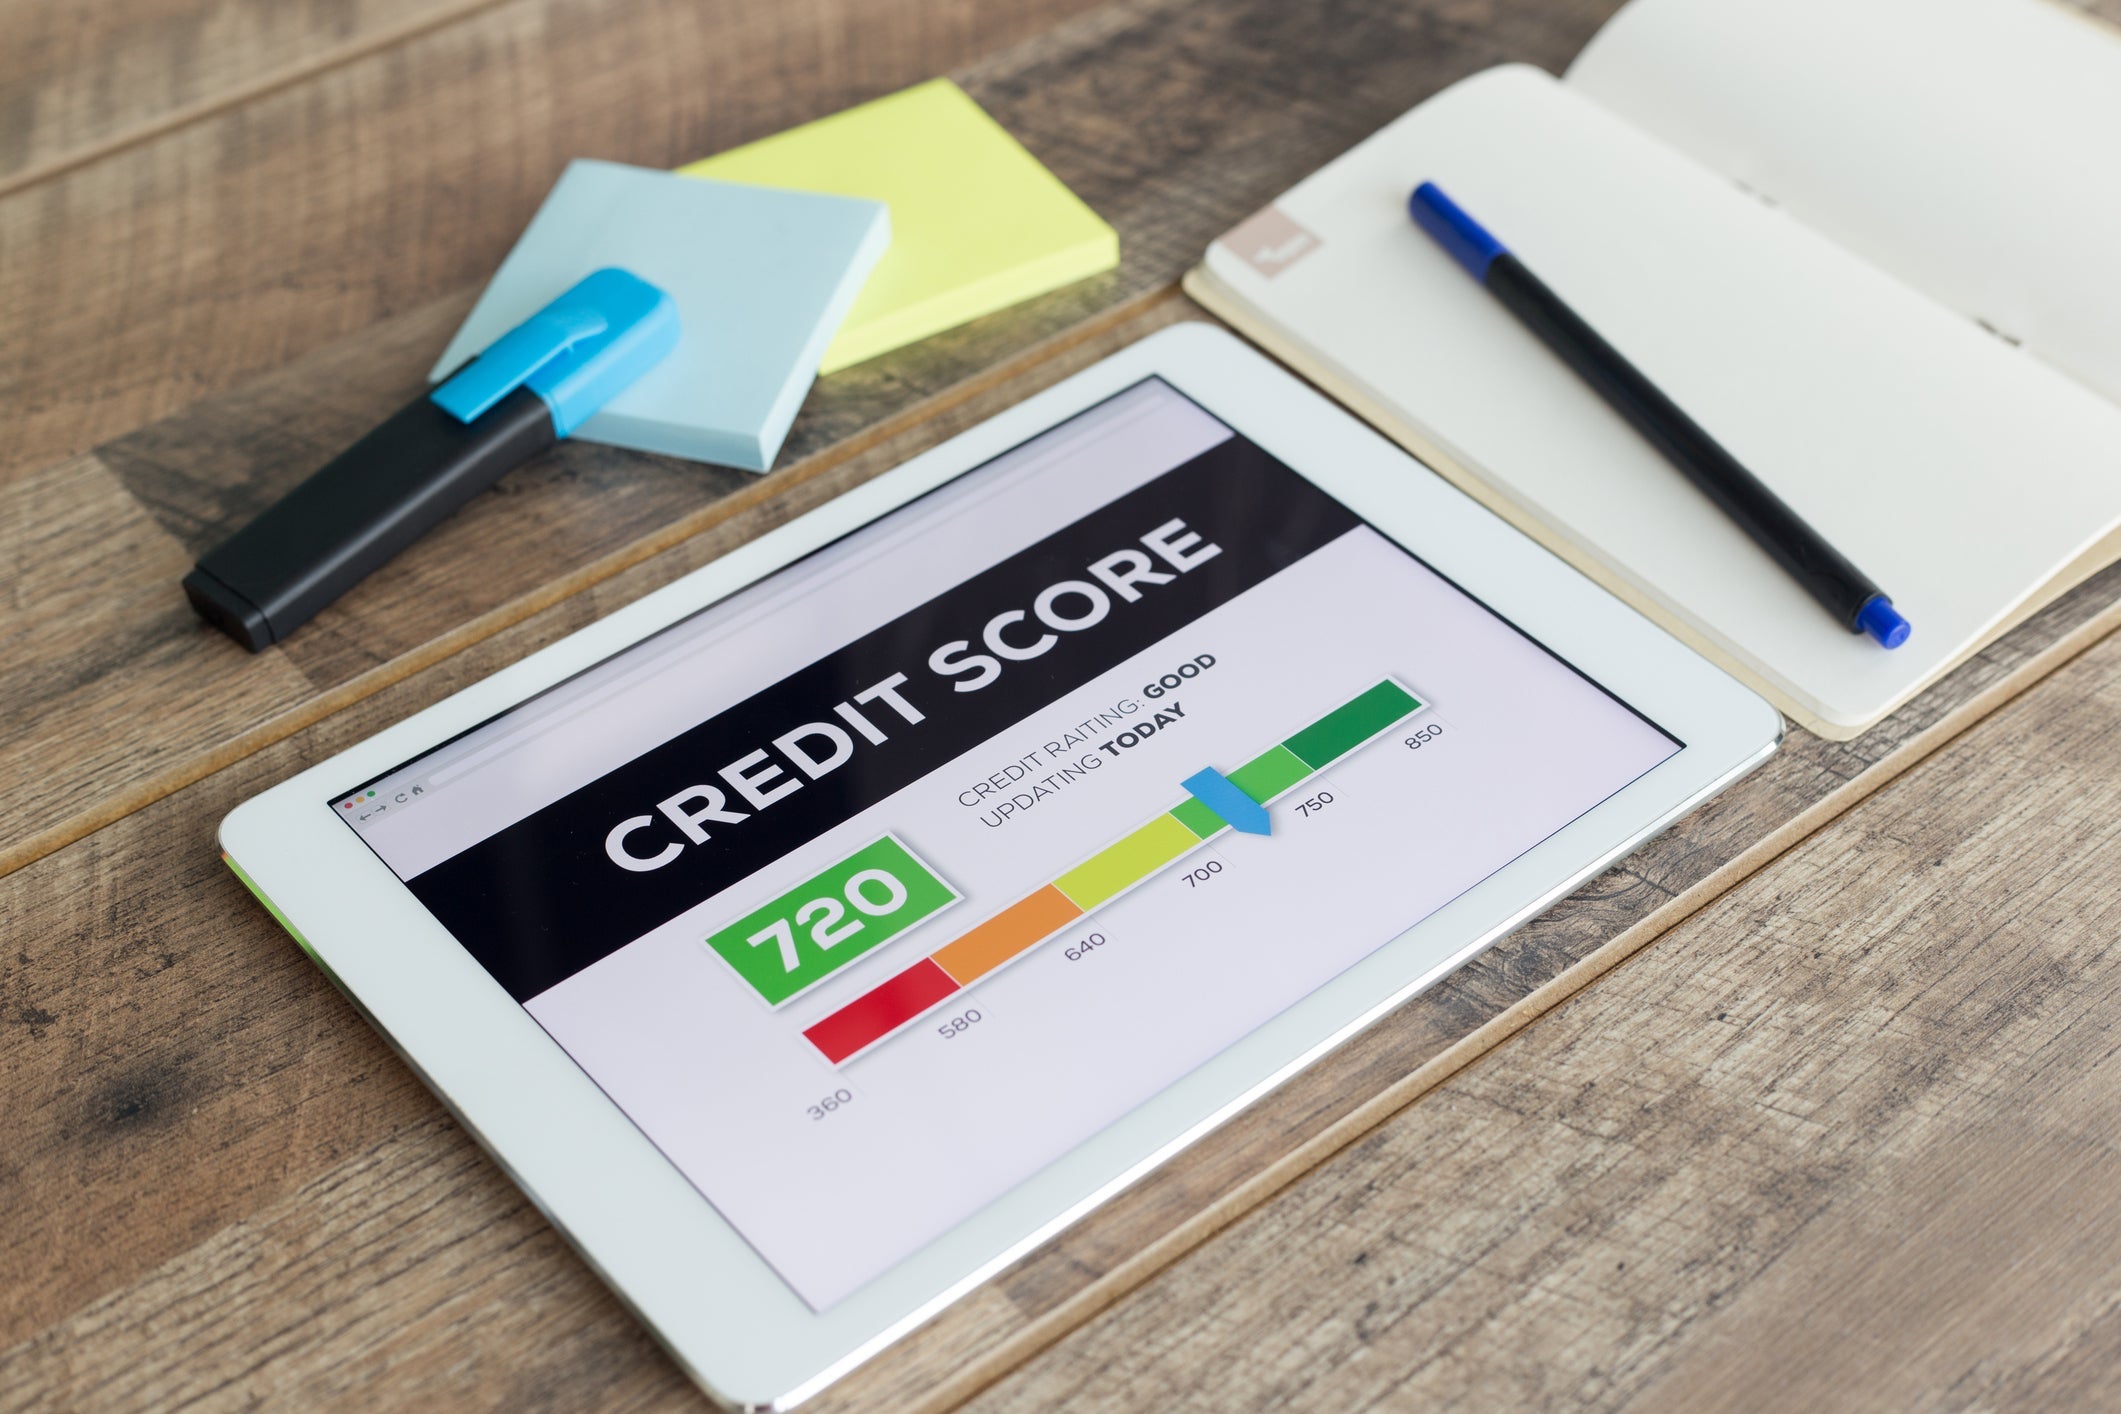
When you pay your bills on time and carry minimal to no debt, credit cards can help your credit score by adding to your overall credit history. The two most important factors that contribute to your credit score are your payment history and the amounts you owe, which comprise 35% and 30% of your credit score, respectively.
The remaining 20% is divided equally among the types of credit used and the new credit lines opened. Having credit card accounts open and in good standing will help, although applying for several new credit cards in a short period of time will hurt.
A common misconception is that you need the highest score possible for the lowest rates. To qualify for the best mortgage rates available, you need to have a credit score of 740 or above, but in nearly all cases, having a score of 760, 780, 800 or higher won’t make the slightest difference. (Wynn pointed out that he has seen some rare exceptions in the past when a lender offered a specific program that required higher scores, typically for very high value loans).
GETTY IMAGES/EYEEM
If you pay all of your bills on time and have no substantial debts other than a modest credit card statement balance, which you pay in full each month, it’s likely that you’ll have a credit score in the high 700s. Applying for a new credit card may drop your score a few points, but so long as it remains comfortably above 740, you won’t hurt your chances to qualify for the best mortgage rates.
Problems that credit cards can create with the mortgage application process
One of the problems mortgage applicants encounter comes from using credit cards heavily (even while avoiding interest by paying statement balances in full each month), which is how many award travel enthusiasts typically behave.
As cardholders see it, they have no debt, as they never carry a balance and never pay interest. From the perspective of card issuers and lenders, however, the balance that appears on each month’s statement is the amount of debt that is reported to the credit bureaus.
As Wynn explained, your credit report and credit score are just a snapshot in time, yet lenders will see the minimum payment listed as a more or less permanent debt obligation, regardless of whether you pay it in full.
D3SIGN/GETTY IMAGES
That means the moment when your statement closes is critical to your credit score, although some card issuers may report balances more frequently than once a month. So, if you’ve paid your balance but it hasn’t been reported, then your credit report will still show the higher balance.
Unfortunately, lenders will then see a greater amount of debt in your name, which affects how much they will let you borrow. Knowing this, you can choose to pay balances in full before your statements close. That way, card issuers will report $0 balances and your borrowing ability will not be impaired by the appearance of debt.
Another problem credit card users can face comes from applying for a new credit card (or any other loan) after having been preapproved for a mortgage, especially after having submitted a formal mortgage loan application. In fact, Wynn advises all of his clients to do the following after they have received pre-qualifications:
Do not use credit cards excessively.
Do not let current accounts fall behind.
Do not co-sign for anyone on a new account or loan.
Do not give permission to anyone to run your credit (by applying for new credit accounts).
His rationale is that lenders conflate new inquiries with new credit applications, which changes your qualifications for the loan. Furthermore, the impact of these negative items can be much greater for non-homeowners and people with a limited credit history.
My advice to travel rewards enthusiasts
Mortgage rates are starting to come down from record highs, so many people may be considering a home purchase or refinance to lock in a lower payment. You can check out current mortgage rates in your area here.
When you’re ready to move forward, you should speak with a mortgage broker who can quickly check your credit. Do this as early as possible to see where you stand and give yourself the opportunity to correct any mistakes.
If your score is close to 740, you should consider every option to hit that mark and stay above it, which means “fasting” from new credit card applications until the process is over. In addition, those who are looking to stretch their borrowing ability to the limit should constantly be paying their credit card balances off (even before statements arrive) to minimize the impact that debt has on their credit reports.
D3SIGN/GETTY IMAGES
If you already have a very high credit score (in the upper 700s or above), there’s no need to change your behaviors. So long as you follow Wynn’s advice from pre-qualification to closing, which should only be a few weeks in most cases, then you don’t have to use every trick possible to add a few points to an already excellent score.
Bottom line
Many travel rewards enthusiasts are very savvy credit card users, but applying for a home mortgage is a special circumstance that temporarily demands a new set of rules. By understanding the process and taking necessary precautions during this period, you can get the best mortgage rates possible and continue your pursuit of award travel right after you close on your loan and have the keys to your new home.
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.