Senitra is a credit cards expert and TPG contributor. Senitra spent seven years working in marketing, has been a freelance writer for numerous websites and worked as a full-time reporter and editor for several daily and weekly newspapers in Texas, New Jersey and Pennsylvania. She has been quoted on her credit card expertise in MarketWatch, Consumer Reports and Kiplinger.
Credit card writer Danyal Ahmed is an avid traveler, averaging about 100,000 aeronautical miles per year. He regularly applies that knowledge and his expertise in credit cards to his role as a credit card writer at TPG.
also contributed to this story
March 20, 2025 • 7 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.
Editorial note: This is a recurring post, regularly updated with new information and offers.
Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
Applying for new credit cards during a home purchase or refinance can complicate the mortgage approval process and may require additional documentation.
Experts recommend waiting until after your mortgage loan is fully funded and disbursed before seeking new credit, as premature applications can delay or jeopardize your closing.
For home purchases, wait at least a full business day after closing and confirmation of funding; for refinances, wait until the three-day rescission period has passed and funding is confirmed.
Opening new credit lines soon after a mortgage can temporarily lower your credit score due to recent inquiries and changes in your credit profile.
What to consider
Lenders may run multiple credit checks during the mortgage process, and additional inquiries can raise concerns or result in denials.
For refinances, the loan is not funded until the rescission period ends, so applying for new credit before this can create complications.
If denied for a new card after closing, contacting the reconsideration line may help overturn the decision.
What you'll miss from the article
Detailed timing strategies and expert advice for minimizing mortgage disruptions when seeking new travel rewards credit cards.
Generated by AI with support from our editorial team.
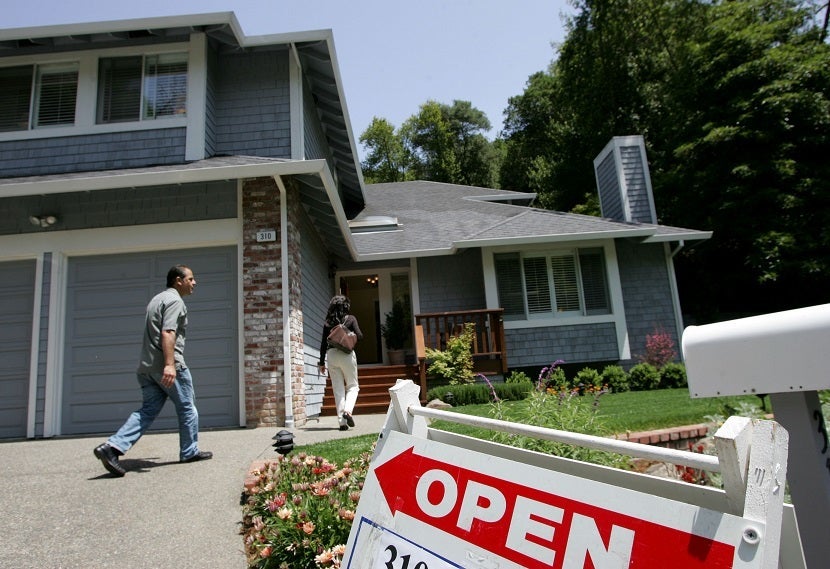
Congratulations! You've just bought (or refinanced) a house! Or, maybe you're considering the possibility.
What does this mean if you're an avid traveler who applies for travel rewards credit cards regularly? Typically, buying or refinancing a house means temporarily putting off getting the latest and greatest cards.
But just how long after closing on your mortgage do you need to wait to apply for your next travel rewards credit card? We talked to a mortgage industry professional to find out some of the dos and don'ts during the mortgage process and how long you should wait before applying for new credit cards.
Mark Karetskiy, loan officer and branch leader for the Karetskiy Lending Team with Movement Mortgage, sends prospective homebuyers a list of "Ten Mortgage Commandments of Buying a Home." Among the commandments is "Thou shalt not originate any kinds of inquiries into your credit."
"Will applying for a travel rewards credit card before closing on your purchase or refinance disqualify you from obtaining the financing?" he said. "No, not necessarily."
However, Karetskiy says it could. And it will likely cause more work, time and stress for both you and your loan officer.
"The lender's job is to make a yes-or-no decision on an applicant's request for credit based on the applicant's current and past two-year income, credit and asset history," he continued. "It is in the best interest of anyone requesting credit to keep the status quo on everything related to their qualifications, most importantly, their credit."
MARK EDWARD ATKINSON/GETTY IMAGES
The wait is over
For a home purchase, it's best to wait at least a full business day after closing before applying for new credit cards to ensure your loan has been funded and disbursed.
"Until you have the keys, don't do anything," Karetskiy said. "Even if you've signed and received confirmation that your lender has funded, the title company still needs to disburse the money. Until they do, you're not really done."
STURTI/GETTY IMAGES
The guidance changes slightly for a refinance on a primary residence because the closing date is not the funding date. With refinances, the borrower has a three-day right of rescission, which means you have three business days after closing to rescind or cancel your mortgage loan. Your refinance is not funded until these three days have passed.
"Therefore, on refinances, it is best to wait until you've received confirmation from your loan officer or lender that your loan has officially been funded and disbursed prior to resuming regular use of your credit," Karetskiy explained.
Once you've received confirmation that your closing is complete, you may want to apply for a new rewards credit card immediately. Typically, there are lots of expenses involved in moving and setting up a new house, especially for first-time buyers.
DRAZEN_/GETTY IMAGES
Since many credit cards require spending a minimum amount — often between $3,000 and $5,000 within a certain number of months — in order to receive a welcome bonus, it's fairly easy to earn a valuable welcome bonus with the purchases you'll need after buying a home.
You may need furniture, lawn equipment and appliances, and you can pay for all of these with your new rewards card.
While everyone's situation is different, applying for a new credit card shortly after closing on your mortgage can potentially lower your credit score. Adding a mortgage means you've opened new credit, increased your total amount owed, affected your credit mix and decreased the length of your credit history. Additionally, since it's a new account, you have no payment history associated with it.
D3SIGN/GETTY IMAGES
"If someone just closed on a mortgage, they are impacting every factor that goes into their FICO score," Karetskiy said. "So, it's safe to say that adding a new credit card in addition to a new mortgage in a short time frame is likely going to decrease your scores."
Sometimes, a credit card application relatively close to your home purchase may result in a pending and denied application, likely due to an increased number of recent inquiries. Typically, a lender will run your credit several times during the homebuying or refinance process, shopping for mortgage rates.
MIXETTO/GETTY IMAGES
You may also have inquiries about setting up utility services at your new home since some providers require a credit check before completing any work.
If you experience a pending approval or denial, your best bet for approval is to call the respective issuer's reconsideration line to discuss your situation and hopefully overturn the denial.
Buying a home is typically the biggest purchase of your life, and it often requires waiting until the process is complete before applying for new credit cards. But after you've received the OK from your lender and title company that everything's funded, you'll be ready to dive right back into boosting your points and miles balances one can of paint or insurance payment at a time.
Just remember that opening any new lines of credit, whether it be credit cards, personal loans or car loans, can lengthen (or sometimes even jeopardize) the homebuying or refinance process. The rewards credit card landscape is vast, and a few months of patience is all you need to have the best of both worlds.
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.