The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
News
More retailers are launching credit cards — but are they worth it?
Chris was a reporter at The Points Guy, where he covered the intersection of credit card rewards and travel. At TPG, he wrote a broad array of stories ranging from in-depth features and reports to trending travel news as it related to loyalty, card benefits and consumer behavior.
Madison Blancaflor is the managing editor for TPG's content operations team. She focuses on helping TPG's broader editorial team bring news, features and advice to readers. She has nearly six years of experience covering the credit cards and travel industries.
also contributed to this story
January 18, 2021 • 7 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
Retailers are increasingly launching their own credit cards to adapt to changing consumer habits and boost loyalty programs.
These cards often target specific spending categories, such as health and wellness, and offer digital-first experiences.
While appealing to brand loyalists, most retail credit cards lack flexibility in earning and redeeming rewards compared to broader rewards cards.
Cobranded travel cards typically provide more robust perks and sign-up bonuses than most new retail cards.
What to consider
Retail credit cards often restrict rewards to brand-specific purchases, limiting their appeal for general use.
Many retail cards offer fewer perks and less flexibility than traditional rewards or travel-focused cards.
Some offers mentioned in the article are no longer available.
What you'll miss from the article
A detailed comparison of retail versus travel cobranded cards, including insights on which types of consumers might benefit most from each.
Generated by AI with support from our editorial team.
Update: Some offers mentioned below are no longer available. View the current offers here.
The latest brand with plans to launch a credit card may offer some insight into the future of the industry.
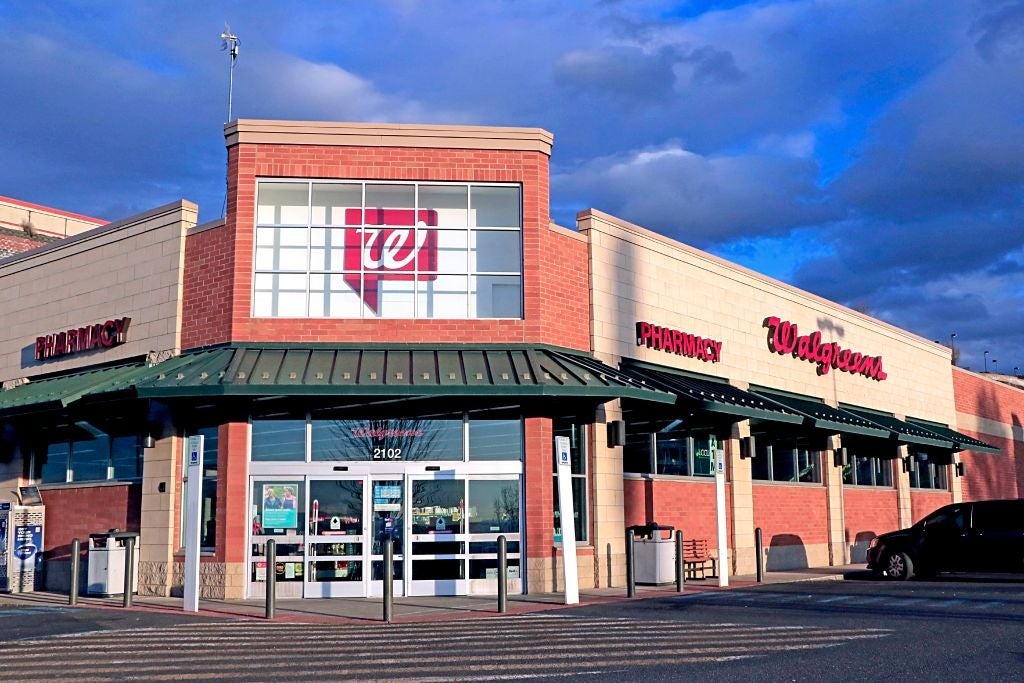
Walgreens — yes, that corner drugstore — will unveil a lineup of credit cards later this year in partnership with Mastercard and Synchrony Bank as it pushes to expand its core business.
On the surface, creating a credit card may seem like an odd choice for a brand known for its brick-and-mortar locations to pick up cold medicine and snacks. However, Walgreens is just the latest company to announce (or launch) a credit card in the past year in the midst of the pandemic. And it’s not as strange as it may seem.
As brands closer align with customer loyalty programs — and digitization accelerates — we’ll likely see this trend continue. Let’s take a closer look at why these cards are launching now — and if they are actually worth your while.
Why Walgreens (and others) are launching cards now
It boils down to this: Companies are trying to appeal to the modern consumer in a COVID-19 world.
Walgreens is a prime example of a company that is adapting to changing consumer behavior. In-person jaunts to pick up a prescription or browse for candy are being replaced by online purchases and digital pharmacies.
The pandemic has forced Walgreens — like many other brands — to accelerate its plans to reach customers in new ways. And that’s where the loyalty and credit cards angle comes into play.
(Photo by Don & Melinda Crawford/Education Images/Universal Images Group via Getty Images)
Take this pivot for instance. Walgreens launched its myWalgreens loyalty program in November 2020 — and is shifting its business focus to wellness, health and well-being.
According to a statement from Walgreens President John Standley, that includes a “commitment to providing customers and patients with unparalleled loyalty and rewards experiences for managing their health and well-being.”
For the Walgreens credit card, that means consumers can expect accelerated rewards and bonuses in the health and wellness category, along with a mobile-first experience.
Last year, Verizon launched a card of its own, issued by Synchrony Bank. Beyond core products and services, cobranded cards can be serious moneymakers for brands. From merchant interchange fees to interest and late payments, this additional revenue stream can be a cash cow. And you can bet companies such as Verizon and Walgreens took notes from the world of airline and hotel cobranded cards.
In 2020 and at least for the first half of 2021, there remains a strong appetite for non-travel cash-back cards, particularly with bonus categories that align closer with how many people are spending currently.
We’ve seen a number of new non-travel rewards cards launch in recent years from retailers including Apple, Starbucks, Verizon, Walgreens, Venmo and more. But are these new retail-centric cards entering the market a good value for cardholders?
Are these cobranded retail cards worth applying for?
The short answer? Rarely.
The thing that many of these credit cards lack is flexibility — both in earning and redeeming. While cards such as the Chase Freedom Unlimited — one of the top cash-back credit cards on the market — offer solid earning opportunities across a wide range of categories and an easy redemption process that makes using rewards simple, many retailer cards make it harder to earn and burn rewards. That hinders their ability to compete.
Take the Verizon Visa® Card, for example. On paper, the card offers great bonus categories: 4% on gas and groceries, 3% on dining, 2% on Verizon purchases and 1% on everything else. However, those rewards are earned via Verizon Dollars that can only be redeemed for Verizon purchases.
(Photo courtesy of Verizon)
This means that retail cards like Verizon and Walgreens are really only valuable to a certain type of customer who can’t find that same value elsewhere. In this case, a Verizon customer with a monthly phone bill may find enough value in the card’s bonus categories to justify applying. But most of the time, other cards prove to be more valuable — even for Verizon customers.
Even the Venmo Credit Card, which does offer more in terms of flexibility than most of the brand-specific cards that have come out in the past year, still doesn’t quite measure up to a lot of the top cash-back credit cards. That’s because Venmo caps the annual spending limit at $10,000, which means you can only earn up to $300 cash back per year.
Those who use Venmo as a cornerstone of their daily shopping habits may find value in the card, but you can still find better bonus categories with other cards.
The information for the Verizon and Venmo cards has been collected independently by The Points Guy. The card details on this page have not been reviewed or provided by the card issuer.
The argument for cobranded travel credit cards
Perhaps a more direct comparison are airline and hotel cobranded cards. Like retailer cards, they are marketed toward loyal customers of a specific brand rather than a broader audience. But cobranded travel cards have still mastered two important elements of the credit card game that these retail cards still lack — sign-up bonuses and perks.
While some cobranded credit cards may offer less flexibility than traditional rewards credit cards, they typically come with solid welcome bonuses and/or brand-specific perks. The Delta SkyMiles® Gold American Express Card, for example, offers a $100 Delta flight credit after spending $10,000 in purchases in a calendar year, travel protections, a Pay with Miles discount and your first checked bag free.
Even the IHG Rewards Traveler Credit Card (a no-annual-fee cobranded hotel card) comes with a list of perks to help entice cardholders to keep it.
Cobranded cards often come with perks. So while they may not be as flexible as other rewards cards, the benefits outweigh that. (Photo courtesy of IHG)
At the end of the day, it’s harder to justify keeping retail cards when they offer little in the way of sign-up bonuses, perks or flexibility. For most credit card shoppers, there are simply more valuable credit card options out there right now.
Bottom line
To be fair, we don’t yet have the exact details on the Walgreens credit card lineup to be launched later this year. But the overarching theme of these new retail credit cards the past year has remained the same — solid bonus categories on a surface level, but little in the way of sign-up bonuses, perks and/or flexibility.
While the credit card market might be an enticing industry for brands to explore as the brand loyalty game continues to evolve at a rapid pace, we’ve yet to see many of these retail brands offer a compelling card offer that can compete against top cards from banks such as Chase, American Express and Capital One.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.