The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Guides
These are the three types of cards I keep in my wallet
Ethan's been a frequent flier for as long as he can remember, from studying abroad in Paris to moving to Shanghai after graduating college, where he served as TPG's eyes and ears for all things travel in the Asia-Pacific region. If you asked him where he wants to travel next he'd quote Anthony Bourdain and tell you "anytime I'm eating spicy noodles in a bowl, I'm happy."
July 16, 2020 • 8 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
A well-rounded credit card strategy involves carrying cards that serve different purposes, such as maximizing rewards, unlocking valuable perks and supporting credit health.
Cards used for everyday spending often provide strong returns at select merchants, while others are kept mainly for their travel or lifestyle benefits.
Some cards are retained primarily to help build and maintain a strong credit score, even if they are rarely used for purchases.
Maintaining a mix of card types can increase redemption flexibility and long-term financial value.
What to consider
Certain cards offer high value through annual credits or exclusive benefits, but may require enrollment or have usage restrictions.
Keeping older, inactive cards open can improve your credit score by increasing your average account age, but occasional activity may be needed to avoid closure.
Valuations for hotel points can vary, and maximizing free night certificates may yield outsized value per TPG's valuations as of June 2024.
What you'll miss from the article
A detailed breakdown of how to balance card types for optimal rewards, perks and credit-building over time.
Generated by AI with support from our editorial team.
Update: Some offers mentioned below are no longer available. View the current offers here.
Diversity is incredibly important in your credit card strategy for a lot of reasons. You need cards with different bonus categories, perks that don't overlap, and ideally cards that earn different types of points so you'll have more flexibility when you're ready to redeem.
It's also important to think about the role different cards play in helping you build your credit score. If all you ever do is open cards for the welcome bonus and close them a year later, sooner or later your credit score will take a hit. Today I'm going to talk about the three kinds of cards I carry in my wallet, and how each one helps me earn points, travel better or build a strong credit score.
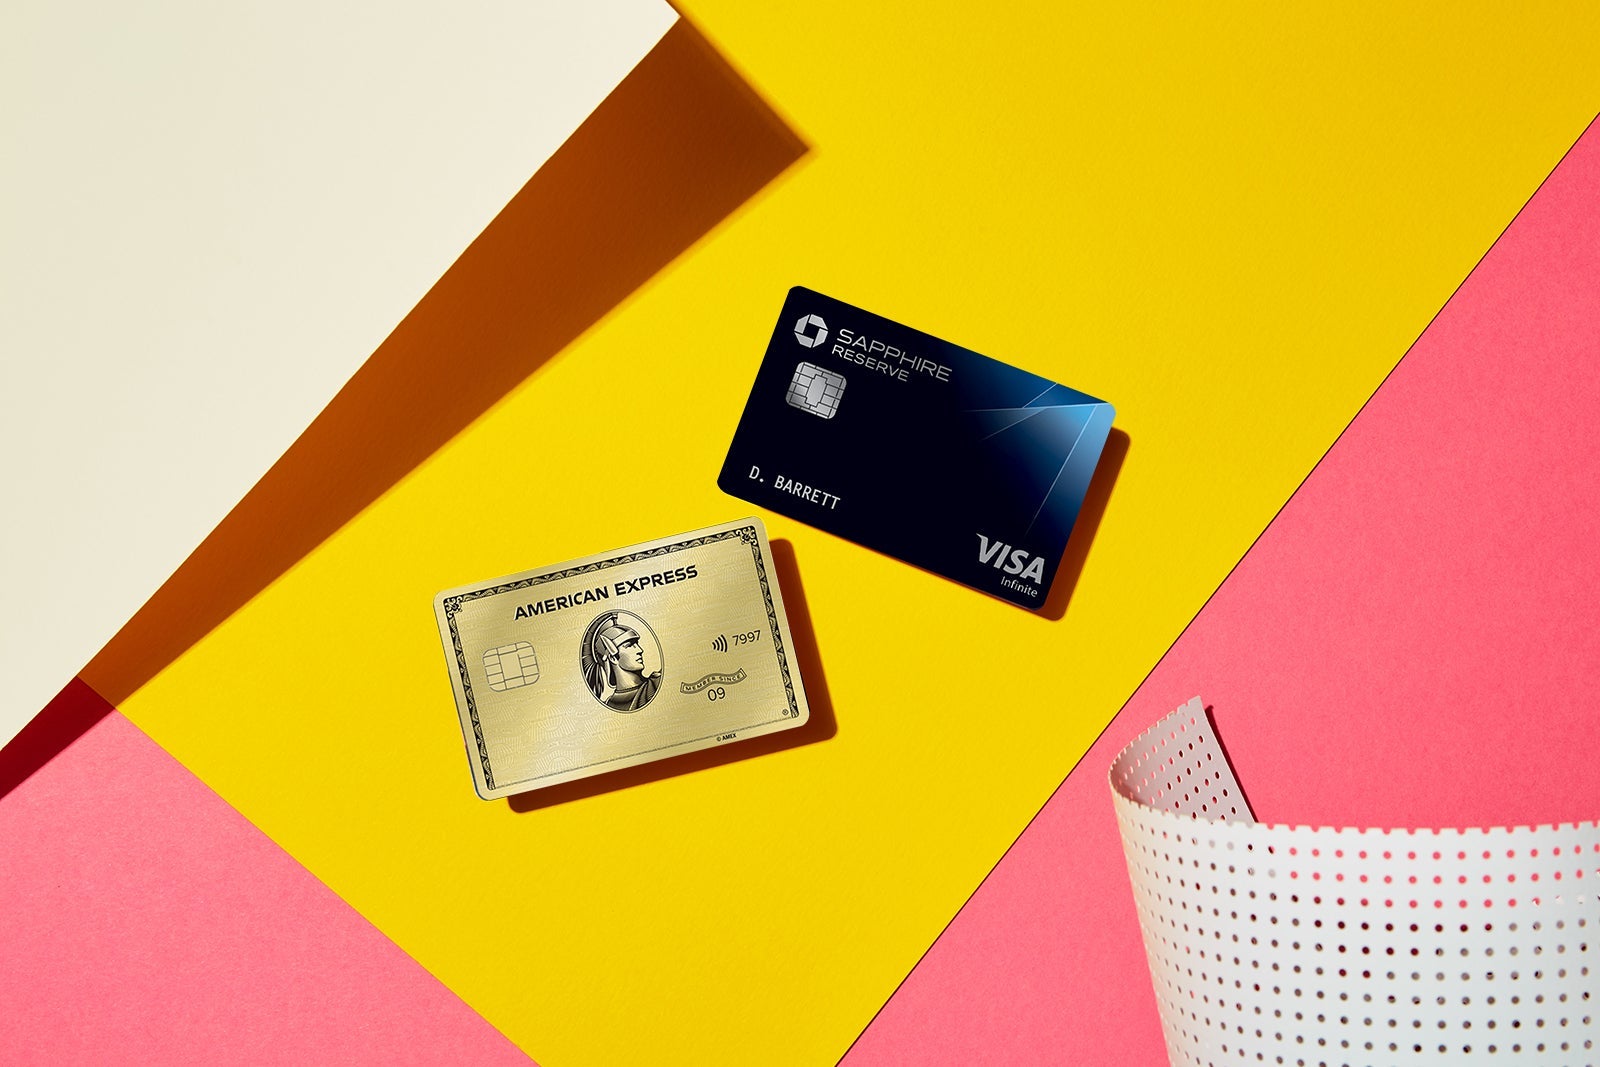
This is the simplest and most obvious category, as it represents the cards that I actually carry in my wallet as opposed to leaving in a desk drawer at home. Within this category you'll find two different types of cards: cards with strong bonus categories like the American Express® Gold Card which I use for all my dining at restaurants and grocery purchases at U.S. supermarkets and the Chase Sapphire Reserve® that I use for travel expenses. Prepandemic, I'd estimate that as much as 50% of my monthly expenses went on one of these two cards.
Knowing that I spend heavily on travel and food, I was able to target cards that offer high returns in those categories. With the Amex Gold I earn 4x on restaurant purchases and at U.S. supermarkets (up to $25,000 in purchases per calendar year at U.S. supermarkets; then 1x). TPG values Membership Rewards point at 2 cents each, making that a very solid 8% return. Similarly, the Sapphire Reserve earns 3x points per dollar on a very broadly defined travel category, letting me rack up thousands of bonus points a year paying for airfare, hotels, rideshares, parking meters, group tours and a host of other things.
The other half of my expenses don't clearly fall into a single bonus category, so I use a card that offers a strong return on everyday spending. For me that usually means rotating between The Blue Business® Plus Credit Card from American Express (2x Membership Rewards points per dollar on your first $50,000 in purchases per calendar year; then 1x) and the Chase Freedom Unlimited® (1.5% cashback / 1.5x Ultimate Rewards points on purchases).
The premium credit card market has continued to grow in recent years, with new offerings and product refreshes convincing customers to pay hefty annual fees to unlock luxury travel and lifestyle perks. I pay the $695 annual fee (see rates and fees) on The Platinum Card® from American Express every year, but I'd be shocked if I made more than 10 purchases on the card in a calendar year. While The Platinum is the original premium rewards card, it only offers one narrowly defined bonus category and I have other ways to earn Membership Rewards points (see above).
Still, I'm able to get a good value each calendar year by using the card's up to $200 airline incidental fee credit, up to $200 annual Uber credit ($15 a month with a $20 bonus in December), the up to $100 Saks Fifth Avenue credit (broken down to $50 from January to June and another $50 from July to December), and the occasional money-saving Amex Offer. Add in access to Amex's growing collection of Centurion Lounges, some of the best airport lounges in the world, and I feel like I get my money's worth every year. Enrollment required for select benefits.
(Photo by Eden Batki/The Points Guy)
One of my other favorite credit cards, the Marriott Bonvoy Brilliant® American Express® Card, falls into this category as well. I happily hold four different Bonvoy credit cards, but put all my spending on the Marriott Bonvoy Business® American Express® Card, not the Bonvoy Brilliant.
Still, the Brilliant offers an incredibly compelling value proposition. In exchange for a $450 annual fee (see rates and fees) you get an up to $300 annual Marriott property statement credit on eligible purchases at hotels participating in the Marriott Bonvoy program. The credit can be used for room rates, food and drink, spa treatments and certain other incidental charges. That's as good as cash to me, knocking the out of pocket cost for the card down to just $150.
Enter the most valuable benefit on the card, the annual free night certificate worth up to 50,000 points. TPG values Marriott points at .8 cents each, meaning you "pay" $150 for a free night worth $400, but it's easy to get even more value than that. This year I redeemed my 50,000 point free night certificate at the St. Regis Langkawi, for a room that would've otherwise cost $650. That's to say nothing of the massive pool suite we were upgraded to or the incredible free breakfast we received thanks to my Titanium elite status, easily bringing the value of this one night to $800 or more.
Our upgraded suite at the St. Regis Langkawi featured as much space outside the room as in, including a private pool (Photo by Ethan Steinberg / The Points Guy)
No-annual-fee cards that boost my credit score
It might surprise you to hear that a decent portion of my wallet consists of cards that I don't spend any money on and that don't offer any meaningful benefits. In many ways, these are the most important cards. A great example would be The Amex EveryDay® Credit Card from American Express, one of the first cards I opened after maxing out my 5/24 slots with Chase. The card doesn't offer any valuable travel perks, and it's earning rate isn't as good as other cards in my wallet. But because this card has no annual fee, I plan to keep it open forever, increasing the average age of accounts and providing a serious boost to my credit score. The information for the Amex EveryDay card has been collected independently by The Points Guy. The card details on this page have not been reviewed or provided by the card issuer.
(Photo by Eric Helgas for The Points Guy)
I have a few other cards that fall under this category, and the truth is these are the only cards I can say for certain I'll always keep. While I love my Chase Sapphire Reserve, I could easily imagine Chase tweaking the benefits or raising the annual fee in the future to a point where I couldn't justify it anymore. But for cards that have no annual fee, no amount of benefit changes or devalued earning rates would cause me to close the card as it costs me nothing to keep it open. Just be sure to put a small charge on the card every nine-12 months (like a pack of gum or a $1 Amazon balance reload) so the banks don't close it for inactivity.
Bottom line
Holding different types of credit cards means more than just Visas and Mastercards or airline miles and hotel points. It means holding cards that serve different purposes and potentially even holding a large number of cards that you rarely spend anything on.
For rates and fees of the Platinum Card, please click here. For rates and fees of the Marriott Bonvoy Brilliant Card, please click here.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.