The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
News
How a single car payment dropped my credit score by double digits
Nick Ewen is TPG's editor-in-chief and helps readers leverage credit cards (he has more than 25 of them) and loyalty programs to travel more for less. He's been at TPG for over 11 years.
August 30, 2020 • 8 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
A large credit card purchase for a car lease down payment resulted in a temporary double-digit drop in the author's credit score.
Credit utilization, both overall and on individual cards, significantly impacts credit scores even if total utilization remains low.
Adding authorized users to your credit cards can affect both your score and theirs, depending on spending and balances reported.
Paying off large purchases before the statement closing date can help avoid negative credit score impacts.
What to consider
Credit bureaus factor in both total and individual card utilization when calculating scores, so a single large purchase can have outsized effects.
Authorized user activity appears on both the primary and authorized user's credit reports, influencing eligibility for future credit products.
Paying off large balances before the statement closes can prevent temporary score drops due to high utilization.
What you'll miss from the article
A detailed walkthrough of how credit utilization and authorized user status interact to affect your credit score after significant purchases.
Generated by AI with support from our editorial team.
Update: Some offers mentioned below are no longer available. View the current offers here.
Understanding everything that goes into your credit score isn't an easy proposition. Sure, there are only five factors that the credit bureaus consider in these calculations — payment history, amounts owed, length of credit history, new credit and credit mix. However, the confusion surrounding the practical, real-life applications of these factors is widespread.
And this past week, despite years of writing about and understanding credit, a single decision resulted in a double-digit drop in my VantageScore.
Here's what happened — along with some practical considerations for you to avoid the same fate.
My wife's new car
My wife leases a new car every few years, and her current lease was up on July 31, 2020. As a result, she started sfhopping for a new offer this summer. After some exploration, she decided to stick with her current brand and went with the newer version of her existing Lexus.
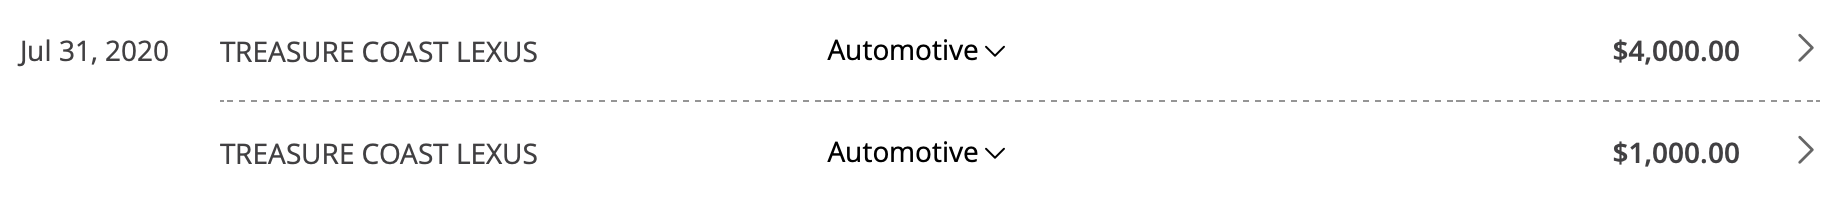
Wanting to minimize her time in the dealership due to the ongoing coronavirus pandemic, she communicated extensively via email and over the phone with the sales agent, and she was thrilled to discover that she could put the entire down payment ($5,000) on a credit card — with no fee. Since we combine our Chase Ultimate Rewards points in a single account to ensure they can all be transferred to partners, she swiped her Chase Freedom Unlimited to earn 1.5% back (effectively 1.5x Ultimate Rewards points).
A few weeks after the payment, I received an email from my credit-monitoring service, letting me know that my credit score recently changed. As someone who is fiercely protective of my credit report, I (naturally) wanted to check out what had happened. After logging into my account, I was surprised to see the following:
My TransUnion score had dropped 17 points.
My Equifax score had dropped 14 points.
I found this strange at first. I hadn't missed any payments, nor had I recently applied for a new credit card. In fact, it had been several months since I added the American Express® Gold Card to my wallet — notably without a welcome offer.
Upon further digging, however, I came across the culprit. Both of those bureaus had received information from Chase showing a much higher balance on my wife's Freedom Unlimited card. And because I am an authorized user, it appeared on my credit report as well.
This all relates to the "amounts owed" on your credit accounts — frequently called credit utilization — which looks at how much of your available credit you're using at a given time. This is the second most-important factor in your credit score, making up 30% (behind only payment history at 35%). It's also the one that could be most affected when you close or cancel a credit card.
Here's what's interesting: The general recommendation is to keep your utilization under 30%, and at the time of the score drop, I was at a total of just 2% across all of my cards.
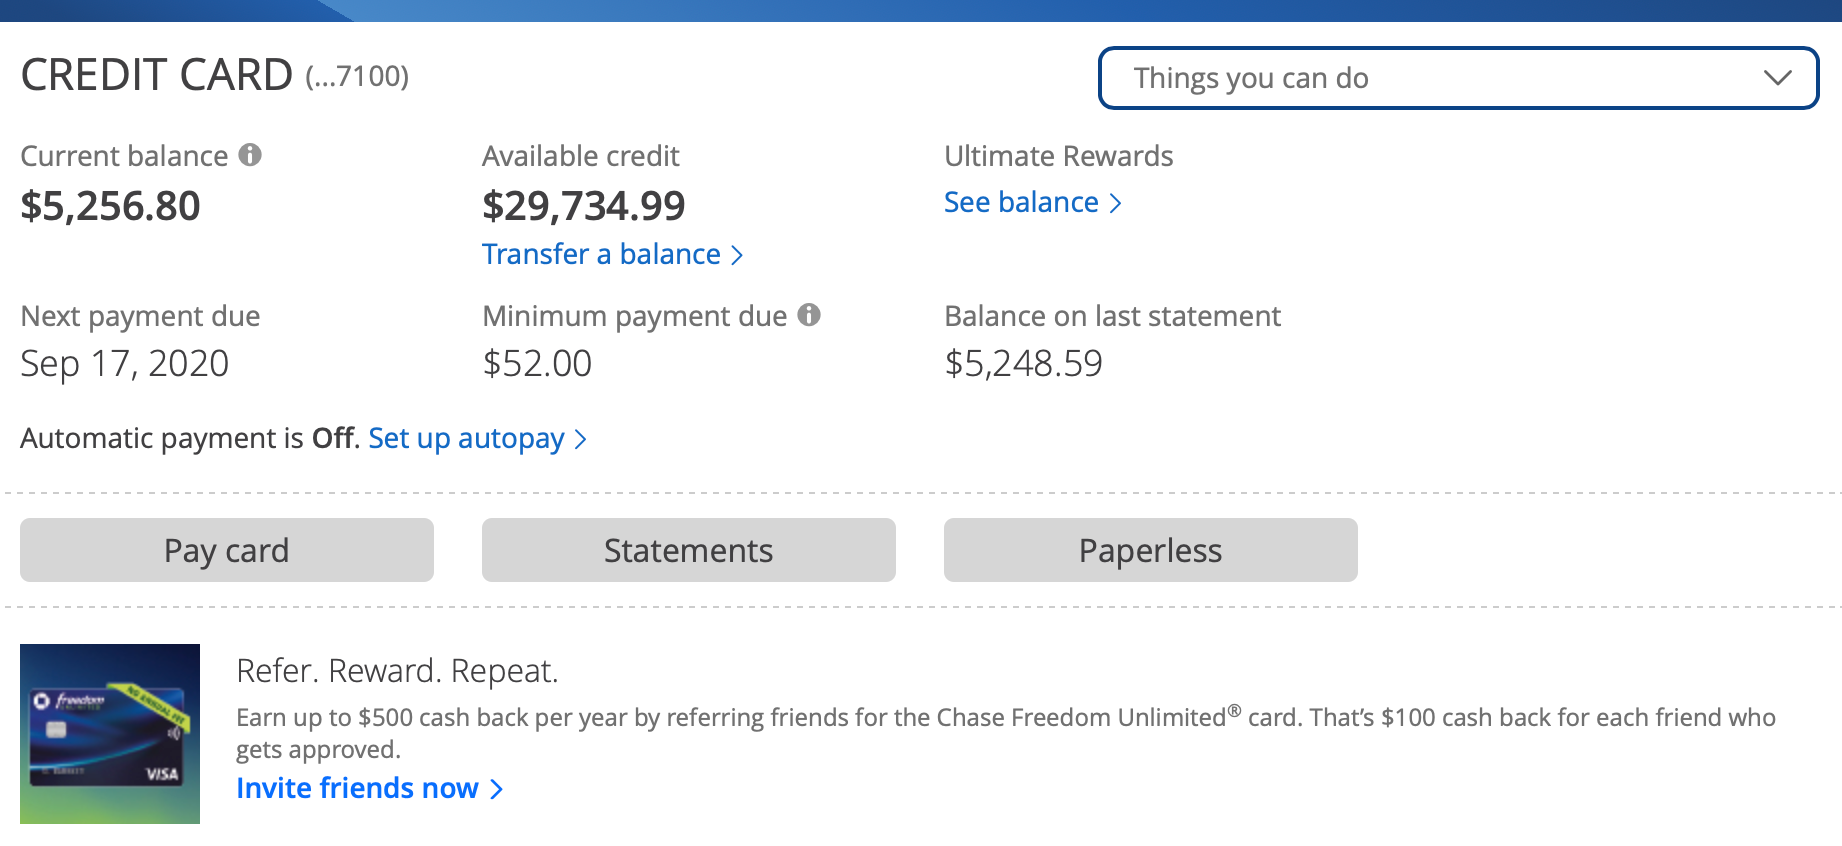
Unfortunately, the major credit bureaus consider both your total utilization and specific utilization on individual cards when computing your score — and in a single month, my wife's card (on which she has a $35,000 credit limit) went from 1% to nearly 15%:
Screen shot courtesy of Chase
Without the car payment, her statement balance would've been a paltry $248.59. After all, we're still spending a large chunk of time at home and haven't incurred a ton of expenses. But that single, $5,000 transaction was enough to lower my VantageScore by more than a dozen points.
What this means for you
At the end of the day, my TransUnion and Equifax scores are still over 800, so this shouldn't have any long-term effects on my overall credit report. Nevertheless, there are some important lessons to take away from my experience.
It's not always just about the points
Here at The Points Guy, we love our points and miles. Yet sometimes, the pursuit of rewards can blind us to other factors that should be considered when making a purchase, including the following:
Certain cards carry benefits for authorized users, but there are other factors at play. (Photo by Isabelle Raphael / The Points Guy)
Remember the impact to (and from) authorized users
There are many reasons to have authorized users on your credit cards. I love that my brother and sister can utilize the array of perks on my Platinum Card® from American Express (part of my Christmas present to them each year). It's great that my wife can swipe my Amex Gold at restaurants and grocery stores to earn bonus points on those purchases. And I enjoy the fact that my five-year-old daughter is already building credit history as an authorized user on my Freedom Unlimited.
As the primary cardholder, you're responsible for any purchases they charge to the account, and being added as an authorized user can count as a brand-new account when an issuer is considering your eligibility for a new card (especially applicable for Chase's 5/24 rule). And your transactions can also impact their score — which is exactly what happened to me as an authorized user on my wife's account.
Consider paying off a large purchase immediately
If you have a large purchase to make on a credit card — one that will immediately push your utilization on said card over 10% — consider paying it off immediately (if you have the cash to do so, of course). If you do this before your card's statement closes, it's highly likely that your higher balance won't ever be reported to the credit bureaus, keeping your utilization much lower and maintaining your high score.
In hindsight, that's exactly what my wife should've done, and I'm annoyed at myself for not even thinking about it. Knowing that her lease was coming to an end, she had been putting aside money for a down payment for several months. In fact, she was planning to simply write a check when the time came — but was pleasantly surprised to find that she could use a card to rack up additional Chase Ultimate Rewards points.
However, we should've realized that paying it off immediately, ahead of her Aug. 21 statement closing date, would've been the prudent move. This would've kept her utilization on the card under 1% and would've prevented the resulting drop in my credit score.
As noted above, this mistake represents a very minor blip on my credit report, and it shouldn't be long before my score climbs back up. And even with the drop, a VantageScore of 800+ is considered "Excellent" and likely won't interfere with any future applications for credit.
Nevertheless, this was an important learning experience for me. While large purchases can be a great way to boost your rewards by swiping the right credit card, there are important considerations that might lead you in a different direction.
Photo by alexfan32/Shutterstock
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.