The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Guides
What credit score do you need to get the Citi / AAdvantage Business World Elite Mastercard?
Katie Genter is a digital nomad who has traveled full time since June 2017. She writes and edits stories about points and miles, and loyalty programs, often letting her personal experiences color these stories.
Credit card writer Danyal Ahmed is an avid traveler, averaging about 100,000 aeronautical miles per year. He regularly applies that knowledge and his expertise in credit cards to his role as a credit card writer at TPG.
also contributed to this story
January 21, 2025 • 9 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.
Editorial note: This is a recurring post, regularly updated with new information and offers. Citi is a TPG advertising partner.
Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
A small-business travel rewards card requires a good personal credit score, typically around 730, for the best approval odds, though lower scores may still qualify depending on your profile.
Eligibility for a sign-up bonus is limited to those who have not received one for this specific product in the past 48 months.
Applicants must have a business, but sole proprietors and freelancers can qualify without a registered business entity.
The card provides benefits such as a free checked bag on select domestic flights and priority boarding, appealing to frequent travelers with certain airlines.
What to consider
Approval is based on personal credit score, but business credit may also be reviewed if available.
You can only receive a sign-up bonus if you have not earned one for this product in the past four years.
Application rules limit you to one new card every eight days, two in 65 days, and one business card in 90 days.
What you'll miss from the article
A detailed breakdown of credit score factors, reconsideration strategies if denied, and tips for maximizing loyalty program redemptions.
Generated by AI with support from our editorial team.
If you’re thinking about applying for the Citi® / AAdvantage Business™ World Elite Mastercard® (see rates and fees) — formerly known as the CitiBusiness® / AAdvantage® Platinum Select® Mastercard® — but are uncertain whether your credit score qualifies you for approval, we can help with that.
Let’s look at the different factors you should consider before deciding on whether or not you should apply for this small-business rewards credit card.
What credit score do you need to get the Citi / AAdvantage Business World Elite Mastercard?
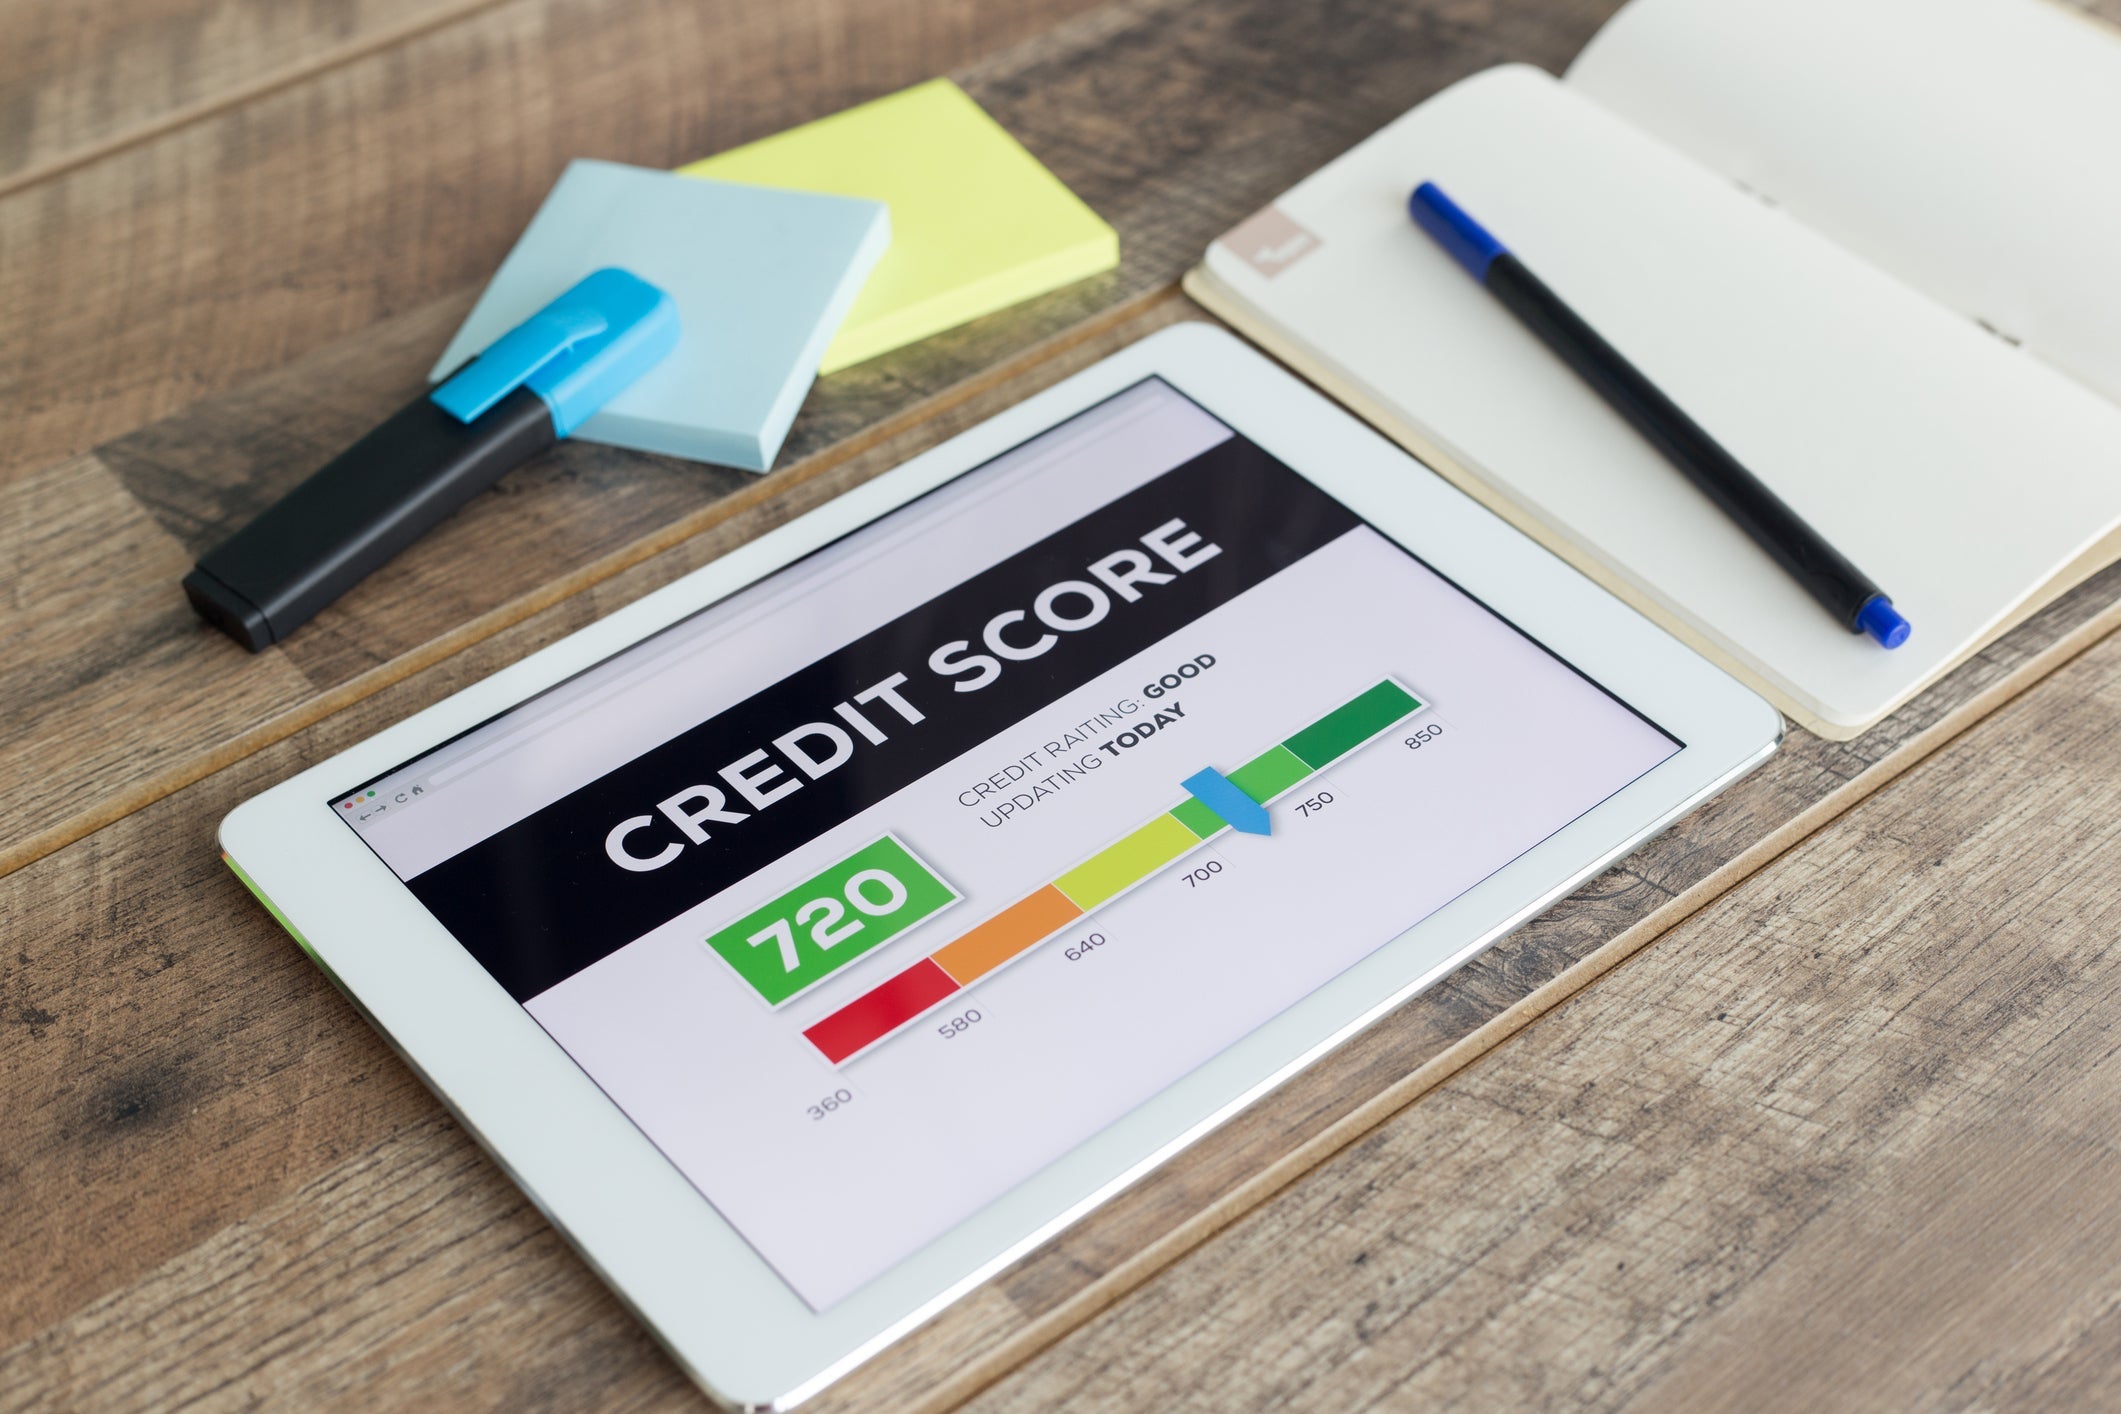
Citi doesn’t publish specific credit scores that are needed to be approved for the Citi / AAdvantage Business World Elite Mastercard. After all, your credit score is just one of many factors that Citi will take into account when deciding whether to approve your application. But you’ll generally need a good credit score of at least 730* to be approved for a rewards credit card.
It is, however, possible to get approved with a lower score depending on your specific application details.
*The Points Guy credit ranges are derived from FICO® Score 8, which is one of many different types of credit scores. If you apply for a credit card, the lender may use a different credit score when considering your application for credit.
Who should get the Citi / AAdvantage Business World Elite Mastercard?
The Citi / AAdvantage Business World Elite Mastercard is a decent card if you want extra perks when flying American Airlines.
As a cardholder, you’ll get the first checked bag free on American Airlines domestic itineraries for you and up to four companions traveling on the same reservation. The $99 annual fee is waived the first year, but in subsequent years it’s easy to justify this fee if you check at least three bags a year.
ZACH GRIFF/THE POINTS GUY
With this card, new cardholders can earn 65,000 bonus miles after spending $4,000 on purchases in the first four months from account opening. Based on TPG's March 2026 valuations, the welcome bonus is worth $1,040.
You earn 2 AAdvantage miles on eligible American Airlines purchases, as well as spending with telecommunications merchants, cable and satellite providers, car rental merchants and gas stations. All other purchases earn 1 mile per dollar spent.
The card application notes that “American Airlines AAdvantage bonus miles are not available if you have received a new account bonus for a Citi / AAdvantage Business World Elite Mastercard account in the past 48 months.” So, if you’ve received a sign-up bonus for this card in the last four years, you won’t be eligible to earn another bonus at this time.
Do I need a business to get a business credit card?
Yes, you do need a business to get a business credit card, but many types of small businesses can be eligible, including some work that you may not have previously considered. For example, selling items online, providing music lessons, tutoring children, freelance jobs or managing a rental property can all make you eligible for a business credit card.
VGAJIC/GETTY IMAGES
You don’t have to have a registered business to apply for a business credit card. You can select “sole proprietor” as the type of business when filling out the application, enter your name as the business name and enter your Social Security number as your tax ID number.
It’s important to realize that you don’t just have one credit score. Instead, there are different calculation methods and credit reporting agencies. Your business and personal credit scores will vary based on the calculation method and credit reporting agency that is used.
There are a few formulas for calculating your credit score, but none of the exact calculations are public. Nonetheless, FICO is relatively transparent about the different factors they assess and how much weight each is given:
Amounts owed (30%): The relative size of your current debt and the ratio of your current debt to your available credit.
Length of credit history (15%): How long your credit accounts have been established (including the age of your oldest account, the age of your newest account and the average age of all your accounts), how long certain credit accounts have been established and how long it has been since you used certain accounts.
New credit (10%): How many new accounts you have opened recently.
Credit mix (10%): How many different types of credit accounts you have, such credit cards, retail accounts, installment loans, finance company accounts and mortgage loans.
What to do if you get rejected
If your application is rejected, you’ll get a letter in the mail that states why Citi turned you down. Depending on the reasons, you may want to use this information to improve your credit score before applying again. Or, if you believe you can provide additional information that might lead to approval of your application, you can call Citi’s reconsideration line to make your case.
ASIAVISION/GETTY IMAGES
If you call the reconsideration line, be prepared to answer questions about your business and present a compelling argument for why Citi should approve your application.
It’s best to avoid applying again until you’ve addressed the reasons Citi gave for rejecting you. But, if you want to apply again or apply for a different card from this issuer, the consensus about applying for Citi credit cards is that you can only apply for one card (personal or business) every eight days, no more than two cards in a 65-day window and no more than one business card in a 90-day window.
How much are American Airlines AAdvantage miles worth?
According to TPG’s March 2026 valuations, American Airlines miles are worth 1.6 cents each, making the current welcome bonus for the Citi / AAdvantage Business World Elite Mastercard worth $1,040. If you use your miles wisely, you can redeem your AA miles for far greater value.
Credit card writer Danyal Ahmed has redeemed his miles for as much as 6.5 cents a piece when booking Qatar Airways business class for 70,000 miles.
If you’re an American Airlines loyalist and a business owner, the Citi / AAdvantage Business World Elite Mastercard is a good choice as you earn bonus miles in business-specific categories and on travel with American Airlines.
Elite like benefits such as priority boarding and free checked bags are enough to help offset the $99 annual fee. If your credit score is at least 730 and your credit profile is good overall, this card and its current welcome offer could be a great value add for your business.
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.