Stephanie Stevens is an associate writer with TPG's credit cards team. She focuses on creating timely credit cards content for TPG readers.
November 10, 2026 • 9 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
Pairing two rewards cards with complementary benefits can help maximize points across different spending categories.
Three combinations are highlighted: one for frequent travelers who dine out, one for everyday rewards, and one for maximizing business expenses.
Each pairing allows you to consolidate rewards into a single balance, making it easier to redeem for travel through transfer partners.
Choosing the right combination depends on your spending habits and whether the combined perks and rewards justify the total cost.
What to consider
Some cards discussed are business products, requiring qualification based on business expenses.
Combined costs can be significant, so ensure your spending aligns with the bonus categories to maximize value.
Selecting cards that earn the same rewards currency streamlines redemption and enhances flexibility.
What you'll miss from the article
Detailed breakdowns of which card pairings best fit specific spending patterns and how to optimize rewards for travel or business.
Generated by AI with support from our editorial team.
When it comes to earning credit card rewards, sometimes two cards really are better than one.
Maybe you have a card that earns bonus points on dining and groceries but falls short on other everyday purchases. Or perhaps you love your card's travel perks but wish it offered better earning rates outside of travel.
That's where pairing cards can come in handy. By choosing two cards with complementary benefits and earning categories, you can get more out of your spending without relying on a single card for everything.
Here are three American Express card combinations worth considering, depending on your spending habits and travel goals.
Frequent travelers who dine out: Amex Platinum and Amex Gold
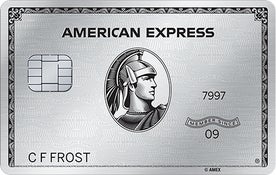
Frequent travelers who want a combination of premium travel benefits and strong everyday earning rates may get the most value from pairing the with the .
5 points per dollar spent on airfare purchased directly with the airlines or through American Express Travel® (on up to $500,000 of airfare purchases per calendar year*)
5 points per dollar spent on prepaid lodging booked with Amex Travel
1 point per dollar spent on all other purchases
The Gold fills an important gap in the Platinum's earning structure. It earns 4 points per dollar spent at restaurants worldwide and at U.S. supermarkets (on up to $50,000 and $25,000 in purchases per calendar year, respectively*).
*Then 1 point per dollar spent for the rest of the year
ISABELLA BOCCASINO/THE POINTS GUY
By using the Platinum for eligible flights and the Gold for dining and groceries, you can earn elevated rewards across several major spending categories while enjoying premium travel benefits. Since both cards earn Membership Rewards points, you can also combine your rewards into one balance to use toward travel through Amex's transfer partners (after linking your accounts online).
The trade-off of this card combination is cost. The Platinum has an $895 annual fee, while the Gold has a $325 annual fee, bringing the combined annual cost to $1,220. For that reason, I'd only recommend this pairing to travelers who can take advantage of the Platinum's benefits and who regularly spend in the Gold's bonus categories.
Best for earning everyday rewards: Blue Business Plus and Gold
If you spend a lot on dining and groceries but want to earn more than 1 point per dollar spent on other eligible purchases, the and could make a great pair.
The Gold earns 4 points per dollar spent at restaurants worldwide (on up to $50,000 in purchases per calendar year*) and at U.S. supermarkets (on up to $25,000 in purchases per calendar year*). It also earns 3 points per dollar spent on flights booked directly with airlines or through amextravel.com or the Amex Travel App™.
Then, use the Blue Business Plus for eligible business purchases that would earn only 1 point per dollar on the Gold. It earns 2 points per dollar spent (on the first $50,000 in eligible purchases each calendar year*) compared with the Gold's standard earning rate of 1 point per dollar spent.
*Then 1 point per dollar spent for the rest of the year
D3SIGN/GETTY IMAGES
Since both cards earn Membership Rewards points, you can build up a single rewards balance to use toward travel through Amex's airline and hotel transfer partners.
The Gold has a $325 annual fee, while the Blue Business Plus has no annual fee, so you won't pay extra to add a flat-rate earning card to the mix.
Just keep in mind that the Blue Business Plus is a business card, so you'll need to qualify to apply. This combination could be especially useful for freelancers and small-business owners with eligible business expenses that don't fall into the Gold's bonus categories.
Best for maximizing rewards on business expenses: Business Gold and Blue Business Plus
If your business spends a lot on things like advertising, software or gas, the and could make a great pair.
The Business Gold earns 4 Membership Rewards points per dollar spent in the two eligible categories where your business spends the most each billing cycle (on up to $150,000 in combined purchases per calendar year*).
*Then 1 point per dollar spent for the rest of the year
Eligible categories include:
Select U.S. advertising
Transit
U.S. electronic goods retailers and software and cloud system providers
U.S. gas stations
U.S. restaurants
U.S. wireless phone service providers
What I like about the Business Gold is that you don't have to choose your bonus categories in advance. Amex automatically determines your top two eligible categories each billing cycle, which is helpful if your business expenses change from month to month.
WESTEND61/GETTY IMAGES
For purchases outside those categories, the Blue Business Plus earns 2 points per dollar spent (on the first $50,000 in eligible purchases each calendar year*). That's double the Business Gold's standard earning rate of 1 point per dollar spent.
*Then 1 point per dollar spent for the rest of the year
For example, you might use the Business Gold for advertising and software expenses, then switch to the Blue Business Plus for other eligible business purchases. Since both cards earn Membership Rewards points, you can build up one balance to use with Amex's airline and hotel transfer partners.
The Business Gold has a $375 annual fee, while the Blue Business Plus has no annual fee. This combination makes the most sense if you spend enough in the Business Gold's bonus categories to justify the annual fee while using the Blue Business Plus to earn more on other purchases.
Before adding another Amex card to your wallet, take a look at where you're spending the most money and what you want to get out of your rewards. The goal is to find a card that fills a gap in your current lineup, rather than one that offers more of the same.
Here are a few things to consider:
Your spending habits: Consider where you spend the most, like on dining, groceries, travel or business expenses. Look for cards that reward the purchases you make most often.
Annual fees: Adding another card means potentially taking on another annual fee. Make sure you'll get enough value from the rewards and benefits to justify the cost.
Your rewards goals: If you're hoping to build up Membership Rewards points for travel, pairing cards that earn the same currency can help you grow your balance faster.
And remember, earning more points isn't worth it if you're spending more than you normally would or carrying a balance and paying interest.
There's no one-size-fits-all approach to choosing the best credit card combination. The key is finding cards that complement each other rather than simply offer more of the same benefits.
Just make sure the additional rewards and benefits are worth the combined annual fees and that you're choosing cards that make sense for your spending habits.
For rates and fees of the Amex Platinum Card, click here. For rates and fees of the Amex Gold Card, click here. For rates and fees of the Amex Business Gold Card, click here. For rates and fees of the Amex Blue Business Plus Card, click here.
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.