Ben Smithson is a senior writer for TPG and is based in London. Originally from Australia and a qualified lawyer with a financial services background, he has almost a decade of experience writing about a broad range of travel and loyalty topics.
March 2, 2026 • 7 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
A travel writer recounts a rental car mishap in Fiji, initially believing a flat tire would not be covered by credit card-provided rental car insurance.
Despite online research suggesting the damage would be excluded, contacting the benefits administrator revealed the incident was covered due to it being sudden impact damage.
The claim was ultimately approved, reimbursing the cost of the replacement tire and highlighting the importance of confirming coverage directly with the provider.
The article emphasizes that even if terms seem to exclude certain incidents, it is worthwhile to file a claim and seek clarification.
What to consider
Primary rental car insurance from premium cards typically requires paying for the entire rental with the card and declining the rental agency's collision coverage.
Coverage terms, exclusions and country limitations vary by card, including maximum rental periods and vehicle value caps.
Always review the specific policy details and contact the benefits administrator for clarification on ambiguous situations.
What you'll miss from the article
A step-by-step account of how to navigate ambiguous rental car insurance claims and why direct communication with benefits administrators can lead to unexpected reimbursements.
Generated by AI with support from our editorial team.
I've always felt pretty confident about understanding my credit card benefits. As someone who writes about credit cards for a living, I assumed I had credit card-provided rental car coverage figured out.
But a recent trip to Fiji left me deflated after I initially discovered a gap in my protection, and I only realized it after I pulled over to the side of the road and turned on the hazard lights.
However, this story has a happy ending and includes a lesson learned.
If you're relying on your premium credit card's primary rental car coverage, even if you've read the fine print, you might actually be covered for more than you first thought.
My experience taught me that even when you think you're not covered, it's worth taking the time to double-check. You might be pleasantly surprised with what you find.
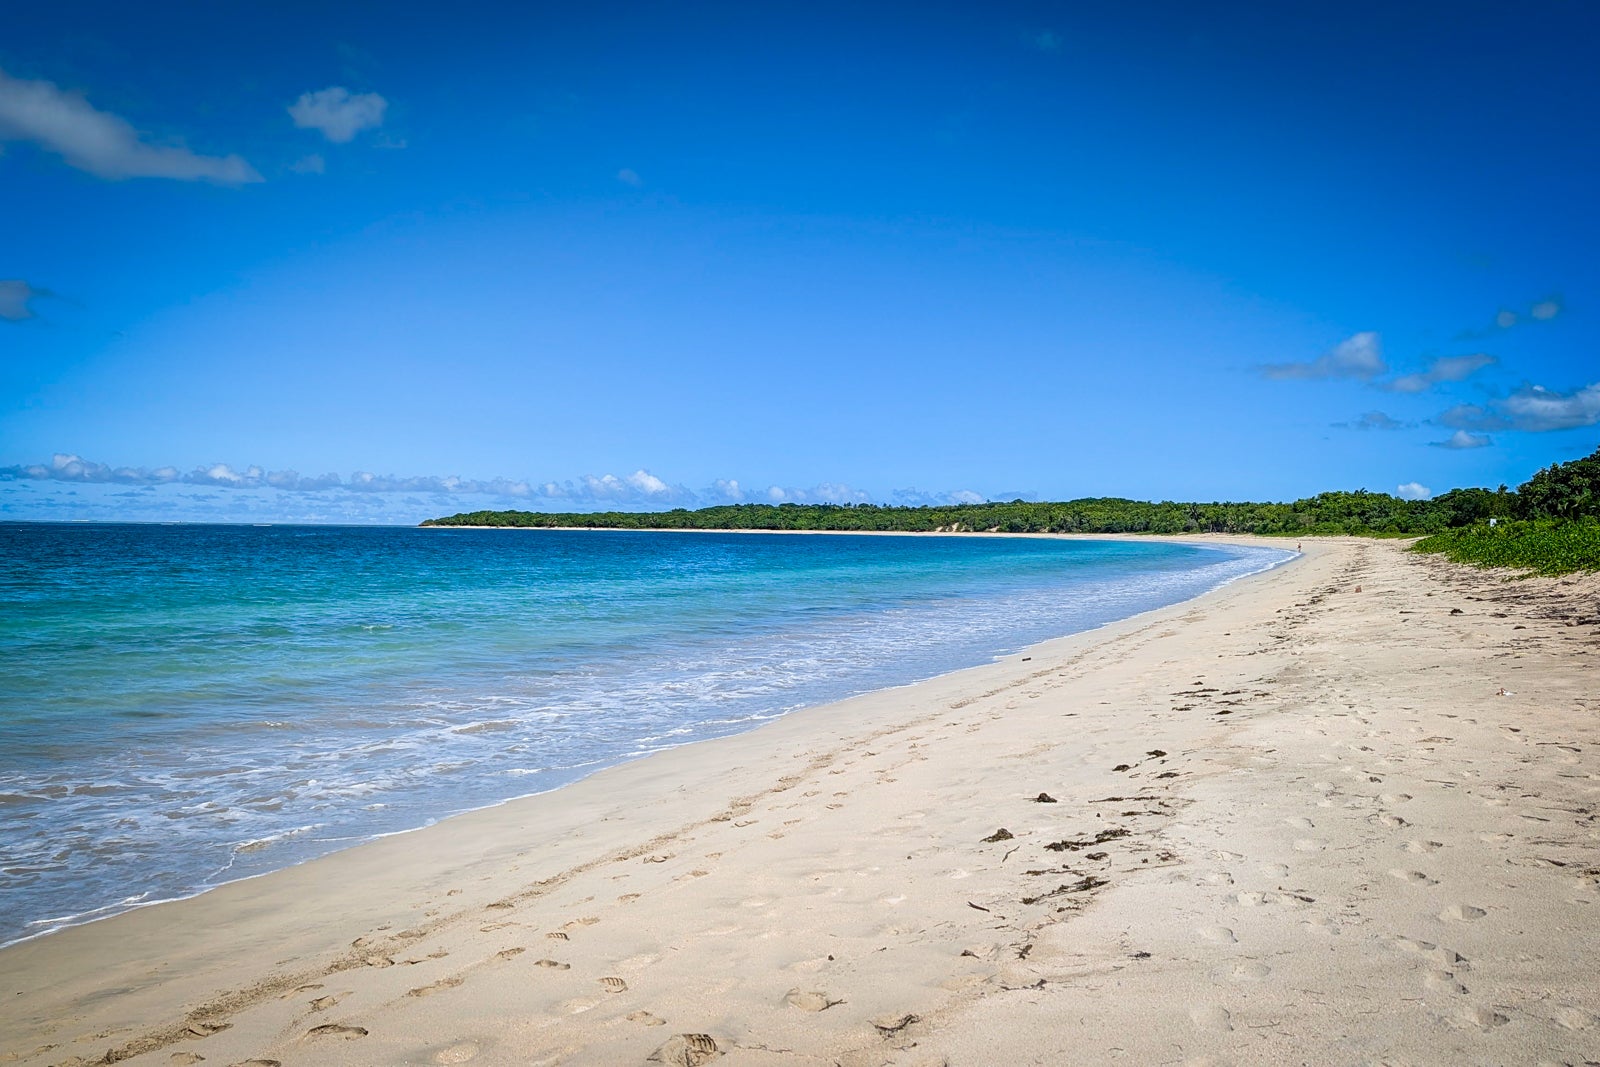
When I landed in Fiji on a recent trip and headed to the rental car counter to collect my vehicle, I did what any responsible points and miles enthusiast would do when asked to swipe my card to pay for the rental: I quickly searched online whether my (see rates and fees) or my Capital One Venture X Rewards Credit Card would provide better rental car coverage while also earning transferable rewards.
Both cards offer primary rental car coverage, which means the credit card's protection kicks in before your personal auto insurance. This is a significant benefit because it can help protect your personal insurance rates from skyrocketing after potential claims.
I only had about 60 seconds to decide — it was already dark, and it had been a long travel day. After comparing the two, my Venture X card seemed to offer slightly more comprehensive coverage, so I used it to pay for my rental.
I felt good about my decision. After all, I had done my due diligence, or so I thought.
BEN SMITHSON/THE POINTS GUY
My misadventure in Fiji
The rental agency staff were friendly but warned as they handed over the keys: Fiji's roads can be rough, and heavy rain in recent days had made potholes harder to spot when filled with water, especially at night.
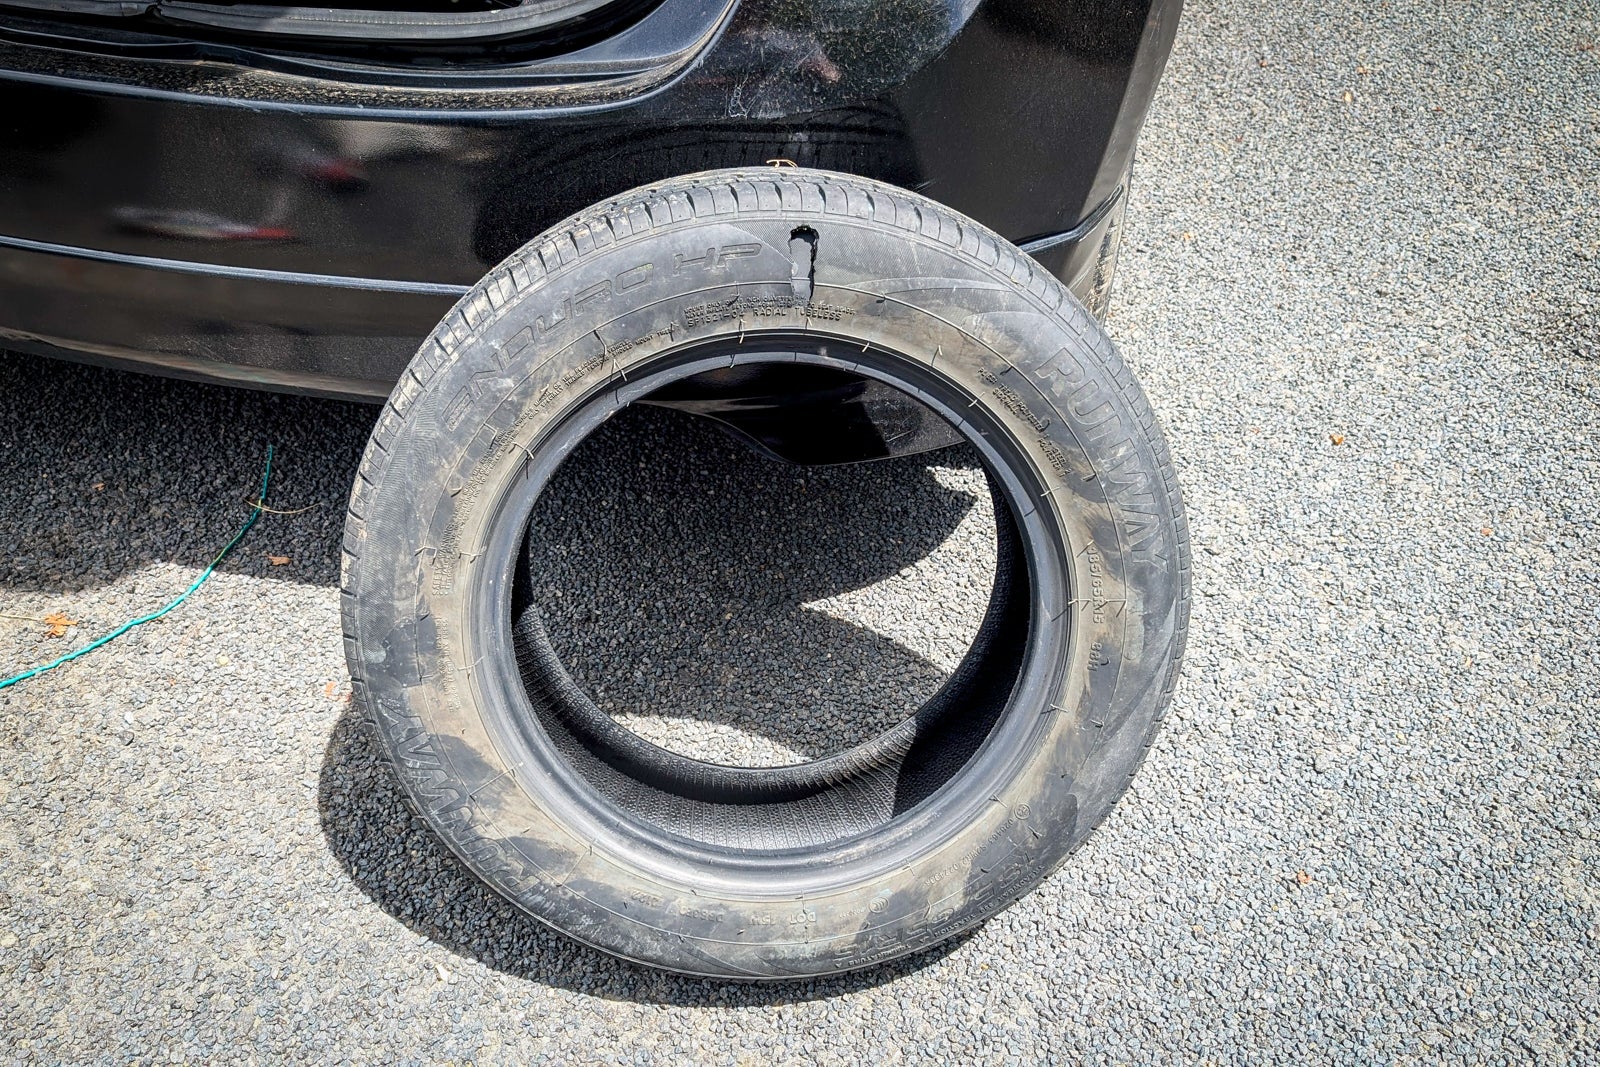
Less than an hour later, I hit a water-filled pothole that shredded my tire on the main highway. The road hazard was invisible beneath the water.
I found myself stranded on a Fijian highway, at night, in the rain, with a tire beyond repair. Fortunately, a friendly local driving by stopped and helped me install the car's spare tire.
I managed to limp the car to a local garage the next day, where I paid out of pocket for a replacement tire. It wasn't cheap, but I consoled myself with the knowledge that my Venture X card would reimburse me. After all, this was exactly the kind of unexpected rental car expense that primary coverage was supposed to handle, right?
BEN SMITHSON/THE POINTS GUY
Checking my provider's coverage
When I returned home, I examined my Venture X's Visa Infinite card benefits policy. There was a lot of fine print, so I also asked Google and ChatGPT for help deciding whether a flat tire was covered by this policy.
Under the "Related instances & losses not covered" section, the policy excludes "wear and tear, gradual deterioration, or mechanical breakdown," and both Google and artificial intelligence chatbots concluded that a punctured tire would be excluded as either wear and tear (if the tire wasn't in great condition to start with) or potential negligent driving (as tires don't just shred themselves and whether I should have spotted the pothole was debatable).
But here's where things got interesting.
I was just about to forget about claiming anything and conclude this as an expensive mistake when I decided to call the policy provider to be absolutely certain.
After speaking with the benefits administrator, I learned that my specific situation (a tire destroyed by impact with a road hazard) may well be covered under the collision damage waiver, and I should file a claim for formal assessment. The key distinction was that this wasn't wear and tear or gradual deterioration. It was sudden damage caused by an impact, similar to what would happen when hitting a curb or another object.
After submitting the necessary paperwork, including the repair bill and proof of payment for the rental on my Venture X, my claim was approved, and I was reimbursed for the full cost of the replacement tire.
Even if you think your damage is excluded (whether because of your understanding of the terms and conditions or because you searched the internet), it's worth contacting your credit card company for a final decision.
The worst the company can say is no.
Top cards with primary car rental insurance
These cards offer primary car rental insurance, provided you use your card to pay for the entire rental. However, each has its own exclusions, so it's important to read and understand the policies before relying on them (and check with the issuing bank if you're unsure).
Chase Sapphire cards: The (see rates and fees), the and the (see rates and fees) each provide primary car rental insurance for rentals in most countries, covering rentals of up to 31 consecutive days. This policy covers theft, damage, valid loss-of-use charges, administrative fees and reasonable towing charges due to covered theft or damage.
Capital One cards: The Capital One Venture X Rewards Credit Card offers an auto rental collision damage waiver that may reimburse you for damages caused by theft or collision up to the actual cash value of your rental vehicle (up to $75,000). You are only eligible for insurance when you rent for up to 15 consecutive days in your country of residence or up to 31 consecutive days in other countries.
Chase Ink Business cards: The (see rates and fees), the , the (see rates and fees) and the (see rates and fees) offer reimbursement when renting for business purposes, including theft and collision damage (up to $60,000) for most rental vehicles with an MSRP of $125,000 or less.
United Airlines cards: The (see rates and fees), the (see rates and fees), the (see rates and fees), the (see rates and fees) and the United Club℠ Business Card offer primary car rental insurance, assuming you decline the rental company’s collision insurance and charge the entire rental cost to your card. This insurance provides reimbursement of up to $60,000 for theft and collision damage for most rental vehicles with an MSRP of $125,000 or less.
The information for the Ink Business Premier and the United Club Business has been collected independently by The Points Guy. The card details on this page have not been reviewed or provided by the card issuer.
Bottom line
My tire troubles in Fiji taught me an important lesson: Don't assume you know what your credit card's rental car coverage includes or excludes. I was convinced my flat tire wouldn't be covered, and I almost didn't bother filing a claim. I'm glad I did my homework and reached out to the benefits administrator. In the end, this saved me hundreds of dollars.
If you do suffer damage that you think isn't covered, consider filing the claim anyway. You might be pleasantly surprised with the outcome, just as I was. This further proves just how valuable travel credit cards can be when you "hit" the road, so to speak.
For Capital One products listed on this page, some of the benefits may be provided by Visa® or Mastercard® and may vary by product. See the respective Guide to Benefits for details, as terms and exclusions apply.
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.