The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Guides
How I use cash back — not just points and miles — to hit my travel goals
Madison Blancaflor is the managing editor for TPG's content operations team. She focuses on helping TPG's broader editorial team bring news, features and advice to readers. She has nearly six years of experience covering the credit cards and travel industries.
January 2, 2020 • 7 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
The article discusses why cash-back credit cards can be a valuable addition to any rewards strategy, even for those who prefer points and miles.
Cash-back rewards are highlighted for their simplicity and flexibility, making them especially appealing for beginners or those seeking straightforward value.
Combining cash-back and travel rewards cards allows for covering a broader range of travel expenses, from flights to on-the-ground costs like dining and entertainment.
The author shares a personal approach of using cash-back rewards to fund everyday travel expenses while leveraging points and miles for major travel bookings.
What to consider
Some offers referenced in the article are no longer available, so current details may differ.
Cash-back rewards provide consistent value regardless of how they are redeemed, unlike points and miles which may offer variable value depending on redemption method.
Strategic use of both cash-back and travel rewards cards can help offset a wide variety of expenses, but maximizing value requires understanding each card's benefit categories.
What you'll miss from the article
A detailed breakdown of how to integrate cash-back and travel rewards cards for a more comprehensive travel funding strategy.
Generated by AI with support from our editorial team.
Update: Some offers mentioned below are no longer available. View the current offers here.
I write about credit cards for a living, so at least twice a day, someone will ask me what card they should get, what sign-up bonuses are the best or which points currencies I favor. Even though I work at The Points Guy (emphasis on "points"), the two cards I recommend most often are actually cash-back cards — the Capital One Savor Rewards Credit Card and the Blue Cash Preferred® Card from American Express. The information for the Capital One Savor Cash Rewards Credit Card has been collected independently by The Points Guy. The card details on this page have not been reviewed or provided by the card issuer.
Let me be clear: I love points and miles and the cards that earn them. I love how they reward you for everyday spending, I love how easy it is to rack up points and I love how people can use them to hit their travel goals, myself included. Traveling and learning about other cultures is my favorite hobby, and my travel credit cards are the only reason I've been able to afford to do that over the past few years. However, I think cash-back credit cards get overlooked when they are actually an invaluable part of any credit card strategy.
Why I love cash-back cards
Even though there is no way to get added value out of cash back like you can with points and miles, I still love cash-back cards and use them frequently.
For starters, cash back is super-simple to earn and use. You don't have to worry about transferring rewards or subpar redemption options — you're getting the same value no matter what you use the cash for. Digging into award charts, learning the ins and outs of certain programs, researching different routes to maximize points spent on a trip ... a lot of beginners can find it overwhelming. Personally, I don't mind going down the rabbit hole of points and miles to find amazing flight redemptions. Like many TPG readers and fellow TPG staffers, the points-and-miles game is a hobby that I genuinely enjoy. But cash back can be an excellent introduction to the rewards game, and that's why these cards are often what I recommend to friends and family.
I also use cash-back cards for another reason. You can get a lot of bang for your buck out of each point or mile when you redeem them for airfare or hotel stays, but you are leaving value on the table if you redeem them for almost anything else. What about the cost of eating out while traveling? Or the cost of on-the-ground transportation and tourist attractions? If you're a young professional and budget traveler like me, the day-to-day expenses of a trip can be a make-or-break factor in whether you can afford to go. That's where my cash-back cards come in.
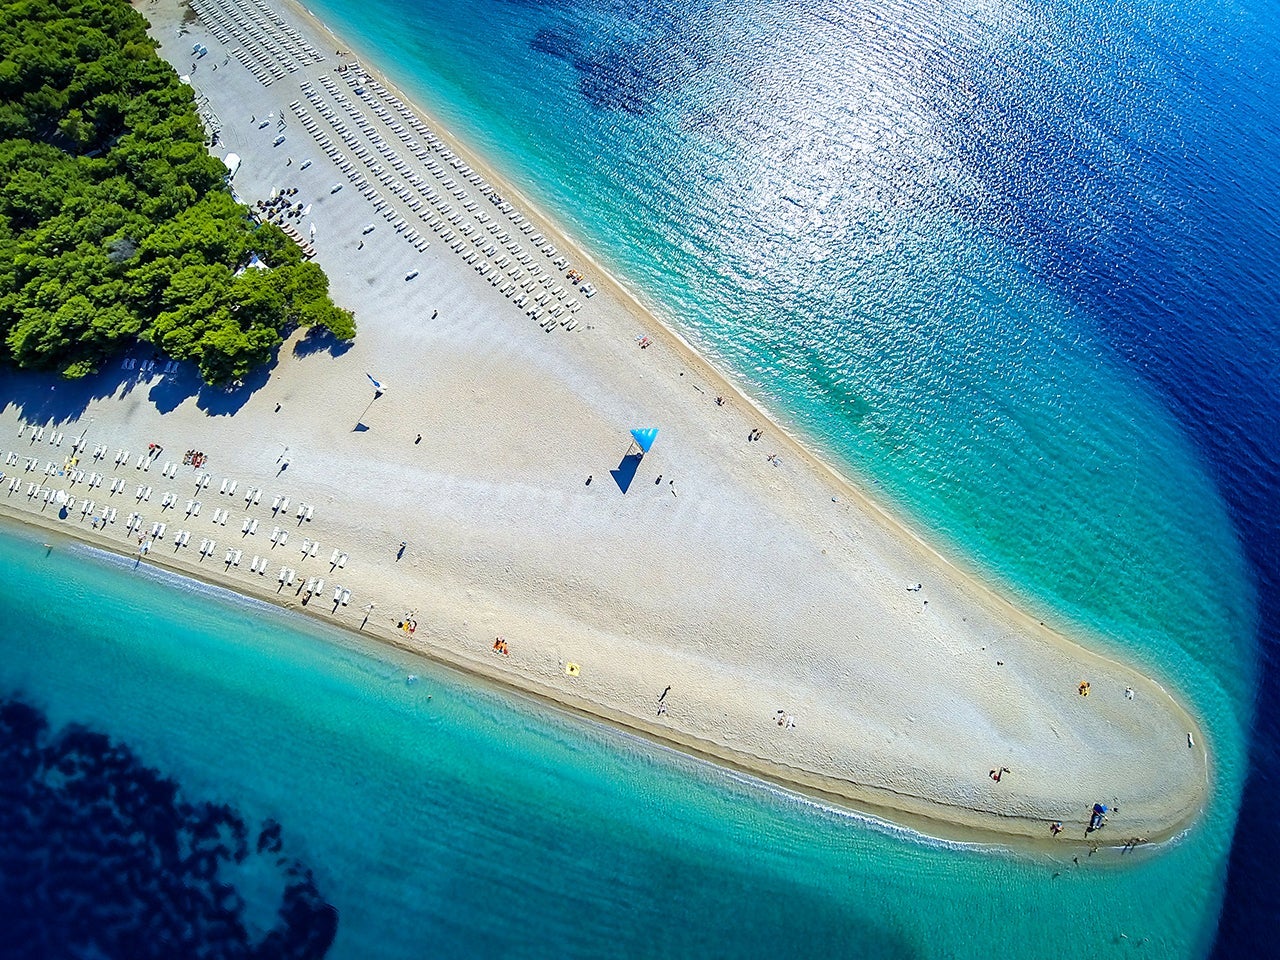
Throughout the year, I'll save up the rewards I earn from my cash back as an unofficial travel fund. Points and miles help me get from point A to point B (and in style too), but my cash-back fund is what I use for amazing dinners and unforgettable experiences while I'm on the ground. For example, I recently took a two-week trip to Croatia with my best friend. I used points from my Chase Sapphire Preferred Card to book my flights there and back, and cash back to pay for my food, transportation costs and my half of our Airbnb stays. I maybe paid $100 out of pocket for 12 days exploring Croatia.
Zlatni rat beach, Bol, Brac island, Dalmatia, was one of my favorite spots when I visited Croatia this past September. (Photo by mbbirdy / Getty Images.)
How I maximize cash back with my points-and-miles cards
I use a combination of cash-back and travel cards and put pretty much all of my spending (outside of rent and my car payment) on my credit cards.
My most frequently-used cards right now are the:
Chase Sapphire Preferred - Earn 3x on dining and 2x on travel
American Express® Gold Card - Earn 4x at restaurants worldwide and U.S. supermarkets (up to $25,000 per calendar year; then 1x) and 3x on flights booked directly with airlines or on amextravel.com
Amex Blue Cash Preferred Card - Earn 6% cash back at U.S. supermarkets (up to $6,000 a year, then 1%) and select U.S. streaming services, 3% on transit and at U.S. gas stations. Cash back is received in the form of Reward Dollars that can be redeemed for statement credits.
Capital One Savor Card - Earn 4% on dining and entertainment and 3% at grocery stores (excluding superstores like Walmart and Target)
Here's how my credit-card strategy plays out and how cash-back cards fit into it:
I use my Chase Sapphire Preferred to pay for ride-shares, hotel and Airbnb stays, and other travel expenses that don't earn me 3x through my Amex Gold. My Amex Gold is used for dining, groceries (at U.S. supermarkets) and airfare. My Blue Cash Preferred is used on my extensive portfolio of streaming service subscriptions and at gas stations. My Capital One Savor is used for all of my entertainment purchases — concerts, movies, sporting events (Go, Carolina Panthers!), bowling alleys, tourist attractions and just about everything in between. (I don't spend much beyond these categories, but anything that doesn't earn bonus rewards gets put on either my Amex Gold or Chase Sapphire Preferred so that I'm at least getting 2 cents of value per point earned.)
This strategy works for me because these cards cover essentially every purchase I make each month and offer benefits that I know I'll use throughout the year. I don't currently have elite status, so my Amex Gold pays for my checked bags when I travel. I host movie nights at my apartment often and the dining credit from my Amex Gold helps me save money and maximize rewards on those nights. I make a point of going to at least one concert, sporting event or musical each month and the Savor also rewards me for that. I'm obsessed with multiple TV shows across multiple streaming services, and my Blue Cash Preferred helps me save on subscription costs. These cards have turned my guilty pleasures into how I fund my travel throughout the year, and the annual fees combined are still less than the fee on one top-tier credit card such as The Platinum Card® from American Express®.
Bottom line
Cash back is a great tool that helps you save money — whether you use that saved money for travel or other financial goals. I completely understand the draw of cards like the Chase Sapphire Reserve and Amex Platinum that earn high-value currencies, but I also believe that cash-back cards deserve a spot in everyone's wallet. When you use both cash back and points-and-miles credit cards, you can save up to pay for every aspect of your travel, both in the air and on the ground.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.