The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Benji Stawski is a former reporter for the site, covering all things points, miles, credit cards, travel and aviation.
April 7, 2020 • 8 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
There are two main types of credit cards: chip-and-signature and chip-and-PIN, with the latter being more common internationally.
Most cards issued in the U.S. default to signature authentication, but some offer PIN capability for use at terminals abroad that require it, such as unmanned kiosks in Europe.
Cards with both authentication methods can automatically switch to PIN when needed, improving usability overseas.
None of the featured cards charge foreign transaction fees, making them suitable for international travel.
What to consider
Some cards require you to manually request or reset a PIN before traveling.
PINs provided for many U.S. cards may only work for cash advances at ATMs, not for purchases.
Certain cards mentioned are no longer available for new applicants, and some offers in the article have expired.
What you'll miss from the article
A detailed comparison of cards with chip-and-PIN capability and practical tips for using payment methods abroad.
Generated by AI with support from our editorial team.
Update: Some offers mentioned below are no longer available. View the current offers here.
There are two types of credit cards in the market today: chip-and-signature cards and chip-and-PIN cards. Plain and simple, chip-and-signature cards use signatures for authentication, while chip-and-PIN cards require a personal identification number.
Most cards issued in the U.S. are chip and signature, but for the rest of the world, chip and PIN is the norm, so it's not uncommon to come across payment terminals that only accept PIN cards when traveling internationally. For instance, most unmanned kiosks in Europe, such as ticket machines and gas pumps, are PIN only. To avoid being in a situation where you don't have a usable credit card while abroad, it's a good idea to travel with a card that offers both authentication methods.
In this story, TPG will go over the top cards that offer chip-and-PIN capability. Each of the cards on this list still default to signature as the authentication method, but will automatically switch to PIN for systems that don't accept signatures. Furthermore, none of the cards included have any foreign transaction fees. Note that although many cards come with a PIN, they are typically only for cash advances at ATMs.
The Platinum Card® from American Express
(Photo by Wyatt Smith/The Points Guy)
This card stands out because it offers a generous 5x Membership Rewards points per dollar spent on airfare purchased directly with the airlines or through the Amex Travel portal (starting Jan. 1, 2021, earn 5x points on up to $500,000 on these purchases per calendar year). Plus 5x points on prepaid hotels booked with American Express Travel. You can transfer your points to 19 airline and three hotel partners, plus enjoy a plethora of perks including trip insurance, access to multiple airport lounges, shopping protections, Hilton and Marriott Gold elite status, access to the Fine Hotels & Resorts (FHR) program and more.
Welcome bonus: 80,000 Membership Rewards® Points after you spend $6,000 on purchases on the Card in your first 6 months of Card Membership.
Earning rate: 5x points on airfare and prepaid hotels booked with American Express Travel.; 1x points on everything else.
The Blue Cash Everyday is best suited for beginners in the rewards credit card game. You’re earning cash back on a limited number of categories in exchange for no annual fee (see rates and fees), with no ancillary perks to accompany the card. If you aren’t spending more than a couple hundred dollars on a credit card per month, this card might make sense for you. While not considered a student credit card, it could help students and young professionals who already have credit history continue to build their credit profile while earning modest rewards.
Welcome bonus: Earn a $200 statement credit after you spend $2,000 in purchases on your new card within the first six months of card membership.
Earning rate: 3% cash back at U.S. supermarkets, U.S. gas stations and U.S. online retail purchases on up to $6,000 per calendar year in purchases for each category (then 1%), and 1% cash back on other purchases.
Similar to Barclays, all Bank of America credit cards have PIN capability. However, you must manually request a PIN through your online account or by calling the number on the back of your card. You'll get the most value from the Bank of America® Premium Rewards® credit card if you're a part of the Bank of America Preferred Rewards program, as customers get a 25%-75% rewards bonus on every purchase.
Welcome bonus: 50,000 bonus points (worth $500) after you make $3,000 in purchases in the first 90 days.
Earning rate: 2x points on travel and dining purchases and 1.5x points on all other purchases.
Annual fee: $95
Read our review of the Bank of America Premium Rewards card.
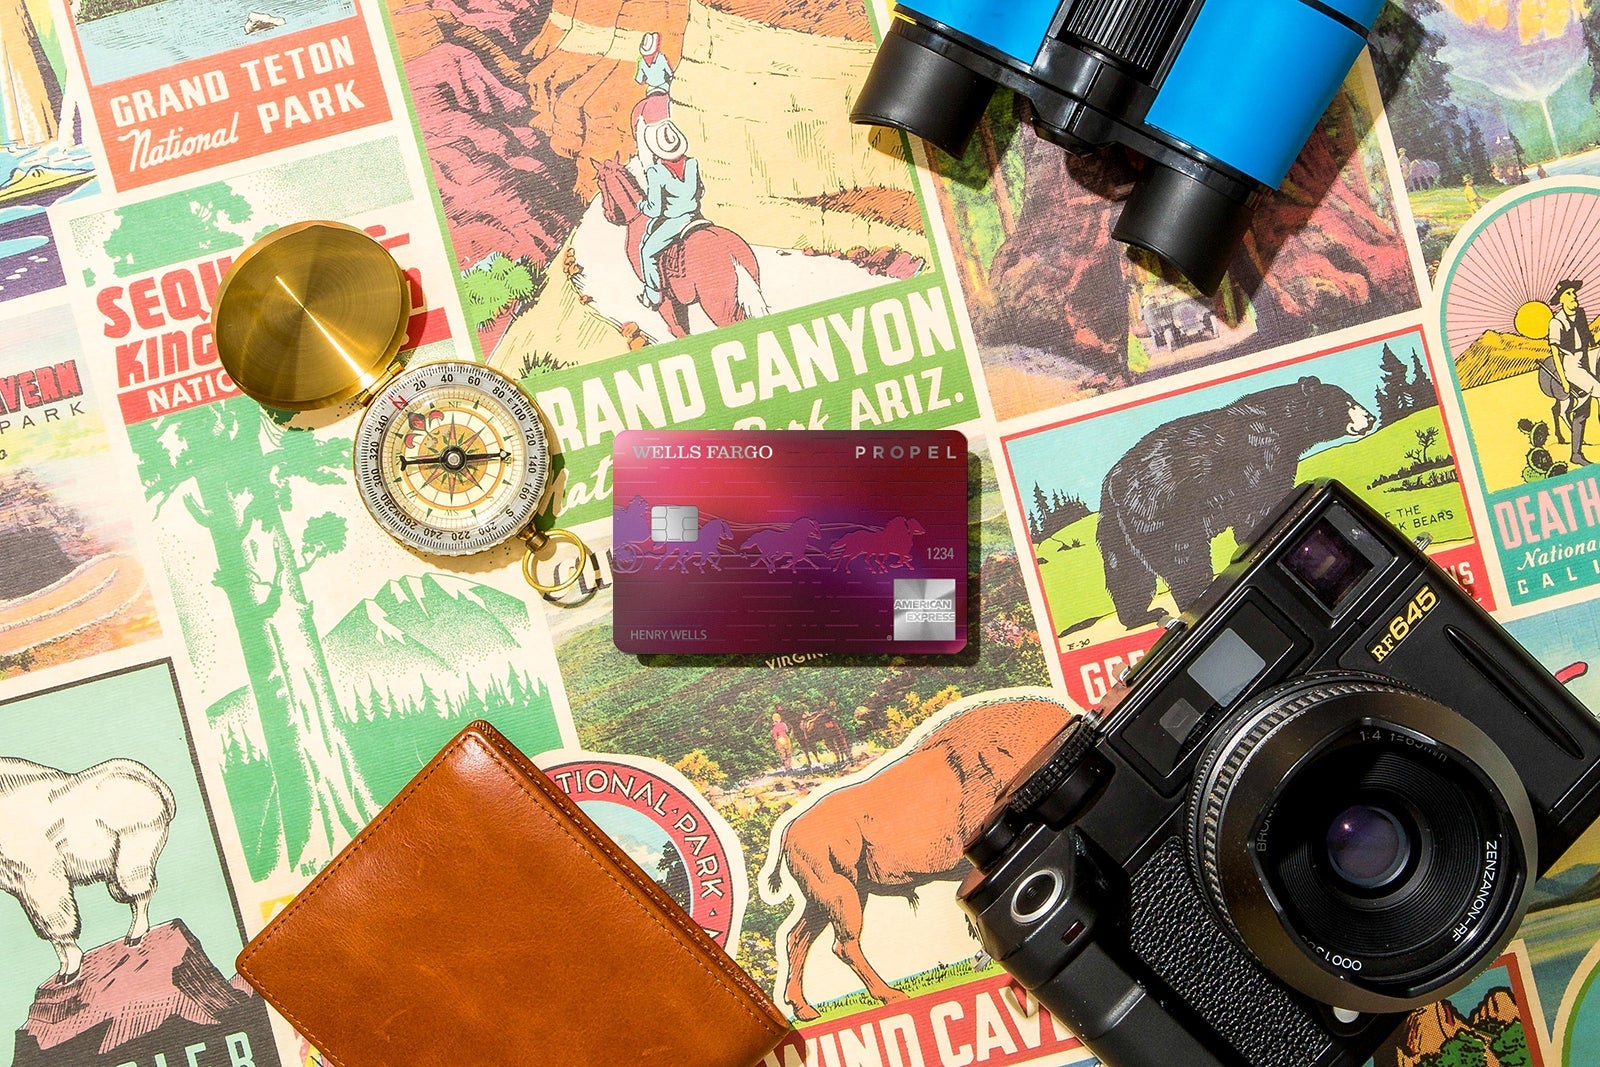
Wells Fargo Propel American Express® card
(Photo by The Points Guy)
The card has chip-and-PIN capability, although the main verification method is by signature. You can call customer support to check or reset your PIN.
Welcome bonus: N/A
Earning rate: 3x points on travel, dining, gas stations and streaming services; 1x points back on everything else.
Annual fee: $0
The Wells Fargo Propel card is no longer available for new applicants. The information for this card has been collected independently by The Points Guy. The card details on this page have not been reviewed or provided by the card issuer.
Read our review of the Wells Fargo Propel card.
JetBlue Plus Card
This card is issued by Barclays, so the PIN feature works the same way as on the Barclaycard Arrival Plus World Elite Mastercard. While abroad, you can earn bonus points on restaurant and grocery store spending.
(Photo by Isabelle Raphael/The Points Guy)
Welcome bonus: 40,000 points (worth $520) after you spend $1,000 in the first 90 days and pay the card's annual fee.
Earning rate: 6x points on JetBlue purchases, 2x points at restaurants and grocery stores and 1x on all other purchases.
It probably goes without saying that the AAdvantage Aviator Red World Elite Mastercard card is best suited for American Airlines flyers. It's also issued by Barclays, so the PIN feature works the same as the issuer's other cards.
Welcome bonus: 60,000 miles (worth $840) after you make a purchase in the first 90 days.
Earning rate: 2x miles on American Airlines purchases and 1x miles on all other purchases.
This card, best for those who fly Hawaii's official airline regularly, is also a Barclays card and has the same PIN feature as the issuer's other cards.
Welcome bonus: 50,000 bonus miles after you spend $2,000 on purchases in the first 90 days.
Earning rate: 3x miles on Hawaiian Airlines purchases, 2x miles on gas, dining and grocery store purchases and 1x miles on all other purchases.
Chip-and-PIN capability doesn't get much attention, but it's an important feature to have when traveling abroad. Barclays and Bank of America currently lead the way in offering PIN capability, but hopefully more issuers will follow suit.
If you're stuck abroad without a chip-and-PIN card, try using a mobile payment app like Apple Pay or Google Pay. This shouldn't be seen as a complete workaround, since not all credit card terminals accept contactless payments, but the ones that do can use your phone for authentication so you shouldn't be asked for a PIN.
For rates and fees of the Amex Platinum Card, please click here. For rates and fees of the Blue Cash Everyday Card, please click here.
Additional reporting by Benét J. Wilson.
Updated on 5/3/21.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.