The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Guides
The gift card trick that helps me maximize my US restaurant credits while I'm abroad
Matt Moffitt is a contributing editor and expert in getting the most out of credit cards and points (he carries at least 25 cards in his wallet at any given time). Originally from Sydney, Australia, he won the Green Card Lottery and lived in Austin, Texas for 10 years before relocating to Spain in 2025.
August 27, 2026 • 9 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
A traveler based abroad found ways to maximize U.S.-only restaurant statement credits without physically dining in the U.S.
By purchasing e-gift cards directly from participating restaurants’ official websites, credits can be triggered remotely and banked for future visits.
Testing with a small gift card purchase first is recommended to ensure the credit posts before committing larger amounts.
This approach is most effective for cards offering larger, less frequent statement credits, while cards with smaller, monthly credits may require more effort for less value.
What to consider
Gift cards must be bought directly from the restaurant’s official site or in person, not from third-party marketplaces, to reliably trigger credits.
Not all participating restaurants sell e-gift cards, and lists of eligible locations can change over time.
Credits are often distributed quarterly or biannually and may not roll over if unused, so timing purchases is important.
What you'll miss from the article
Step-by-step guidance on stacking multiple statement credits and tips for consolidating credits for larger dining experiences.
Generated by AI with support from our editorial team.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
I spent the first half of 2025 traveling through Europe and South America. Then, the month after I got back, I sold my house in Austin and moved to Spain, where I've been based for the past year. In that time, I've only made it back to the U.S. twice.
That has created a problem: between my American Express Platinum Card® and Chase Sapphire Reserve® (see rates and fees), I have up to $700 a year in restaurant credits that only trigger when I pay at a participating restaurant in the U.S.* I wasn't willing to let that value go to waste just because I wasn't going to be dining in the U.S. as often, so I researched a way to keep maximizing those credits from a distance.
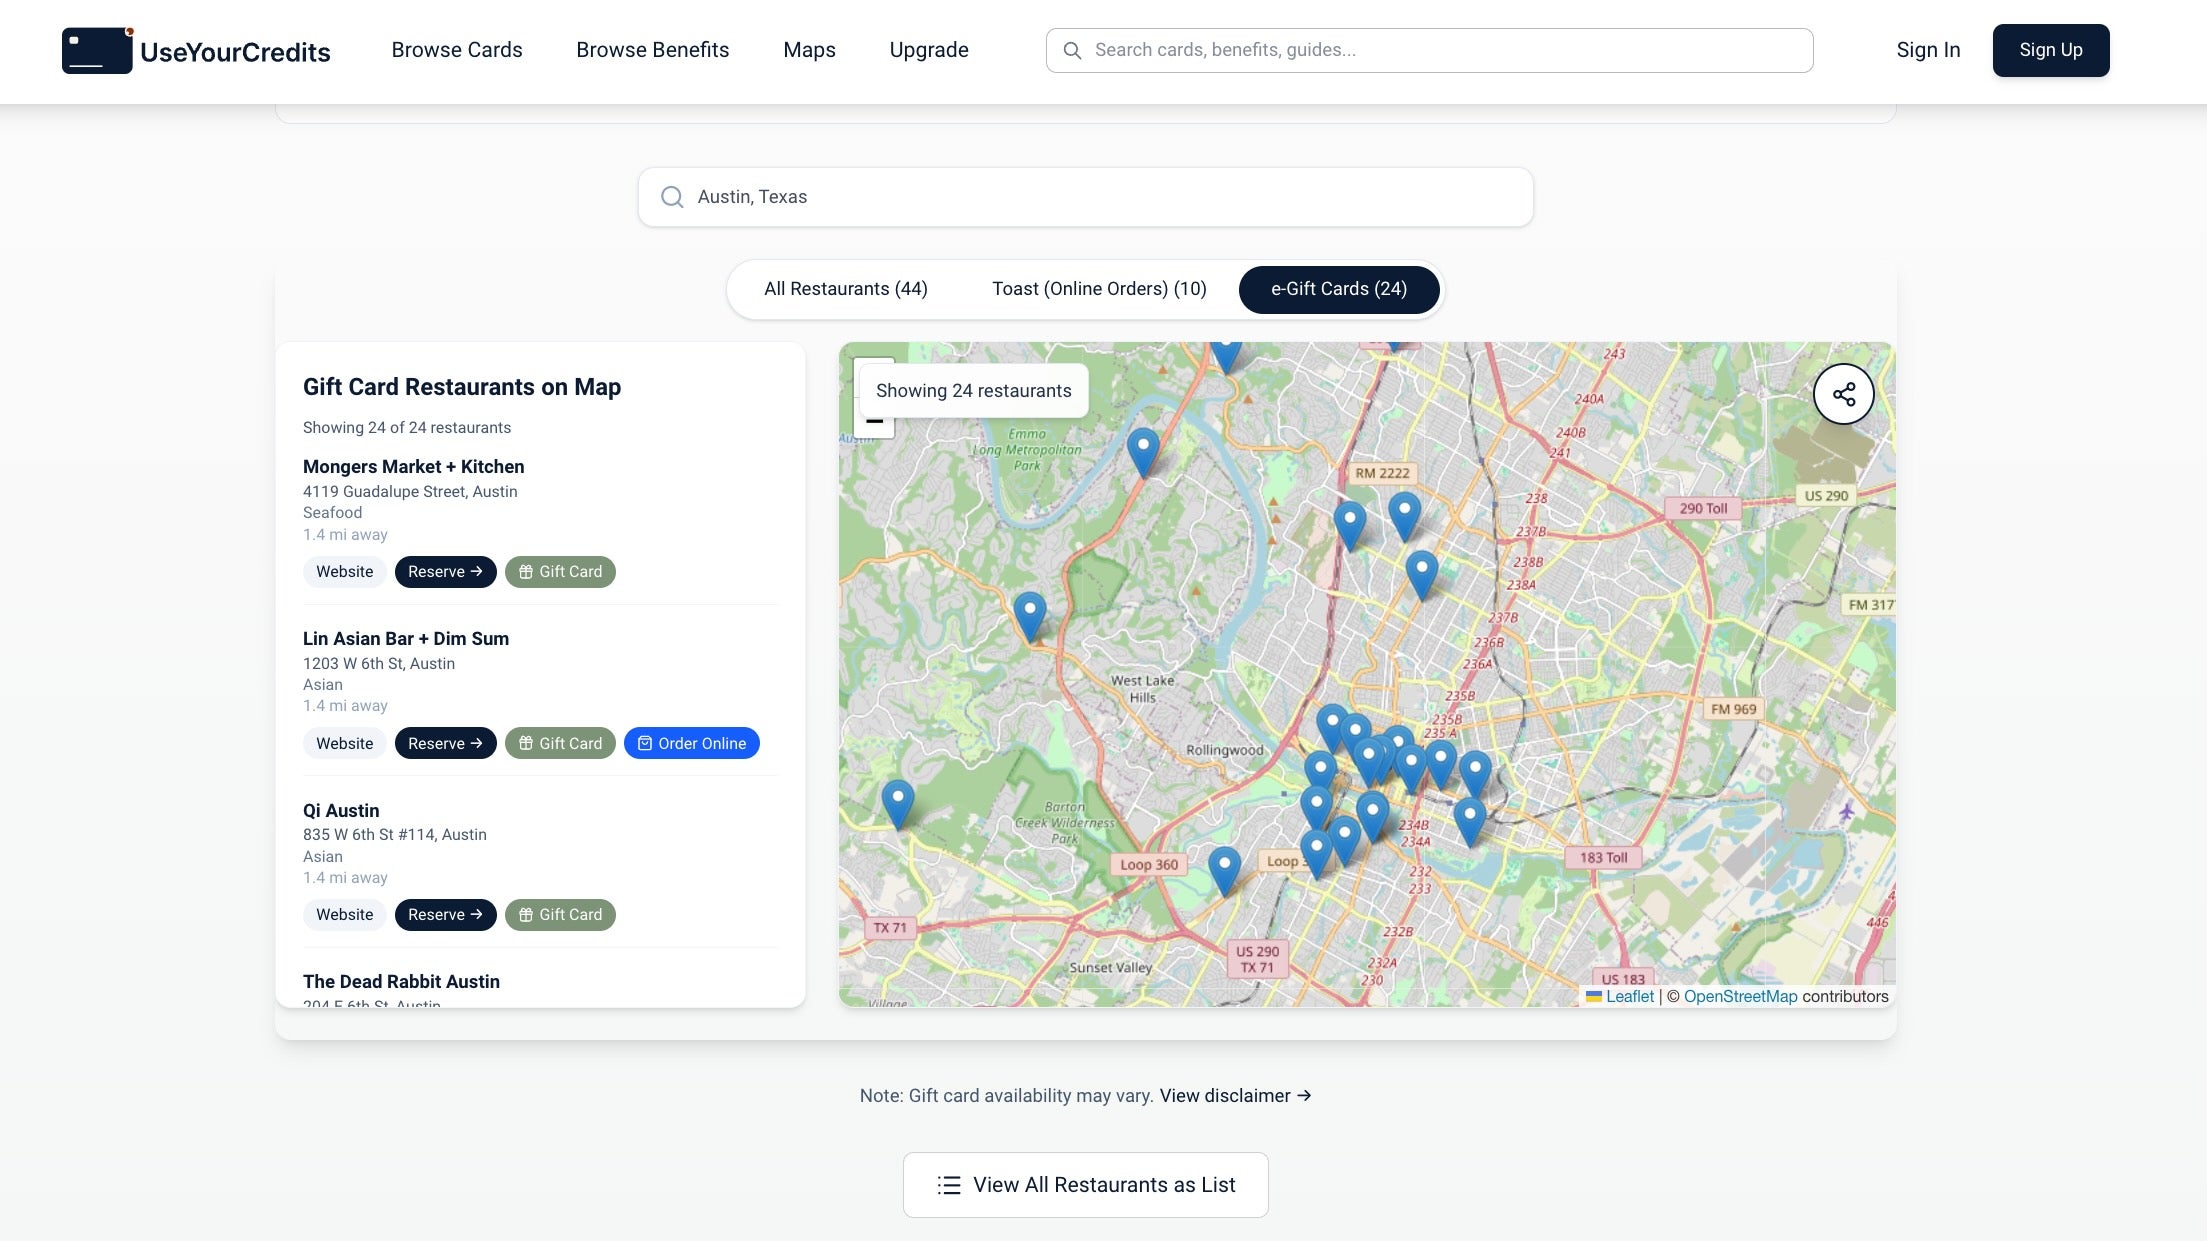
That's when I found UseYourCredits.com, a site that maps out participating restaurants for benefits on cards like these. It's also how I learned that a good chunk of those Resy and OpenTable restaurants sell their own gift cards online. Buy one directly from the restaurant's site, and it often triggers the statement credit just like paying your check would, even if you're thousands of miles away and don't have a reservation.
I've been doing this for about a year now, and it's let me stay on top of these credits every single cycle without needing to be anywhere near the restaurant. Here's how I make it work.
*Receive up to $400 per calendar year in Resy statement credits (distributed as up to $100 per quarter); simply pay with your Amex Platinum at an eligible U.S. Resy restaurant; no reservation required; enrollment required.
Resy's list includes almost 11,000 restaurants nationwide, but only about a third of them sell e-gift cards directly. (This cohort will expand when select Tock restaurants join starting Sept. 15.)
Resy statement credits for use in the U.S. are available on select cards, including the American Express Platinum (up to $100 in statement credits quarterly; enrollment required) and the American Express® Gold Card (up to $50 in statement credits semiannually; enrollment required).
Participating Resy restaurants in Austin. USEYOURCREDITS.COM
Chase's Sapphire Reserve Exclusive Tables list, run through OpenTable, is much smaller (around 400 restaurants), with about a third selling e-gift cards.
One detail that matters: buy the gift card through the restaurant's own website or ordering page, not a generic third-party gift card marketplace. It's usually fine if that page runs on a platform like Toast behind the scenes — what matters is that it's the restaurant's own official channel, not a marketplace that sells cards for dozens of different restaurants.
If a restaurant doesn't sell gift cards online, calling the restaurant directly or buying one in person is also likely to trigger the credit, since the charge usually runs through the restaurant itself.
Why I always test with a small purchase first
I never try to use a full credit at an untested restaurant. I buy the smallest gift card the restaurant offers (usually $5) and wait to see whether the credit posts before I put another dollar toward it.
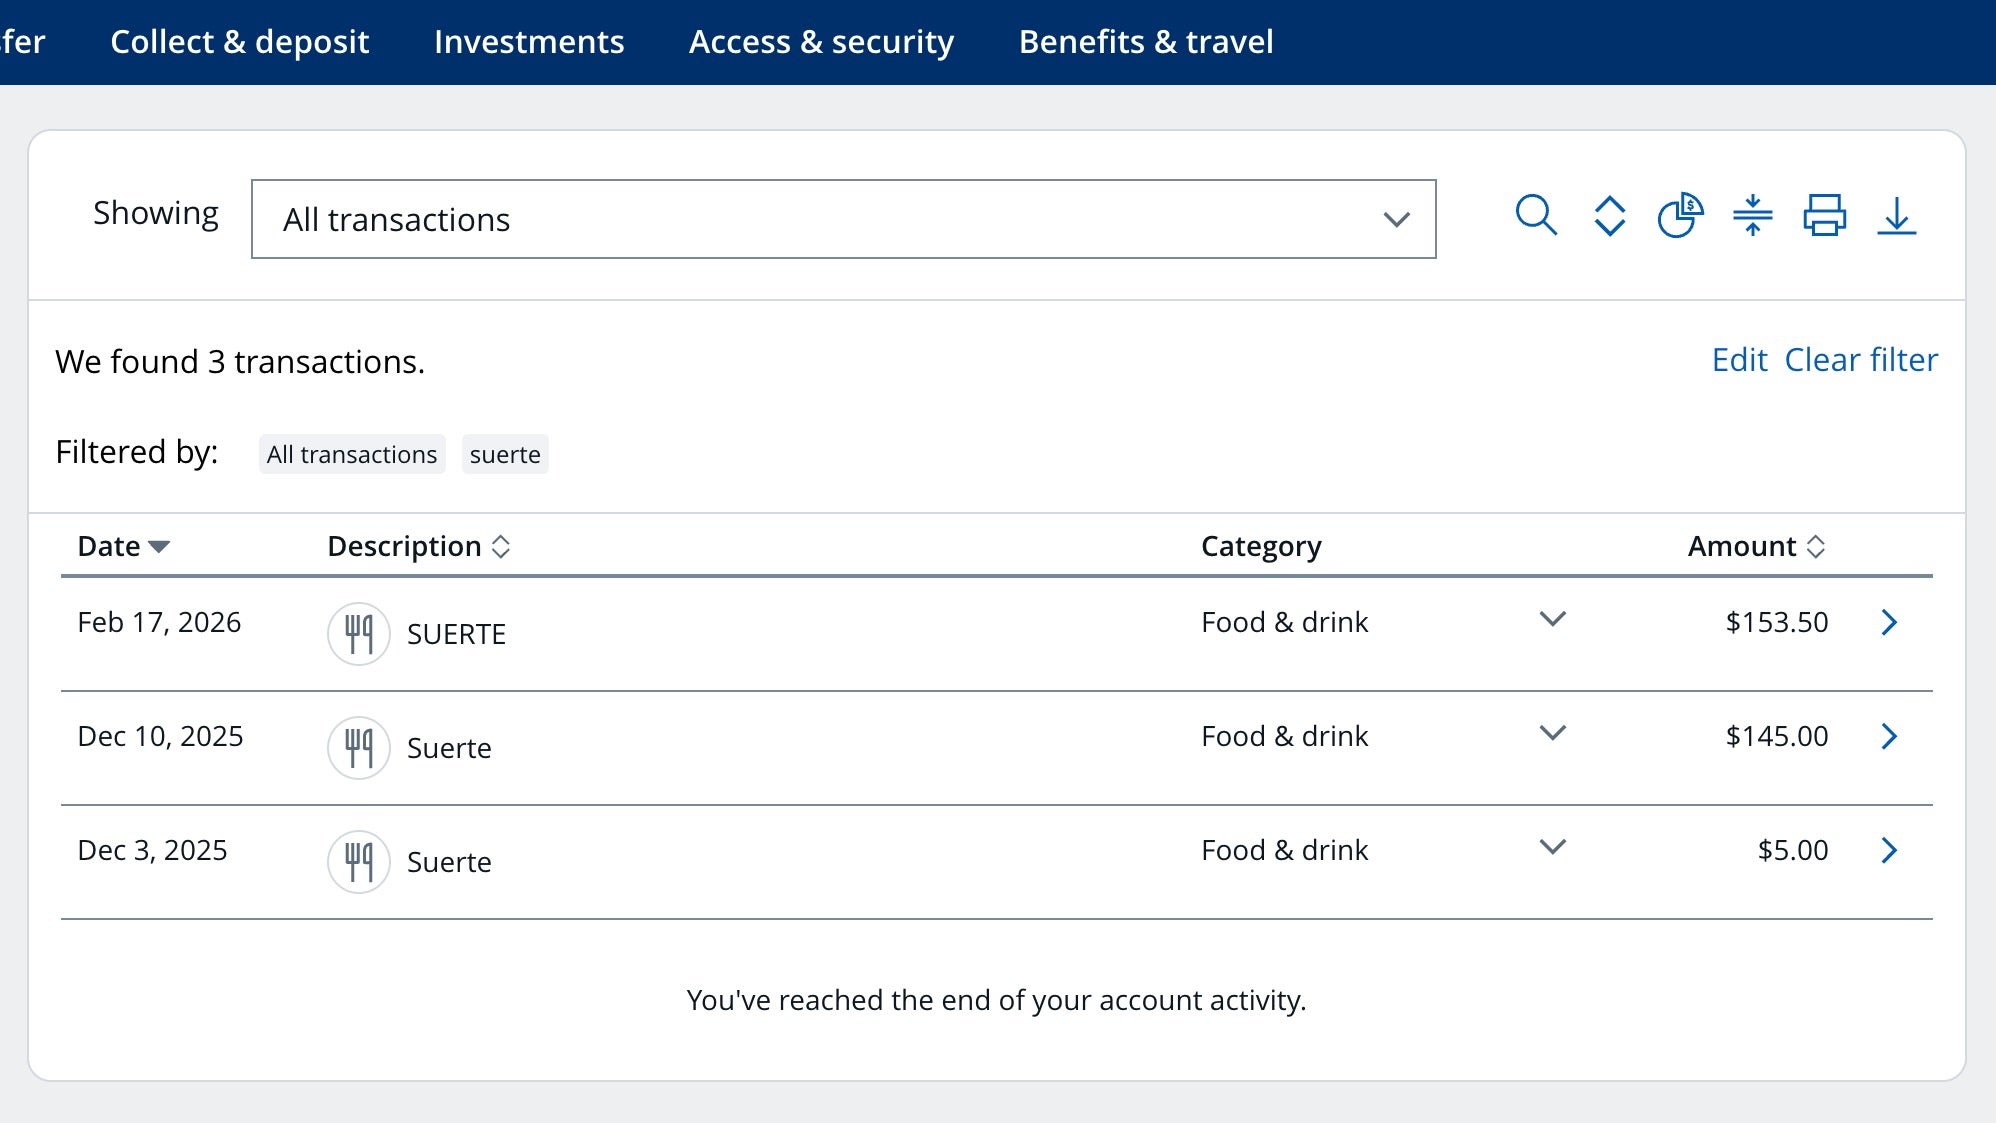
That's exactly what I did at Austin restaurant Suerte last December: a $5 test on the Sapphire Reserve, followed by a $145 reload after the first credit posted.
At nearby Launderette, I tested $25 on my Amex Platinum before reloading another $75. Every time, including for the third gift card I'm currently building up at Fresas (also an Austin staple), the statement credit has posted within two days of purchase.
ERIC ROSEN/THE POINTS GUY
Testing small isn't just caution for caution's sake. Restaurants can change their gift card providers, and issuers can adjust how these transactions get coded. A $5 test protects you from finding out the hard way that $150 didn't trigger anything.
How I stack multiple restaurant credits into one meal
This is where the strategy really pays off.
Chase splits its Sapphire Reserve dining credit into two $150 chunks: one for January through June and another for July through December (unused amounts don't roll over). Last December, I loaded that $150 test-and-reload combo onto a Suerte gift card to bank July-to-December 2025's credit before it disappeared.
Then in February, I flew back to Austin and had dinner in person at Suerte. The bill came to $304 (tip included). I paid $150 of it with the gift card I'd already loaded, and charged the remaining $154 to my physical Sapphire Reserve. That $154 charge triggered a fresh $150 credit for the new January-to-June cycle.
CHASE
Between the banked credit and the newly triggered one, $300 of the $304 total was covered by the card, meaning I paid only $4 out of pocket.
I used a similar approach with my Amex Platinum at Launderette: a $100 gift card that used my Q4 2025 credit (up to $100 in statement credits quarterly for U.S. Resy purchases; enrollment required), then a $100 charge on my physical card during that same February trip, which triggered my Q1 2026 statement credit. Two credit cycles, one meal, $200 covered.
I'm doing it again at Fresas, where I've already used my Q2 statement credit to buy an e-gift card and reload with another $100 for Q3 before my next Austin trip.
You don't need to be living abroad full-time to get value out of this. It's worth considering if:
You're spending an extended stretch outside the U.S., whether that's a year abroad, a six-month posting or a quarter-long trip, and you don't want to watch your credits expire while you're gone.
You want to bank credits toward one bigger night out, a group dinner or a meal you're treating someone to, rather than trying to spend $50-$150 at a time.
You're holding a card with a smaller, more frequent statement credit, like on the Delta SkyMiles® Reserve American Express Card (up to $20 monthly credit for U.S. Resy purchases; enrollment required), and would rather consolidate several months into one gift card than remember to spend at a participating restaurant every single month.
You don't dine out often and are looking for a way to make a high annual fee feel less daunting. The Amex Platinum's $895 annual fee (see ) almost halves once you fully capture its up to $400 annual restaurant credit at U.S. Resy locations; the Sapphire Reserve's annual fee drops to an effective $495 once you factor in its $300 annual Exclusive Tables credit (up to $150 in credits biannually).
Where this strategy falls short
Not every card is worth the effort. I canceled my American Express Gold last year because I couldn't make the math work while living overseas:
Resy statement credit: Up to $50 in semiannual statement credits for U.S. Resy restaurants (enrollment required). You can use the same gift card strategy as with the Platinum and Sapphire Reserve cards, but with a much smaller payout relative to the effort.
$10 monthly dining statement credit: Up to $10 in monthly statement credits at select merchants (enrollment required). It's genuinely hard to use from abroad, since eligible merchants are mostly U.S.-based delivery and takeout brands.
Uber Cash: Up to $10 in Uber Cash each month toward U.S. Uber rides and Uber Eats orders when you add your Amex Gold as a payment method and pay with any Amex card. It doesn't work outside the U.S. at all.
Dunkin' statement credit: Requires reloading your Dunkin' app balance for just $7 every single month to maximize at U.S. Dunkin' locations (enrollment required) — a lot of upkeep for a small return.
That's a lot of small, frequent maintenance for a card with a $325 annual fee (see ).
Compare that to the Platinum's statement credit (up to $100 in statement credits quarterly for U.S. Resy purchases; enrollment required) or the Sapphire Reserve's twice-yearly $150 credits, both of which only need one or two gift card top-ups a year, and it's clear why the larger, less frequent statement credits are easier to justify chasing.
If you'd rather skip the gift card step entirely, the Marriott Bonvoy Brilliant® American Express® Card — which carries a $650 annual fee (see ) — offers a simpler alternative: up to $25 per month in statement credits worldwide at any restaurant that accepts Amex.
It explicitly excludes gift card purchases, so there's no work-around, just the plain requirement that you remember to use it when you're actually eating out. Less to gain but also less friction.
This strategy turned my restaurant credits into real, meaningful savings, including a $4 dinner in Austin that would have otherwise cost $304. It works best on cards with larger, less frequent statement credits, like the Amex Platinum and the Sapphire Reserve, and less well on smaller ones, which is why I stopped bothering with my Amex Gold.
If you've got a restaurant credit sitting unused, it's worth five minutes to check whether that restaurant sells gift cards. Test small, confirm it posts and decide from there whether it's worth building into a monthly, quarterly or twice-yearly habit.
For rates and fees of the Amex Platinum, click .
For rates and fees of the Amex Gold, click .
For rates and fees of the Marriott Bonvoy Brilliant Amex, click .