The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
News
Will non-travel redemption options stick around on travel cards?
Chris was a reporter at The Points Guy, where he covered the intersection of credit card rewards and travel. At TPG, he wrote a broad array of stories ranging from in-depth features and reports to trending travel news as it related to loyalty, card benefits and consumer behavior.
April 15, 2021 • 8 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
The pandemic led to expanded ways to redeem points and miles beyond travel, with several programs allowing redemptions for everyday purchases like groceries and dining at elevated rates.
Some programs have extended these flexible redemption options, offering the same value for non-travel redemptions as for travel, though some are temporary.
Flexibility in redeeming points remains valuable as travel recovers, with some issuers signaling permanent changes while others treat these as limited-time features.
Experts note issuers prefer cardholders use points rather than hoard them, due to accounting and potential devaluations.
What to consider
Some non-travel redemption options are set to expire soon, while others may continue in different forms.
Redemption rates for non-travel categories can match those for travel, but may still be lower than maximizing points with travel partners, per TPG's valuations as of 2021.
Eligibility for enhanced non-travel redemptions may be targeted or limited to select cardholders.
What you'll miss from the article
A detailed comparison of current and potential future non-travel redemption options, including expert insights on program longevity and value trade-offs.
Generated by AI with support from our editorial team.
Update: Some offers mentioned below are no longer available. View the current offers here.
In 2020, the pandemic completely reshaped the priorities of credit cardholders who traditionally earned and redeemed points and miles predominately for travel. Suddenly, travel became the last thing on most people's minds as words like sheltering in place and social distancing enter the equation. For many, that meant holding on to your card's award earnings -- or perhaps spending rewards on items that weren't travel-related.
But as we delve deeper into 2021, a top question that many cardholders have is whether we'll continue to see lucrative ways to redeem points and miles outside of travel purchases -- even as travel continues its rebound.
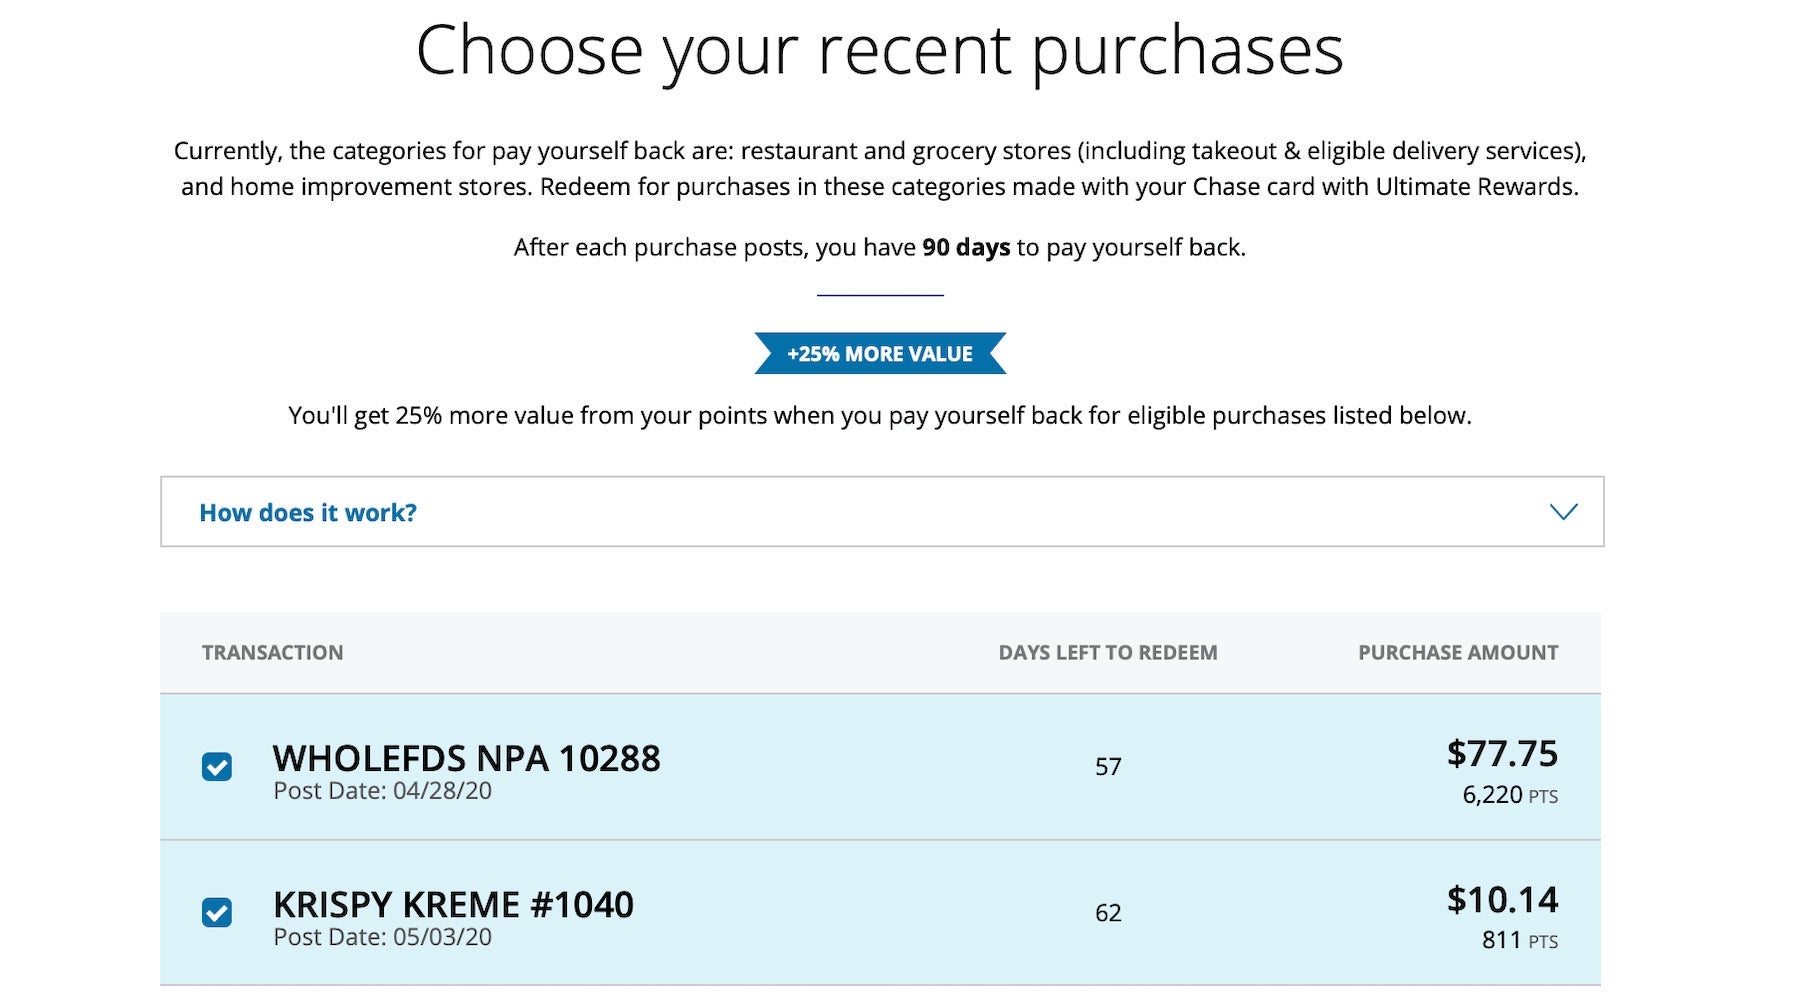
This includes ways to redeem points at elevated rates on everyday categories such as groceries and dining. Chase's Pay Yourself Back program -- letting you use Ultimate Rewards points to offset certain purchases -- won TPG's 2020 Editor's Choice Award as the top innovation in credit card benefits. But will that stick sort of redemption option around or will it become one of those pandemic-era offerings that eventually fade away?
Let's take a closer look at what elevated non-travel redemptions (including dining) on top travel rewards cards might remain longer-term, and what we can look forward to later this year.
Flexible redemption options extended
Both Chase and Capital One have extended the period in which certain cardholders can use their points or miles to offset certain everyday purchases. Most notably, the redemption rate is the same as if you were to use those points or miles on travel purchases.
That's certainly not a coincidence. With many international destinations still restricted and COVID-19 variants flaring up, cardholders are still fairly limited in their travels compared to normal times. Therefore, having the option to use points or miles on other categories of spending remains a valuable benefit for many.
The Chase Pay Yourself Back categories on both the Chase Sapphire Preferred Card and Chase Sapphire Reserve are now valid through Sept. 30, 2021. This redemption option was originally set to expire on April 30, 2021.
Chase Sapphire Reserve customers can redeem points at 1.5 cents apiece, while Chase Sapphire Preferred customers can redeem Ultimate Rewards at 1.25 cents each to offset purchases made at grocery stores, home improvement stores and dining establishments, including take-out and delivery services.
Capital One extension
Through the end of June 30, 2021, you can redeem Capital One miles for purchases made in the past 90 days on food delivery and streaming services on both the Capital One Venture Rewards Credit Card and Capital One VentureOne Rewards Credit Card. This was originally set to expire on April 30, 2021.
The redemption rate is the same as for travel -- 1 cent per point.
... but travel is recovering
Airlines such as Delta are adding new leisure routes as travel rebounds. (Photo by Chris Dong/The Points Guy)
The fact of the matter is that travel demand is recovering, so will issuers still make an effort to encourage you to redeem points on non-travel purchases going forward?
While most issuers will likely shift some of the focus of travel rewards cards back to travel, there's at least one company that may buck the trend. And we actually wouldn't be surprised to see other issuers and cards permanently flex a bit more into the lifestyle realm.
Issuers want you to use your points
Ted Rossman, industry analyst at Bankrate and Creditcards.com (owned by Red Ventures, the same parent company as TPG) says that when it comes to redemptions, issuers have an incentive for you to use your points -- and not have you sit on them.
"It’s not great for issuers when people hoard points, because these show up as liabilities on their books. Since most credit card points don’t expire quickly (if at all), issuers want you to use them."
Additionally, TPG recommends that you don't hoard points, since devaluations can and do happen at any time. Several staffers took advantage of Pay Yourself Back, including TPG's Executive Editorial Director, Scott Mayerowitz, who cashed in a whopping 322,121 Ultimate Rewards points for $4,831.82 in statement credits to cover meals out and groceries.
As Mayerowitz said, "points and miles give savvy travelers unmatched flexibility."
Capital One has already indicated that its non-travel redemptions are only a temporary feature. And during the pandemic, American Express didn't offer any notable elevated redemption offerings using Membership Rewards points, although it did offer temporary credits and some targeted opportunities.
However, Chase has stated that Pay Yourself Back will be around, in some shape or form, for the long haul. The existing categories may change and the elevated redemption options may fluctuate but this benefit seems to be one that isn't likely to disappear in the near term.
Chase is likely aware that Pay Yourself Back even further enhances the Chase "Trifecta," a combination of three powerful cards -- the Chase Sapphire Reserve, Ink Business Preferred Credit Card and Chase Freedom Unlimited.
Rossman added that programs such as Pay Yourself Back "could be a great way to incentivize loyalty and appeal to seasoned travel hackers as well as those who only travel occasionally and mostly prefer cash back."
The only question then is whether the economics work for Chase for the long term.
"It might be a stretch, because the [up to] 50% [redemption] bonus is generous, but it could work if it attracts and retains enough spending. I’m sure Chase would look at spending and customer acquisition and retention data closely," Rossman told TPG.
Other issuers are dabbling
In recent days, we've seen both Amex and Citi further increase their options for non-travel redemptions.
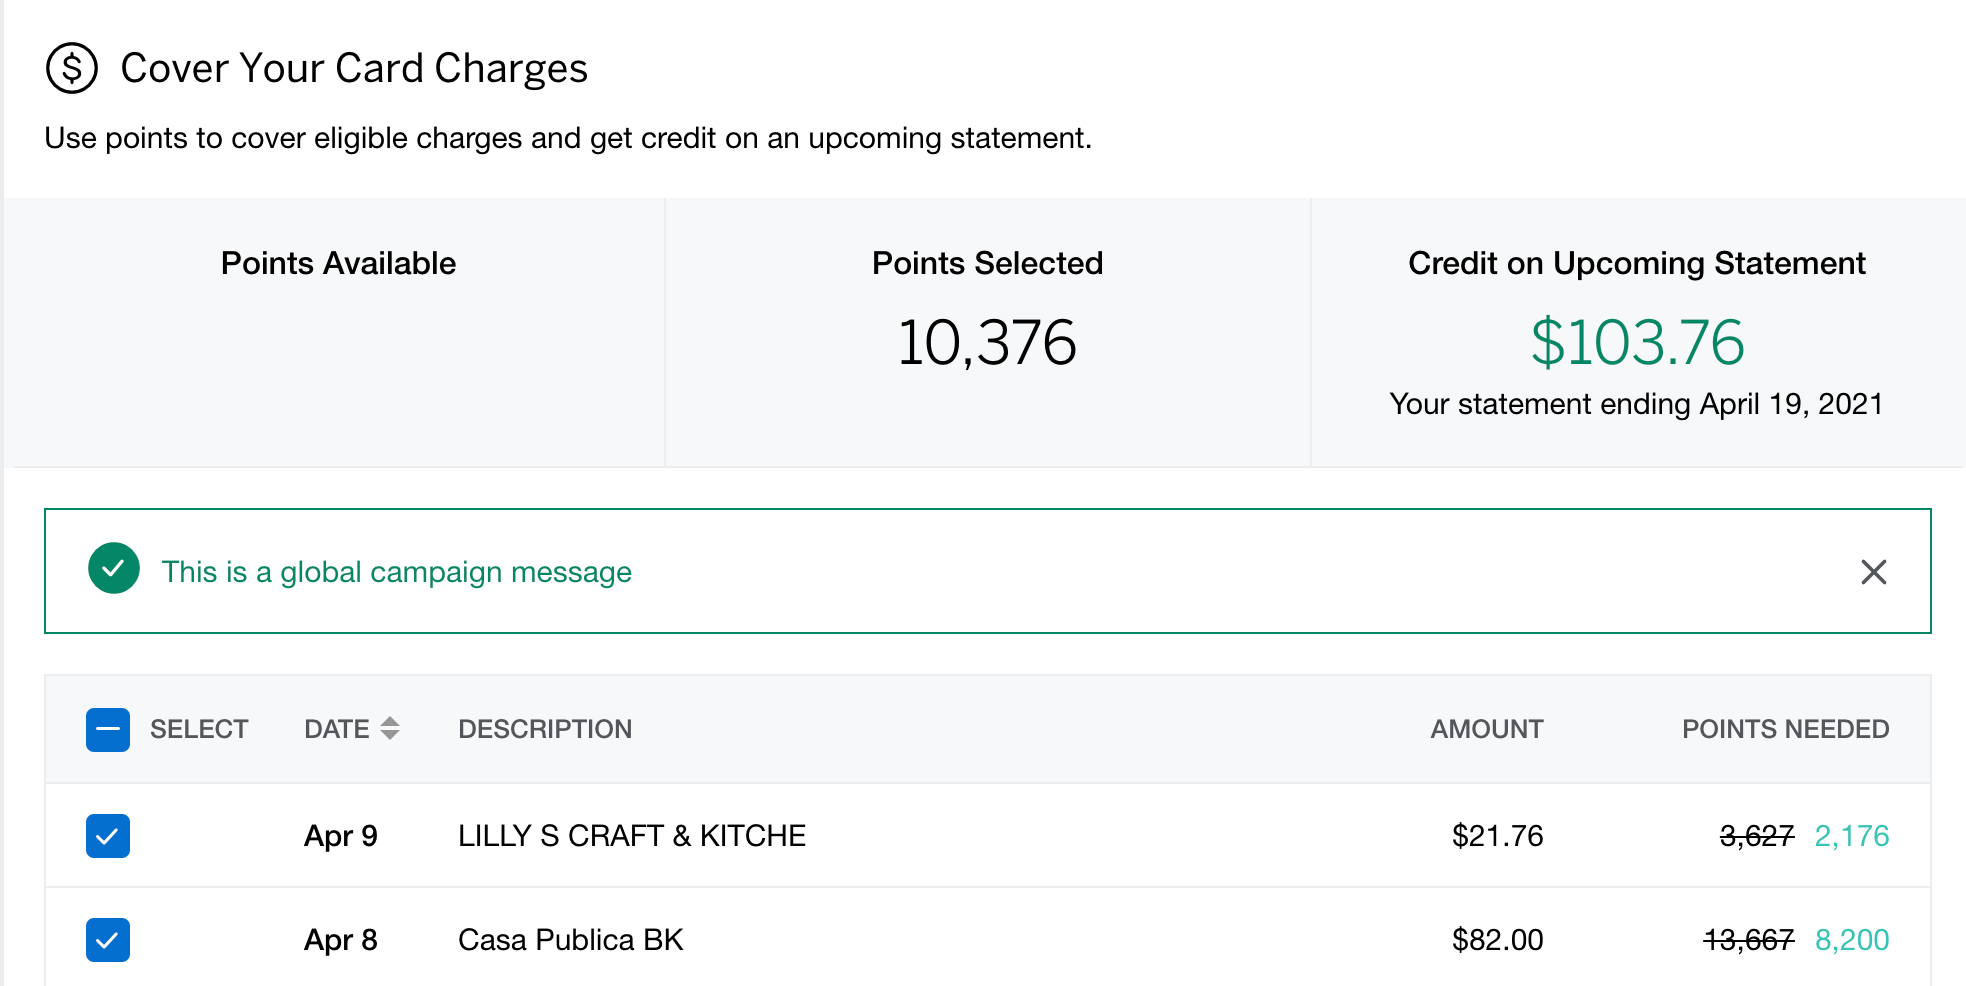
Amex is targeting select cardholders with an offer to use 40% fewer Membership Rewards points to cover everyday charges. Instead of a value of 0.6 cents per point each point is worth 1 cent when redeeming towards your bill in this manner. That's still a full cent less than what TPG values Membership Rewards points when maximized with travel partners, but it makes the redemption more tempting than before.
Meanwhile, Citi appears to have added an option to the Citi Premier® Card to cash out ThankYou points at a 1 cent per point value, similar to the Citi Prestige® Card. Previously, points were worth only 0.5 cents apiece when applied against your statement. Again, this is still less than our own TPG valuation for ThankYou points, at 1.7 cents each, but it's a non-travel redemption that Citi is clearly thinking about.
The information for the Citi Prestige card has been collected independently by The Points Guy. The card details on this page have not been reviewed or provided by the card issuer.
Bottom line
Both Chase and Capital One are continuing their non-travel redemptions programs for at least the next several months beyond the previously stated expiration dates. We've also seen some cards and issuers branch out more into everyday rewards and benefits beyond the traditional travel-heavy focus areas.
Even though transferring credit card points to travel partners may be the most "lucrative" way to use points, more redemption options at increased valuations benefit cardholders. After all, some might argue that flexibility is the current and future king in the credit card rewards landscape.
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.