The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
News
It's worth double-checking: My credit card's rental car coverage paid out for damage I thought was excluded
Ben Smithson is a senior writer for TPG and is based in London. Originally from Australia and a qualified lawyer with a financial services background, he has almost a decade of experience writing about a broad range of travel and loyalty topics.
March 2, 2026 • 7 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
A travel writer recounts a rental car mishap in Fiji, highlighting the complexities of credit card-provided rental car coverage.
Despite initial assumptions that a flat tire from a pothole would not be covered, a call to the benefits administrator led to a successful reimbursement claim.
Primary rental car insurance from premium cards can cover more scenarios than cardholders may realize, especially for sudden, accidental damage.
The article underscores the importance of reviewing policy details and directly confirming coverage with the benefits administrator when in doubt.
What to consider
Coverage terms often exclude wear and tear, gradual deterioration or mechanical breakdown, but sudden impact damage may be treated differently.
Eligibility for primary rental car insurance typically requires paying for the entire rental with the card and declining the rental agency's collision coverage.
Coverage limits, country restrictions and exclusions vary by product, so always consult the policy guide for specifics.
What you'll miss from the article
A step-by-step account of navigating a rental car insurance claim and practical advice for maximizing your card's travel protections.
Generated by AI with support from our editorial team.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
I've always felt pretty confident about understanding my credit card benefits. As someone who writes about credit cards for a living, I assumed I had credit card-provided rental car coverage figured out.
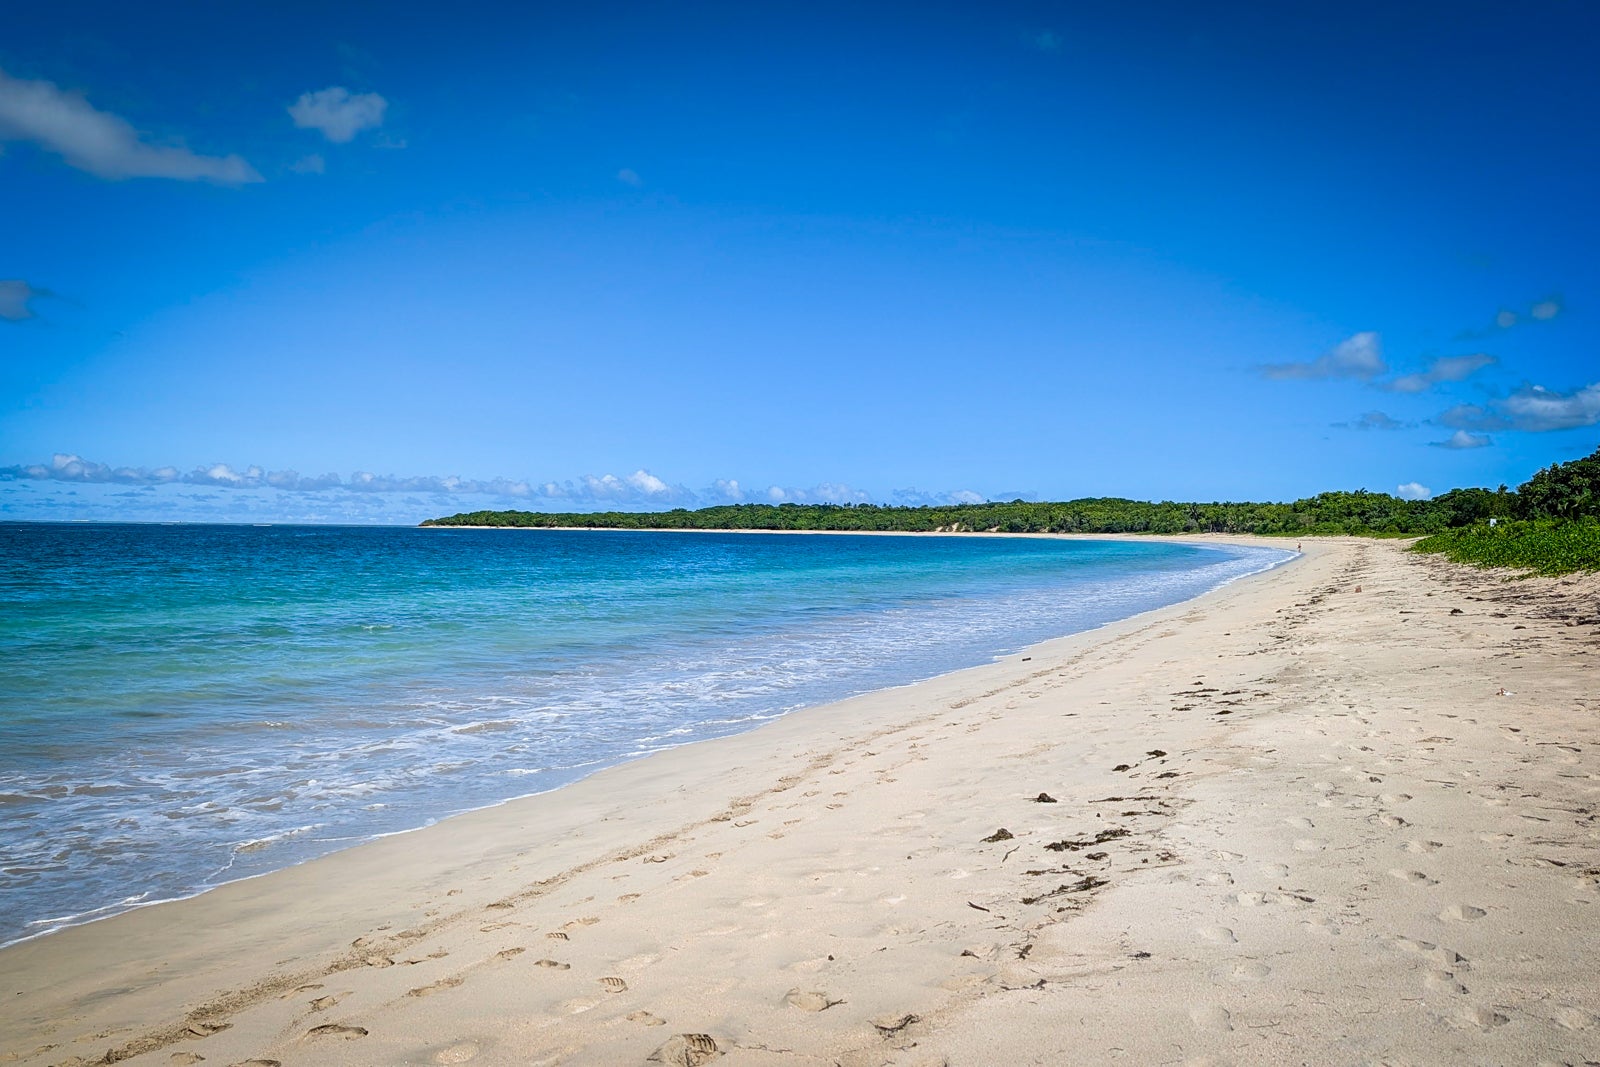
But a recent trip to Fiji left me deflated after I initially discovered a gap in my protection, and I only realized it after I pulled over to the side of the road and turned on the hazard lights.
However, this story has a happy ending and includes a lesson learned.
If you're relying on your premium credit card's primary rental car coverage, even if you've read the fine print, you might actually be covered for more than you first thought.
My experience taught me that even when you think you're not covered, it's worth taking the time to double-check. You might be pleasantly surprised with what you find.
Both cards offer primary rental car coverage, which means the credit card's protection kicks in before your personal auto insurance. This is a significant benefit because it can help protect your personal insurance rates from skyrocketing after potential claims.
I only had about 60 seconds to decide — it was already dark, and it had been a long travel day. After comparing the two, my Venture X card seemed to offer slightly more comprehensive coverage, so I used it to pay for my rental.
I felt good about my decision. After all, I had done my due diligence, or so I thought.
BEN SMITHSON/THE POINTS GUY
My misadventure in Fiji
The rental agency staff were friendly but warned as they handed over the keys: Fiji's roads can be rough, and heavy rain in recent days had made potholes harder to spot when filled with water, especially at night.
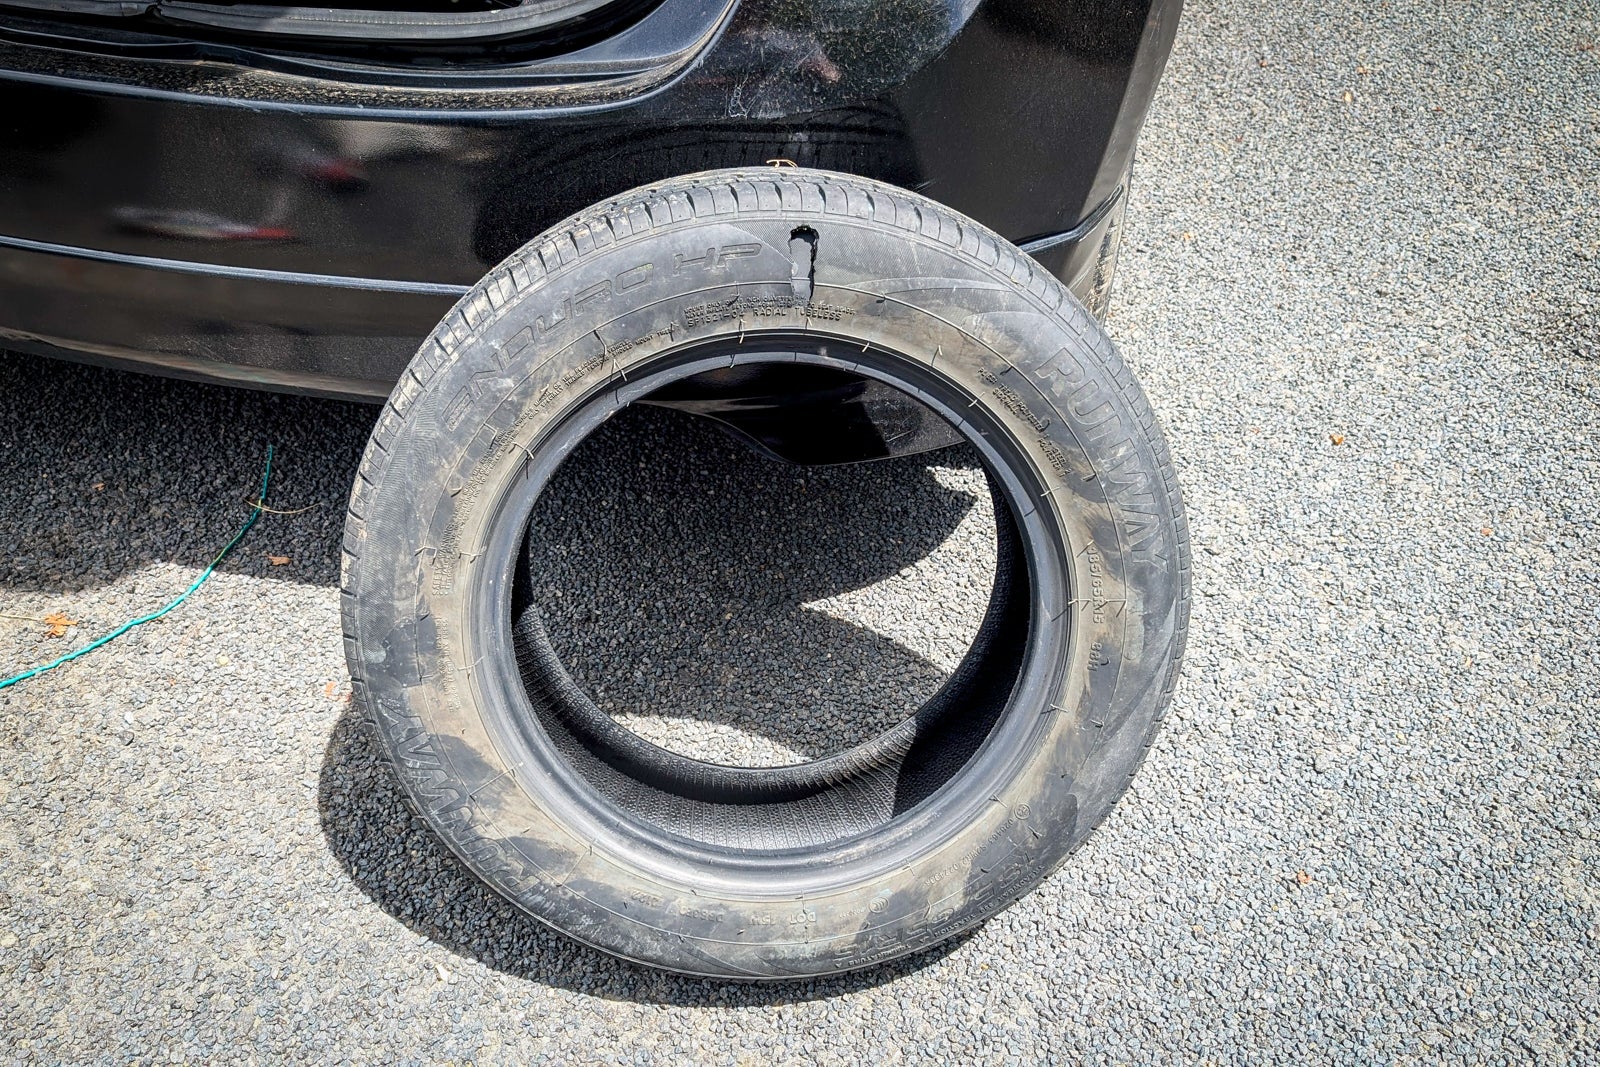
Less than an hour later, I hit a water-filled pothole that shredded my tire on the main highway. The road hazard was invisible beneath the water.
I found myself stranded on a Fijian highway, at night, in the rain, with a tire beyond repair. Fortunately, a friendly local driving by stopped and helped me install the car's spare tire.
I managed to limp the car to a local garage the next day, where I paid out of pocket for a replacement tire. It wasn't cheap, but I consoled myself with the knowledge that my Venture X card would reimburse me. After all, this was exactly the kind of unexpected rental car expense that primary coverage was supposed to handle, right?
BEN SMITHSON/THE POINTS GUY
Checking my provider's coverage
When I returned home, I examined my Venture X's Visa Infinite card benefits policy. There was a lot of fine print, so I also asked Google and ChatGPT for help deciding whether a flat tire was covered by this policy.
Under the "Related instances & losses not covered" section, the policy excludes "wear and tear, gradual deterioration, or mechanical breakdown," and both Google and artificial intelligence chatbots concluded that a punctured tire would be excluded as either wear and tear (if the tire wasn't in great condition to start with) or potential negligent driving (as tires don't just shred themselves and whether I should have spotted the pothole was debatable).
But here's where things got interesting.
I was just about to forget about claiming anything and conclude this as an expensive mistake when I decided to call the policy provider to be absolutely certain.
After speaking with the benefits administrator, I learned that my specific situation (a tire destroyed by impact with a road hazard) may well be covered under the collision damage waiver, and I should file a claim for formal assessment. The key distinction was that this wasn't wear and tear or gradual deterioration. It was sudden damage caused by an impact, similar to what would happen when hitting a curb or another object.
After submitting the necessary paperwork, including the repair bill and proof of payment for the rental on my Venture X, my claim was approved, and I was reimbursed for the full cost of the replacement tire.
Even if you think your damage is excluded (whether because of your understanding of the terms and conditions or because you searched the internet), it's worth contacting your credit card company for a final decision.
The worst the company can say is no.
Top cards with primary car rental insurance
These cards offer primary car rental insurance, provided you use your card to pay for the entire rental. However, each has its own exclusions, so it's important to read and understand the policies before relying on them (and check with the issuing bank if you're unsure).
Chase Sapphire cards: The Chase Sapphire Reserve® (see ), the Chase Sapphire Preferred Card and the Chase Sapphire Reserve for Business℠ (see ) each provide primary car rental insurance for rentals in most countries, covering rentals of up to 31 consecutive days. This policy covers theft, damage, valid loss-of-use charges, administrative fees and reasonable towing charges due to covered theft or damage.
Capital One cards: The Capital One Venture X Rewards Credit Card offers an auto rental collision damage waiver that may reimburse you for damages caused by theft or collision up to the actual cash value of your rental vehicle (up to $75,000). You are only eligible for insurance when you rent for up to 15 consecutive days in your country of residence or up to 31 consecutive days in other countries.
United Airlines cards: The United Quest℠ Card (see ), the United Club℠ Card (see ), the United℠ Business Card (see ), the United℠ Explorer Card (see ) and the United Club℠ Business Card offer primary car rental insurance, assuming you decline the rental company’s collision insurance and charge the entire rental cost to your card. This insurance provides reimbursement of up to $60,000 for theft and collision damage for most rental vehicles with an MSRP of $125,000 or less.
The information for the Ink Business Premier and the United Club Business has been collected independently by The Points Guy. The card details on this page have not been reviewed or provided by the card issuer.
Bottom line
My tire troubles in Fiji taught me an important lesson: Don't assume you know what your credit card's rental car coverage includes or excludes. I was convinced my flat tire wouldn't be covered, and I almost didn't bother filing a claim. I'm glad I did my homework and reached out to the benefits administrator. In the end, this saved me hundreds of dollars.
If you do suffer damage that you think isn't covered, consider filing the claim anyway. You might be pleasantly surprised with the outcome, just as I was. This further proves just how valuable travel credit cards can be when you "hit" the road, so to speak.
For Capital One products listed on this page, some of the benefits may be provided by Visa® or Mastercard® and may vary by product. See the respective Guide to Benefits for details, as terms and exclusions apply.