The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
A TPG editor shares insights into managing a diverse portfolio of 20 credit cards, with a focus on maximizing travel rewards and everyday value.
The editor actively uses seven cards, leveraging specific perks like bonus categories at restaurants and supermarkets, travel protections and lounge access.
Strategic use of different cards for travel bookings and daily expenses helps optimize points and benefits, while minimizing unnecessary fees such as foreign transaction charges.
Tips include tracking spending with spreadsheets, regularly checking accounts for new offers and learning the nuances of each card's benefits.
What to consider
Some offers discussed in the article are no longer available, so current options may differ.
Not all cards are used equally; many are reserved for specific merchants or promotional discounts, while a core set is used for most transactions.
Avoiding foreign transaction fees and maximizing bonus categories are key strategies for frequent travelers.
What you'll miss from the article
Detailed examples of card management routines, favorite redemption stories and practical advice for beginners on building a strong credit card strategy.
Generated by AI with support from our editorial team.
Update: Some offers mentioned below are no longer available. View the current offers here.
Welcome to How I Swipe, a credit card routine series with a focus on strategic credit card spending while at home and on the road. Below is a short list of questions we asked TPG Senior Editor Nick Ewen to answer about how he spends on his credit cards, covering everything from the first card he opened to his go-to card for everyday spend to what cards are in his wallet when he hits the road.
The basics
TPG: What is the first credit card you opened?
NE: A Chicago Cubs MasterCard issued by MBNA. I was (and still am) a big Cubs fan, so it seemed very “cool” to show my fandom on the first card that was my very own (I had been an authorized user on my parents’ cards for years). I still have it, too — since there’s no annual fee and it’s my longest-tenured line of credit.
TPG: How many credit cards do you have?
NE: I currently have 20 open, active accounts — 18 are travel rewards cards, and then I have two store-issued credit cards that I opened years ago to utilize zero-interest promotions on large purchases.
NE: Of the 20 cards, I use seven of them actively (which I define as multiple transactions per monthly billing cycle). The rest are used sporadically when I am making a specific purchase — be it with a given hotel, airline or with a merchant offering a discount or statement credit (e.g. Amex or Chase offer).
NE: I’ve liquidated most of my American Airlines miles, so I’m looking hard at the AAdvantageAviator Red World Elite Mastercard (which is especially appealing given that the welcome bonus only requires a single purchase). I’d also probably jump on the Capital One Venture Rewards Credit Card (which card is currently offering at 75,000 bonus miles when you spend $4,000 on purchases in the first three months from account opening.)
NE: I spend $3,663 — which I have to say I didn’t even realize was this high until I crunched the numbers.
TPG: What is your go-to card for everyday spend?
NE: I focus most of my non-bonus spending on my Blue Business® Plus Credit Card from American Express, which offers 2x Membership Rewards points on every purchase (up to $50,000 in spending each calendar year, then 1x). If a merchant doesn’t take Amex, however, I’ll use my Chase Freedom Unlimited®.
TPG: What card perks are most useful day to day?
NE: For me, especially during the pandemic, the bonus categories on my cards have been absolutely essential to my points-and-miles strategy. Don’t get me wrong; I love perks like lounge access and automatic elite status. However, on a day-to-day basis, earning 4x points at restaurants and supermarkets [4x points at U.S. supermarkets, up to $25,000 per calendar year; then 1x] on my Amex Gold or 5x on my Chase Freedom at rotating merchants each quarter is most valuable to boosting my account balances and setting me up for valuable redemptions … once international travel resumes.
TPG: How many points on average do you earn from credit card spend per month?
NE: This really varies, depending on what I have going on in a month. However, based on a rough estimate of my monthly spend (and earning) across the seven cards I regularly use, I’d say I earn an average of 20,000 points per month.
TPG: What is your favorite card stacking opportunity?
NE: I almost always use my Chase Sapphire Reserve. Not only does it offer 3x Ultimate Rewards points per dollar spent; it also provides terrific travel protections when things go wrong. This came in handy back in June 2019, when a technical problem on our way home from vacation led to a missed connection and forced overnight in Lima, Peru. Instead of waiting for the airline to accommodate us, we booked a nice hotel in the tourist area and enjoyed a nice dinner. Chase covered the hotel, the meal and our Uber rides from and back to the airport the next day. This peace of mind is incredibly valuable.
TPG: What cards do you bring with you on the road?
NE: The major ones are the Sapphire Reserve, the American Express Gold Card and The Platinum Card® from American Express. None of these cards charge foreign transaction fees (see rates & fees - Amex Gold; see rates & fees - Amex Platinum) when I’m outside the country, and I get bonus points on the Sapphire Reserve on travel purchases (including parking, trains, buses, car rentals, and more) and on the Amex Gold on dining at restaurants. Then the Amex Platinum provides extensive lounge access — including Delta SkyClubs (when flying Delta), Priority Pass locations, and Centurion Lounges. (Enrollment required for select benefits.)
TPG: What card perks are most useful when traveling?
NE:Airport lounge access is fantastic, giving me (and my family) a quiet place to escape the craziness of the terminal. I also enjoy the automatic hotel elite status on my cards — especially Diamond status on my Hilton Honors American Express Aspire Card. Finally, the travel protections are GREAT. They’re not “luxury” by any stretch of the imagination, but knowing that I have primary car rental coverage or trip cancellation/interruption coverage when I use my Chase Sapphire Reserve is such a reassuring thing.
The information for the Hilton Aspire Amex card has been collected independently by The Points Guy. The card details on this page have not been reviewed or provided by the card issuer.
TPG: What’s the best points redemption you’ve ever made?
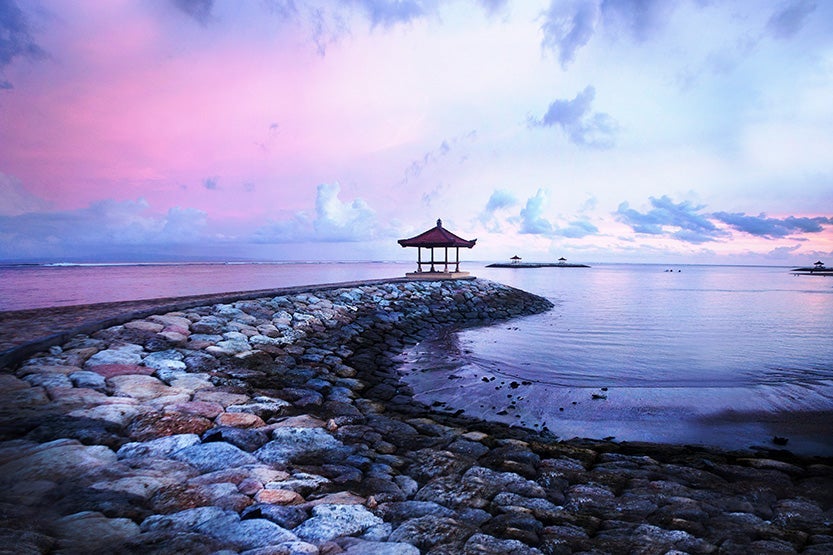
NE: In 2010, my wife and I used 135,000 American Airlines miles apiece for first-class tickets to Bali on a combination of American and Cathay Pacific. Each ticket would’ve cost us $25,000 if we had purchased them outright.
Diamond beach is one of most beautiful and pristine beach in Bali Indonesia
TPG: What’s a rookie credit card mistake you’ve made in the past?
NE: I once used the wrong card for an expensive hotel stay outside the country. Instead of swiping a card with no foreign transaction fees, I used one that charged them! The 2.7% fee was a hard lesson to learn.
TPG: What tricks do you have for managing your card accounts?
NE: I keep an Excel spreadsheet where I project out my monthly card expenses 3-4 months in advance, making sure that my income matches what I’m spending on my cards. I also make a point to log into every one of my active card accounts at least once a week. This not only helps me detect errors; it also helps me identify new offers with bonus points or discounts for select purchases.
TPG: What’s a card perk that doesn’t exist, that you wish did?
NE: I wish there was a transferable credit card currency that allowed me to transfer my points to Alaska Airlines.
TPG: Any credit card pearls of wisdom you want beginners to know?
NE: Start slow, but invest the time to learn more. Managing your credit has a ton of up-side outside of the travel rewards and perks you can use, but it takes time to really maximize all of those benefits. When I first graduated from college, I opened my little no-annual-fee Cubs credit card and thought I had it all figured out. I thought that people who paid annual fees on credit cards were crazy. Little did I know that I’d be incurring thousands of dollars of such fees in the future — but I get incredible value out of all of them thanks to the time and effort I invested in learning the ins and outs of the game.
For rates and fees of the Amex Platinum card, click here. For rates and fees of the Amex Gold card, click here.
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.