The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Guides
Business credit cards vs. charge cards — which is right for you?
Chris Nelson is a credit cards writer for TPG. He specializes in budget travel, hotels, earning elite status through minimal spending and redeeming points for maximum value.
TPG's director of travel content Eric Rosen has used points and miles to visit some of the world's most remote corners, including swimming with whale sharks off Western Australia's Ningaloo Coast, exploring the wilds of Botswana's Okavango Delta and tasting the high-altitude wines of Argentina's Mendoza region.
also contributed to this story
November 1, 2024 • 12 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
Business credit cards and charge cards both help separate personal and business expenses while offering rewards and perks.
Credit cards allow carrying a balance with interest, while charge cards require full payment each month and often have no preset spending limit.
Charge cards may offer more flexibility for large purchases, but are less widely available and typically require stronger credit.
Choosing between the two depends on your business needs, spending habits and ability to pay balances in full.
What to consider
Charge cards generally require very good to excellent credit and are offered by fewer issuers than credit cards.
Carrying a balance is only possible with credit cards; charge cards may charge late fees if not paid in full each month.
Acceptance varies, with some card networks being more widely accepted for business travel.
What you'll miss from the article
A detailed comparison of business credit and charge cards, including pros, cons and which type best fits different business scenarios.
Generated by AI with support from our editorial team.
Update: Some offers mentioned below are no longer available. View the current offers here.
Business credit cards can be a great way to amplify your travel rewards strategy. Most come with generous welcome offers, bonus points on purchases that personal cards do not and other perks to help you meet your travel goals — all while keeping your personal and business expenses separate.
At this point, many rewards cards, both personal and business ones, tend to be credit cards. However, some of the most popular business cards are charge cards. Many people use the terms “credit card” and “charge card” interchangeably. However, the two are very different products.
Understanding how credit cards differ from charge cards is essential for determining which product is right for your business.
We explore business credit cards and charge cards to help you decide which one to choose.
What is a business credit card?
Business credit cards function the same way as personal credit cards. As a business cardholder, you receive a preset credit limit to use to make purchases for your business. As with any credit card, you can't spend over your credit limit. However, because the credit revolves, when you make a payment, you free up available credit for additional purchases.
PIXEL EFFECT/GETTY IMAGES
You have the flexibility to carry a monthly balance but will have to pay interest charges if you do not pay your balance off in full each month.
A business charge card allows you to make purchases and pay expenses. However, unlike a business credit card, you must pay your balance in full every month — you cannot carry it forward. Also, some charge cards have no preset spending limit and adapt to your business's spending patterns.
Before we examine the differences, let’s start with the similarities between credit and charge cards. Both are lines of credit extended to you by a financial institution. You use your personal credit history and score to apply for either type of card. Both will report your activity to the credit bureaus.
You can charge purchases to either card type, and each acts like a short-term loan from your issuer. At the end of your billing cycle, you are expected to repay the amount you borrowed for that month, though it's not mandatory with a credit card (more on that later).
MINISERIES/GETTY IMAGES
Many credit cards and charge cards also offer rewards in the form of cash back, points or miles and other benefits. Both can charge annual fees, late fees and foreign transaction fees.
In short, the two types of cards look very similar but are not quite the same.
There are two major differences between credit cards and charge cards. The first is that credit cards typically let you carry a balance from month to month, whereas charge cards do not. The second is that credit cards tend to have preset spending limits, while most charge cards do not. Now, let’s get into the specifics.
Carrying a balance
In terms of balances and billing cycles, when you use a credit card for purchases, you will receive a statement at the end of each billing month showing your total balance and a minimum amount due, which is generally a small percentage of that balance.
You can pay any amount between the minimum payment and the full balance and carry the rest to the next month.
However, you will accrue interest on the amount that remains unpaid. As long as you pay the minimum each month and don’t exceed your total spending limit, your issuer should keep your account open and consider it in good standing.
LIUBOMYR VORONA/GETTY IMAGES
With a charge card, you must pay off your statement in full each month. If you don't, the issuer will charge a late fee (typically 3% of your balance), which might prevent you from making additional purchases on the card until your balance is paid in full.
Charge cards do not accrue interest since you cannot carry a balance or take advantage of balance transfers to or from your account. However, some charge cards now offer a “pay over time” feature that acts like a credit card, with finance charges based on your time frame.
Because financial institutions do not earn money on interest, they tend to have higher annual and other fees.
Spending limits
When you apply for a credit card, a financial institution assesses your creditworthiness and extends you a line of credit with a limit. This is significant because one of the main factors determining your credit score is your debt-to-credit ratio.
As you make purchases with your card, your debt amount rises against the overall credit limit. This can increase your credit utilization ratio and potentially lower your score. And remember, many small-business owners use their personal credit to guarantee a business credit card. So, the activity on your business credit card can impact your personal credit score.
KSENIYA OVCHINNIKOVA/GETTY IMAGES
By contrast, charge cards do not have preset spending limits. That’s not to say you can charge any amount you want on them at any time, nor that there are no limits whatsoever. Rather, this is intended to give cardholders the flexibility to make large purchases without prior authorization or further credit checks to increase their limit.
Card issuers may limit their cardholders’ spending and adjust it based on purchase habits and changing financial situations. However, because charge cards do not have conventional credit limits, your spending activity doesn't have the same impact on your credit utilization as a regular credit card.
That said, charge card issuers report other factors to credit bureaus, such as credit and payment history, which can impact your credit score.
The right card for you depends on your business needs and spending habits. Generally speaking, it’s easier to apply and get approved for a credit card, so those new to credit should go that route. Charge cards usually require applicants to have very good to excellent credit to be considered.
A credit card can also be easier to get because there are more out there. Only a handful of issuers offer charge cards with no preset spending limit these days, while the major banks all offer business credit cards.
Note that non-Amex cards, such as Visa or Mastercard, tend to be more widely accepted. So, if you travel a lot, having another option in your wallet might be good.
If you know you will need to carry a monthly balance, a credit card will give you the flexibility to do so. Plus, a fixed credit limit might help you better manage your spending.
WONKY CANVAS/GETTY IMAGES
On the other hand, if you can pay off your balance in full each month and want the flexibility to make large purchases without preset limits from time to time, a charge card might be a better choice.
Also, while American Express limits you to a maximum of five open credit cards, it does not appear to limit the number of no preset spending limit cards you can carry. Thus, applying for no preset spending limit cards instead of credit cards could be a good way to continue getting welcome offers and maximizing rewards. Always responsibly, though!
Now that you know how credit and no preset spending limit cards compare, here are a few current business options you might want to consider.
Credit cards
There is no shortage of great business credit cards. Here are just a handful of the top ones.
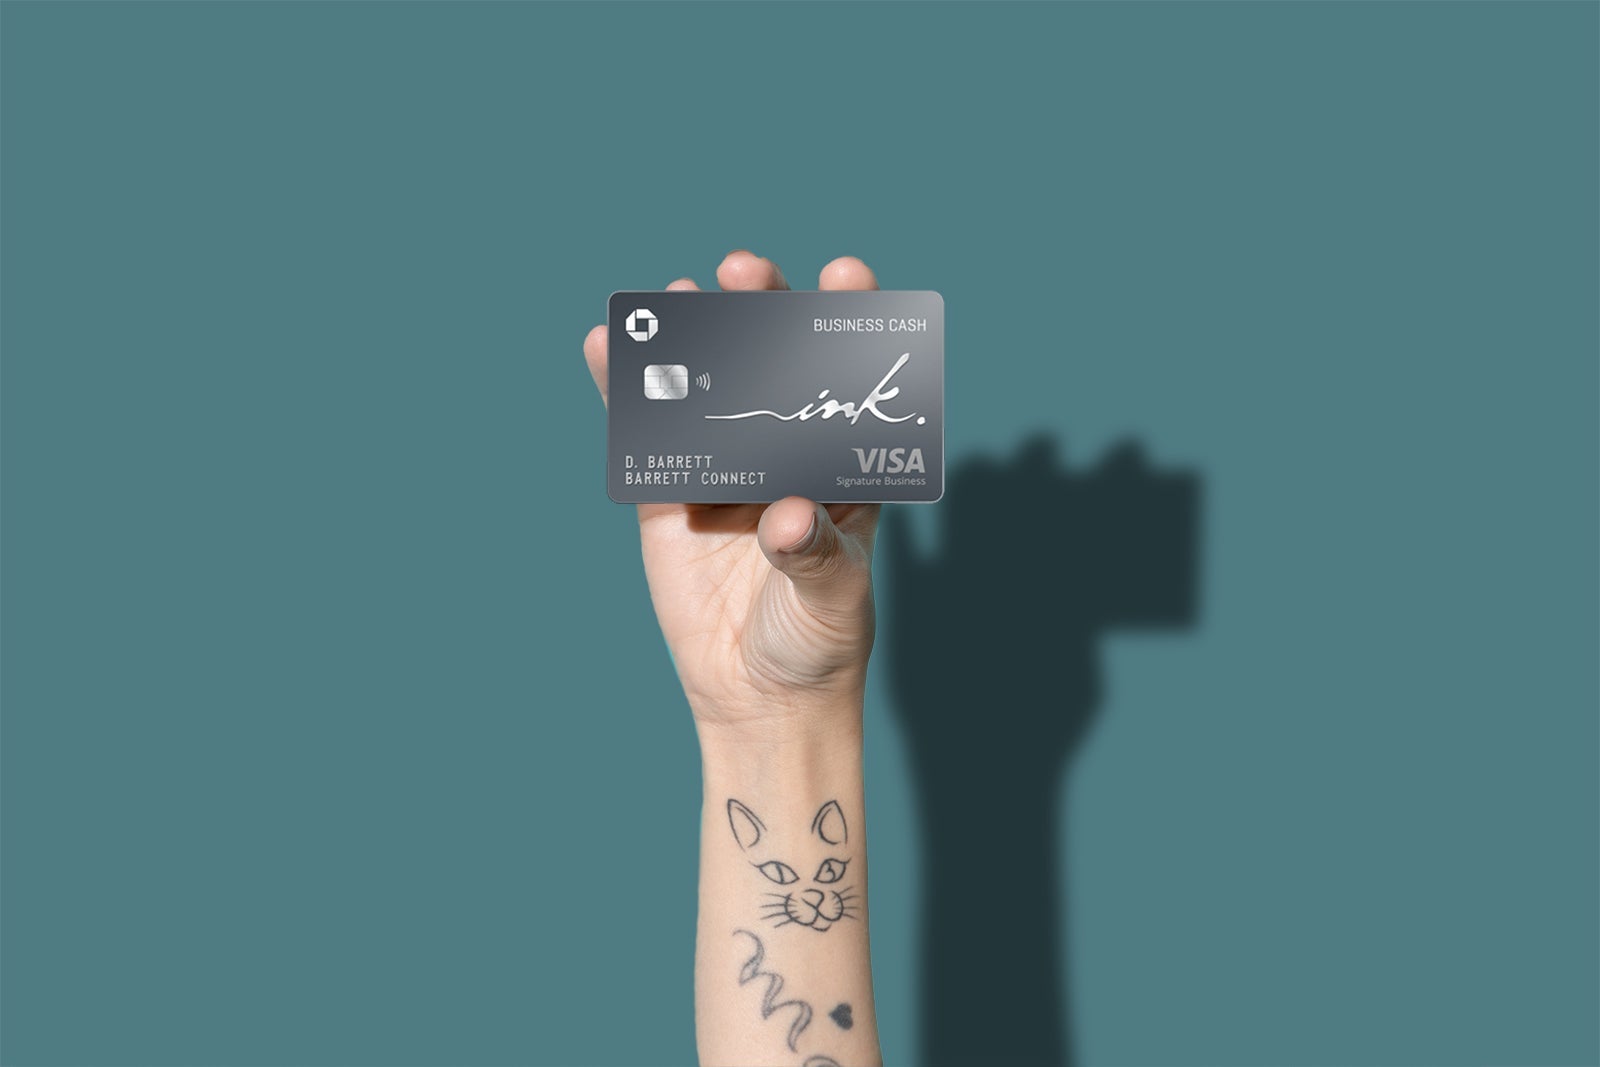
Ink Business Cash® Credit Card (see rates and fees): With this premium business card from Chase, you can earn $750 cash back after spending $6,000 on purchases in the first three months from account opening.
Also, earn 5% cash back on the first $25,000 spent in combined purchases each account anniversary year at office supply stores and on internet, cable and phone services. Get 2% cash back on the first $25,000 spent in combined purchases each account anniversary year at gas stations and restaurants.
Ink Business Preferred® Credit Card (see rates and fees): This card currently offers a sign-up bonus of 100,000 Ultimate Rewards points after spending $8,000 on purchases in the first three months after account opening.
Cardholders earn 3 points per dollar spent on the first $150,000 of combined spending on travel, shipping, social media advertising and internet/cable/phone services each account anniversary year, plus 1 point per dollar spent on all other purchases.
The card also offers cellphone insurance when you use it to pay your (and your employees’) cellphone bill, and primary rental car insurance. You can get employee cards at no additional cost and pay no foreign transaction fees. The annual fee is $95.
Marriott Bonvoy Business® American Express® Card: Right now, new cardmembers can earn 150,000 bonus points and a $125 statement credit after spending $8,000 on purchases in the first six months of card membership.
Earn 6 points per dollar spent at participating Marriott properties; 4 points per dollar spent at restaurants worldwide, U.S. gas stations, U.S. shipping purchases and wireless phone services purchased from U.S. providers; and 2 Marriott Bonvoy Business® American Express® Card points per dollar on all other eligible purchases.
Receive one free award night every year after your account anniversary. The offer is good for stays costing up to 35,000 points. Also, enjoy complimentary Gold Elite status in the new Marriott Rewards program. The card has a $125 annual fee (see rates and fees). To learn more, read our full review of the Marriott Bonvoy Business Amex card.
THE POINTS GUY
Apply here: Marriott Bonvoy Business Amex
Southwest® Rapid Rewards® Performance Business Credit Card (see rates and fees): Earn 80,000 bonus points after you spend $5,000 on purchases in the first three months from account opening.
Earn 4 points per dollar spent on Southwest purchases and earn 2 points per dollar at gas stations and restaurants, earn 2 points per dollar on hotel accommodations booked directly with the hotel, earn 2 points per dollar on local transit and commuting including rideshare and earn 1 point per dollar on all other purchases.
Apply here: Southwest Rapid Rewards Performance Business Credit Card
Charge cards
As mentioned, there are far fewer cards with no preset spending limit, but here is an excellent one worth considering.
Capital One Venture X Business: Earn 150,000 bonus miles after spending $30,000 on purchases within the first three months from account opening.
THE POINTS GUY
Earn unlimited 10 miles per dollar on hotels and rental cards booked through Capital One Business Travel and 2 miles per dollar on all purchases. This card also comes with a $300 annual travel credit that can be used for bookings made through Capital One Business Travel.
Getting a business card can help you maximize your spending and meet your travel goals. However, whether a credit or a charge card is the right choice for you will depend on your spending and payment habits, your credit score and history, and what kinds of purchases you need to make with your card.
Once you understand the differences between the two types of products, though, there are plenty of great choices in each category.
For rates and fees of the Marriott Bonvoy Business American Express Card, please click here.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.