Katie Genter is a digital nomad who has traveled full time since June 2017. She writes and edits stories about points and miles, and loyalty programs, often letting her personal experiences color these stories.
November 9, 2026 • 8 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.
Editorial note: This is a recurring post, regularly updated with new information and offers.
Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
Couples can maximize rewards and benefits by coordinating their credit card strategies, whether managing finances jointly or separately.
Each partner can apply for their own cards, potentially earning separate welcome offers and accessing more perks.
Adding a partner as an authorized user can help share benefits and, in some cases, build credit, but the primary account holder remains responsible for all charges.
Choosing between holding the same cards or complementary cards depends on travel habits, desired perks and the value of shared versus individual benefits.
What to consider
Application approval is based on individual credit history, though accessible household income may be considered in some cases.
Some benefits do not extend to authorized users, and not all issuers allow pooling or transferring rewards between partners.
Coordinating which rewards to earn and redeem is essential, as program rules for combining or transferring points vary.
What you'll miss from the article
Detailed strategies for couples to coordinate earning, redeeming and sharing travel rewards for maximum value.
Generated by AI with support from our editorial team.
Among my friends and family, I see couples manage their finances and credit cards in many different ways. But across all the couples I know, I've found that two people can work together to earn more rewards and enjoy more benefits than they could individually.
So, here are some credit card strategies you should consider if you're part of a couple.
Should couples have separate credit cards or share accounts?
Couples who manage their finances separately will generally want separate credit card accounts. However, even if you manage your finances separately, you may want one or two cards you both use for shared expenses.
Likewise, even if you generally manage your finances jointly, having a few separate cards can be nice for purchasing surprise gifts.
DEJAN MARJANOVIC/GETTY IMAGES
You'll be approved or denied for a card based on your credit score and history, independent of your partner's credit score and history. But depending on your age and circumstances, you may also be able to include income from your partner that you can reasonably access when applying for a new card.
Some banks offer joint credit card accounts, which you apply for together and are jointly responsible for the bills. But joint accounts are relatively rare, so this article instead considers the more common situation in which one person opens an account and then adds their partner as an authorized user.
Primary account holders can make their partner (or anyone else) an authorized user on their account. Authorized users can make purchases on the account, but the primary cardholder is responsible for all the charges (including those made by authorized users).
One of the biggest advantages couples have over solo travelers is access to more welcome offers. Specifically, each member of a couple could earn the welcome bonus on the same card if they each apply separately.
SDI PRODUCTIONS/GETTY IMAGES
This can be particularly useful if you're earning welcome offers for a specific trip. You could use one person's welcome offer for hotel bookings and the other person's for flights. Or, you could each use your welcome offer to book an award flight for the same trip.
But while both partners can potentially earn welcome offers on the same card, it's still important to coordinate application timing and avoid taking on more minimum spending than you can comfortably manage. Plus, each individual must keep in mind issuer application restrictions, such as Chase's 5/24 rule, when deciding which cards to apply for and when to apply for them.
And I love that my husband and I each have our own , as this lets us use our anniversary night certificates for consecutive nights to make a two-night stay.
THOMAS BARWICK/GETTY IMAGES
However, it often makes sense for couples to have complementary cards. By applying for different cards that complement what's in your partner's wallet, you can unlock better bonus-category coverage, different travel perks and access to different transferable rewards currencies.
This can be particularly useful if one person in a couple travels more frequently, as they may want to carry more cards with travel benefits, such as lounge access and airline or hotel elite status.
Be sure to weigh the combined annual fees against the benefits you'll actually use. And keep in mind that some cards let you share benefits with other travelers. For example, many airline credit cards offer a checked baggage benefit that extends to other travelers on your same reservation.
Use authorized user cards to share benefits and maximize rewards
In some cases, you may want to add your partner as an authorized user on a card. This can be an easy choice when there's no fee. But it can also make sense to pay an authorized-user fee in some situations.
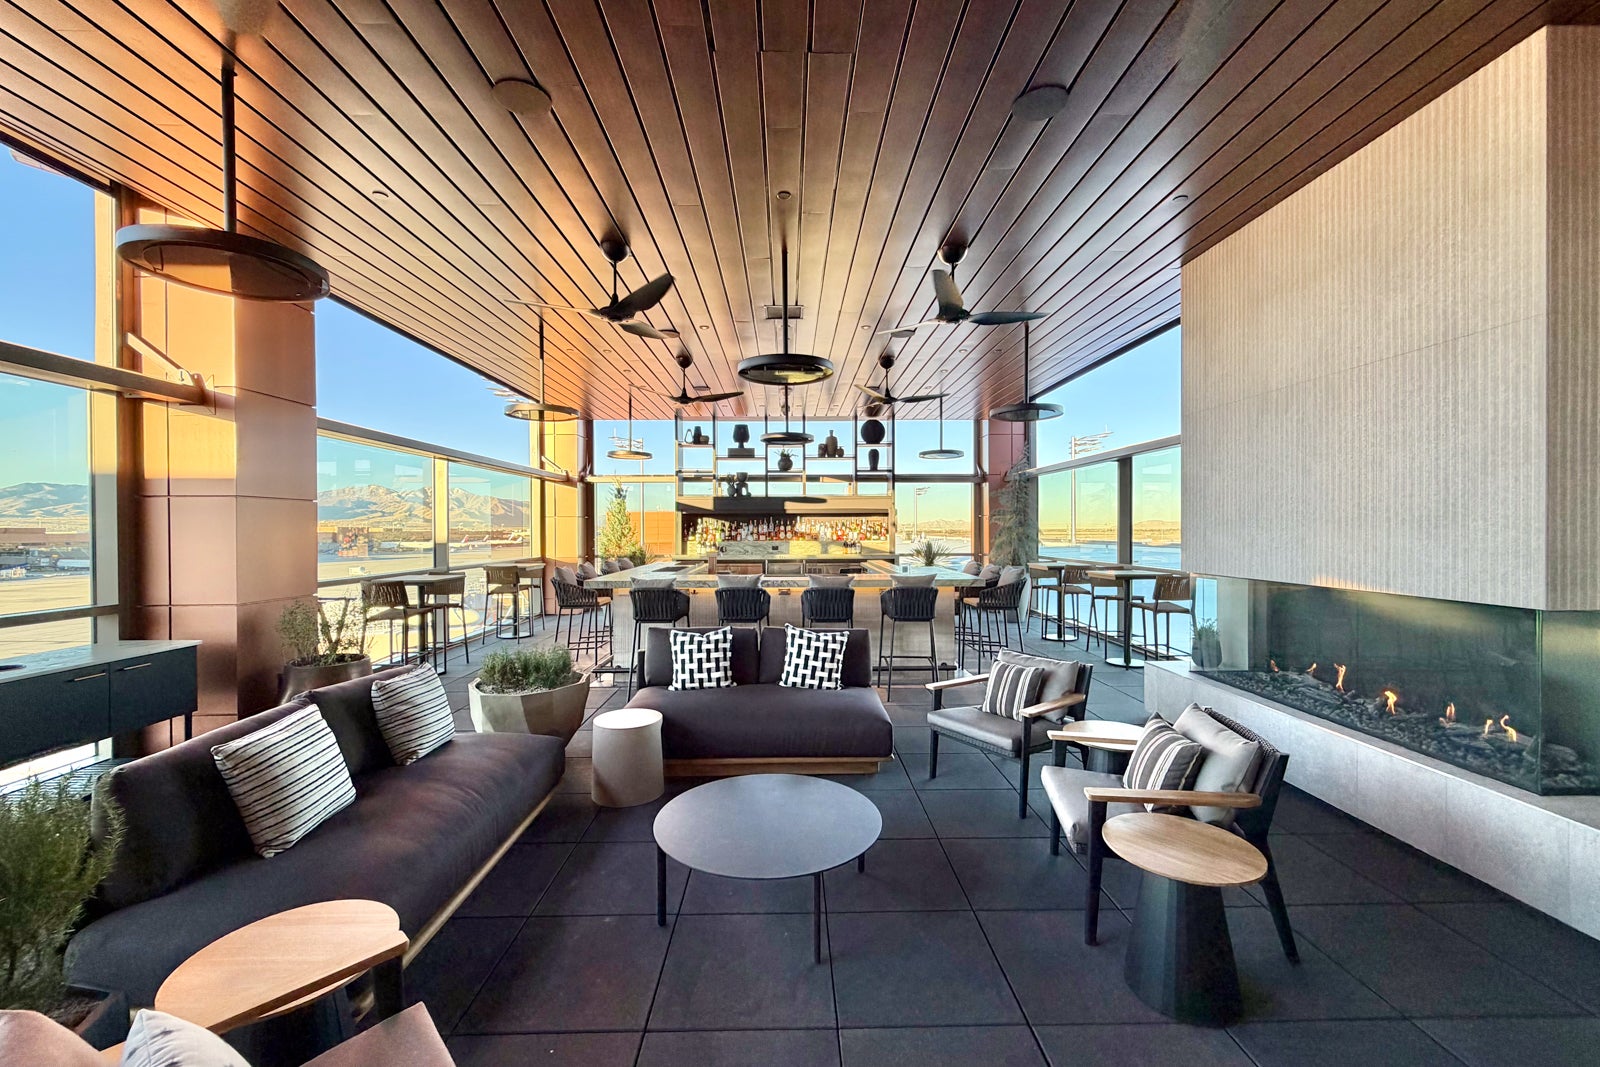
Amex Centurion Lounge in Salt Lake City. ZACH GRIFF/THE POINTS GUY
However, keep in mind that some benefits don't extend to authorized users. For example, purchases on additional Platinum Cards count toward many of the Platinum Card's statement credit benefits, such as up to $200 in airline incidental fee statement credits per calendar year (enrollment required). But additional Platinum Cards don't get their own statement credits.
So, while it might make sense for one partner to hold a premium travel card and add the other as an authorized user, it can make sense for both partners to independently hold cards that offer valuable benefits you'll use.
For example, my husband and I both hold several hotel credit cards, such as the (see rates and fees) and (see rates and fees), since their annual free night certificates and other perks provide ample value.
Adding your partner as an authorized user may also help them build credit if the issuer reports the account to credit bureaus and the account is managed responsibly. However, missed payments or high credit utilization could hurt their credit instead.
Whether you and your partner earn the same currencies on your credit cards or different currencies, and whether you combine your finances or not, it makes sense to coordinate how you earn and redeem rewards.
SVETIKD/GETTY IMAGES
Consider what types of rewards you should both be earning based on the trips you want to take. For example, if you have your sights set on visiting a far-flung international destination, spending on a Southwest credit card likely isn't the best choice. Instead, earning hotel points in a program with properties in your desired destination, airline miles with a program that serves that destination or transferable rewards is a better bet.
The benefit of both partners earning the same transferable currency is that you can each transfer to the airline or hotel program of your choice once you're ready to redeem. But there's also value in diversifying your earnings in case flight availability appears in a program that only some transferable currencies can access.
Before deciding which rewards to earn, consider how you'll redeem them together. Some credit card issuers let you move rewards between eligible household accounts, while some airline and hotel loyalty programs allow members to pool points or transfer them to each other. Even when you can't combine rewards, you may be able to use your points or miles to book travel for your partner.
Couples have plenty of opportunities to earn more rewards and enjoy more credit card benefits by coordinating their credit card strategies. Whether you and your partner decide to get the same cards, hold complementary cards or add each other as authorized users, the best approach depends on your spending habits and travel goals.
My husband and I have found that having our own credit card accounts while coordinating which rewards we earn and redeem works well for us. But you don't need a wallet full of cards to benefit from a two-player strategy. Even a few carefully chosen cards can help you earn more rewards and enjoy more perks together.
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.