The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Guides
Credit card debt hits new record of over $1 trillion — here's how to consolidate and pay off your debt
Emily Thompson specializes in beginner content as a credit cards editor. She taps into her prior experience as a high school English teacher to help others demystify credit scores and unlock experiences that credit card rewards can make possible.
When Ryan worked as a TPG credit cards writer, he oversaw refreshes of card reviews and card offer stories. He enjoyed racking up cash back and helping readers maximize their points and miles for their next big trip.
also contributed to this story
February 6, 2024 • 7 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
U.S. credit card debt has reached a record high, now exceeding $1.13 trillion, with average balances and interest rates continuing to rise.
Paying only the minimum payment on credit card balances can lead to significant interest charges and a prolonged payoff timeline.
Effective strategies for paying off debt include the avalanche method, snowball method and debt consolidation through balance transfers.
Establishing habits like tracking spending, using autopay and making biweekly payments can help prevent future debt accumulation.
What to consider
Interest rates on credit card balances are typically much higher than those for mortgages or car loans, making debt costly if not managed carefully.
Balance transfer offers may provide temporary relief but require paying off the balance before the promotional period ends to avoid additional interest.
Negotiating with issuers for lower rates or payment plans is possible but not guaranteed.
What you'll miss from the article
Detailed step-by-step guides on debt payoff methods and practical tips to avoid falling back into credit card debt.
Generated by AI with support from our editorial team.
Update: Some offers mentioned below are no longer available. View the current offers here.
Credit card debt in the U.S. has reached another all-time high. It passed the $1 trillion mark for the first time in the middle of last year — and it's still climbing.
According to the New York Federal Reserve‘s latest report on household debt and credit, credit card balances increased by $50 billion (a 4.6% quarterly increase) in the fourth quarter of 2023 and now stand at $1.13 trillion.
Here at TPG, we spend much of our time going on about the incredible value you can get from credit card rewards, whether you’re looking to pay off a big holiday purchase or simply get some cash back to pad your bottom line.
However, these recommendations all carry a huge disclaimer: If you get into credit card debt, you’ll rapidly erase the value of any rewards you’ve earned and end up in a difficult financial situation.
Today, we will look at what you need to know about how to pay off credit card debt and avoid acquiring more in the future.
The minimum payment problem
If you have credit card debt, you’re not alone. Americans have an average credit card debt of over $5,550, according to Experian. As interest rates remain high, it’s more important now than ever to understand and work to pay off credit card debt.
Credit card debt is easy to acquire because of credit cards’ high interest rates for unpaid balances, especially on the most rewarding cards. The other two types of most common debt are mortgages and car payments, which currently have average interest rates of over 6.5%. In contrast, the average interest rate for a new credit card account is over 20%.
Thankfully, strong consumer protection laws in the U.S. require card issuers to help you understand the dangers of credit card debt. At the end of each monthly billing cycle, your credit card issuer sends you a statement showing all the changes you made during that billing cycle. This statement shows the total amount you owe as of the statement closing date (your statement balance) and also shows a “minimum payment” due.
If you pay your statement balance in full every month, you never have to worry about racking up credit card debt. But if you only make the minimum payment (or any amount below the full statement balance), you will start accruing interest and it can become an issue.
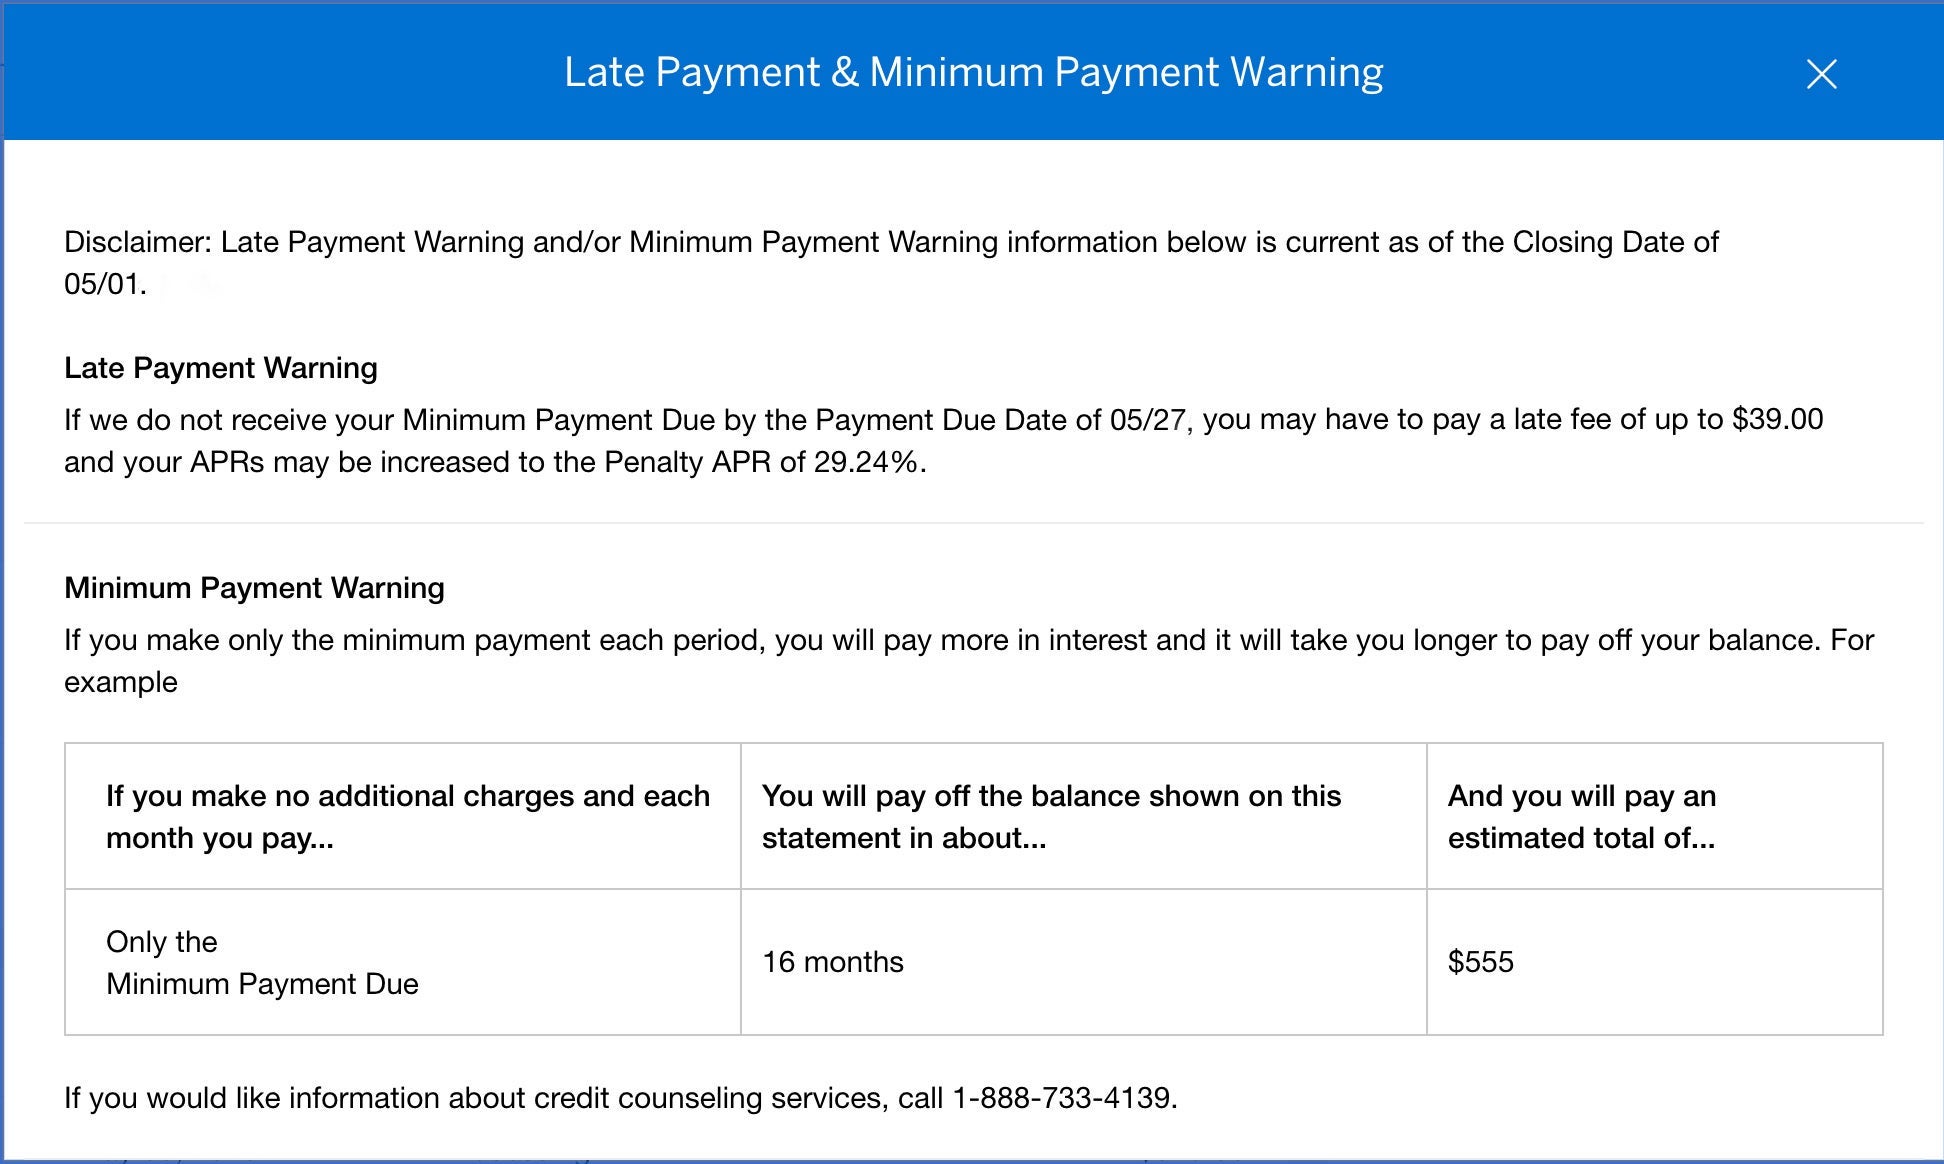
For example, this is a Marriott Bonvoy Business® American Express® Card statement for a balance of $375. If the cardholder pays off the card in full before the payment due date, they do not have to worry about paying interest.
AMEX
However, the statement outlines the amount of time and money it would take them to pay off this balance if they were to only make the minimum payment of $35. If they made that choice, it would take them 16 months and cost them an extra $180 in interest charges to pay just this card off. If they were late on their payment or paid only the minimum amount on other months, they would owe even more.
Before you start tackling debt, take a look at your spending habits. Identify areas where you can cut back. The more you limit your spending, the more you can put toward your debt payment.
List out debts
NATALIA GDOVSKAIA/GETTY IMAGES
This can be difficult to face, but it is an important element of choosing your approach. Make a list of each debt you have and its interest rate.
Choose an approach
There are a few approaches you can take if you want to pay off credit card debt.
Avalanche method: First, pay off the card with the highest interest. Take the money you were able to cut from your spending and put it toward paying down this card. When you have paid this debt, move to the debt with the second highest rate. Continue until you have eliminated your credit card debt.
Snowball method: Focus on your debt with the smallest balance first. When you have paid it off, use that money to work toward your next smallest balance. Eventually, use this momentum to tackle your debt with the highest balance and you will eliminate all of your credit card debt.
Consolidate credit card debt: You can also consolidate your credit card debt by opening up a new credit card with a 0% intro annual percentage rate (APR) offer or take advantage of balance transfer offers. The exact offers vary from card to card, but you can transfer your high-interest balance to this new card and pay it off over the course of 12 to 15 months without racking up any more interest. Just make sure to pay off the balance before the 0% intro APR period expires or you’ll end up fighting an uphill battle against interest again.
Credit card forgiveness: It’s unlikely that a bank will outright forgive your credit card debt, but you might be able to negotiate a lower interest rate or monthly payment plan. There is no guarantee, but it doesn’t hurt to ask.
When you are out of credit card debt, put strategies in place to make sure you stay out. You can use several tools to your advantage, starting with autopay. Most major credit card issuers allow you to set up autopay on your accounts, meaning your bills will automatically be paid before the due date and you’ll never miss a payment. You can use this updated envelope system to ensure you have enough money in your bank account to avoid overdraft fees.
Another option is to pay off all of your balances every two weeks. To do this, set a recurring reminder on your calendar for the 1st and 15th of every month. When that reminder pops up, log in and pay off all your balances, even if the statement hasn’t closed yet. Since you usually have about a month from when your statement closes to when your bill is due, this every-two-week method helps you stay ahead of your bills and never miss a payment.
No matter where you fall compared to Americans’ average credit card debt, plenty of strategies are available to help you pay off whatever credit card debt you might have.
While you shouldn’t hold your breath for credit card debt forgiveness, you can consolidate credit card debt or use one of a few different approaches to pay it off, like the avalanche method.
Regardless of which route you choose, be sure to put a plan in place to avoid or reduce credit card debt in the future.
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.