The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
News
How the Apple Card Compares to Other No Annual Fee Cash-Back Credit Cards
Darren holds the Guinness World Record as the planet's most prolific professional blogger, a feat he achieved in 2010. He's a seasoned storyteller, instructor and communicator, working across marketing, editorial and public relations for some of the world's most progressive brands. He's an explorer at heart, having traversed nearly 50 countries and all 50 US states. He's flown over one million miles on Delta alone, and takes pride in facilitating unforgettable excursions using points and miles.
March 28, 2019 • 8 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
A new titanium cash-back card is launching with a focus on simplicity, offering elevated rewards for purchases at a specific technology brand and through mobile payments.
This card lacks transfer partners and does not earn points or miles, instead providing straightforward cash-back earnings.
The article compares this new product to three popular no-fee cash-back cards, highlighting differences in bonus categories, international usability and introductory offers.
The card's integration with a major smartphone platform may appeal to users who frequently use mobile payments and purchase from the associated brand.
What to consider
Some offers discussed in the article are no longer available.
The new card is best suited for those who make frequent purchases from the associated technology brand or regularly use mobile payments in areas where they are widely accepted.
International acceptance and foreign transaction fees vary among the compared cards, so frequent travelers should review these details before applying.
What you'll miss from the article
A detailed comparison of leading no-fee cash-back cards, including which spending habits align best with each option.
Generated by AI with support from our editorial team.
Update: Some offers mentioned below are no longer available. View the current offers here.
The Apple Card is expected to come out this summer, offering 3% cash back on purchases directly from Apple, 2% on anything you buy using Apple Pay and 1% on anything purchased with the physical card. The earning is simple and there's no annual fee. But there are also no transfer partners nor the ability to earn points or miles.
The titanium Apple credit card will enter a crowded marketplace of no annual fee cards, and greater competition generally leads to better offers for consumers. Below, we'll compare the incoming Apple Card with three of the most highly regarded no annual fee cards on the market today, with an aim to guide you to the card (or cards) that make the most sense for your lifestyle and spending habits.
Card Name
Best For
Cash-Back Overview
Intro APR period
Foreign-Transaction Fees
Sign-Up Bonus
Apple Card
Apple purchases, simplicity
3% (purchases made directly with Apple)
2% (all Apple Pay purchases)
1% (everything else)
N/A (13.24% to 24.24% variable APR from open)
None
N/A
Citi® Double Cash Card
Everyday spending
2% (all purchases; 1% when you buy and 1% as you pay)
0% APR for 18-months on balance transfers made within the first four months of account opening (then 13.99% - 23.99% variable APR applies)
3%
N/A
Capital One SavorOne Cash Rewards Credit Card
Dining and entertainment
3% cash back on dining, entertainment, popular streaming services and at grocery stores (excluding superstores like Walmart® and Target®), plus 1% on all other purchases
0% APR for 15 months on purchases and balance transfers (then a 14.99% - 24.99% variable APR applies)
None
$200 one-time bonus after you spend $500 on purchases in your first 3 months from account opening
The information for the Apple Card has been collected independently by The Points Guy. The card details on this page have not been reviewed or provided by the card issuer.
Apple Card
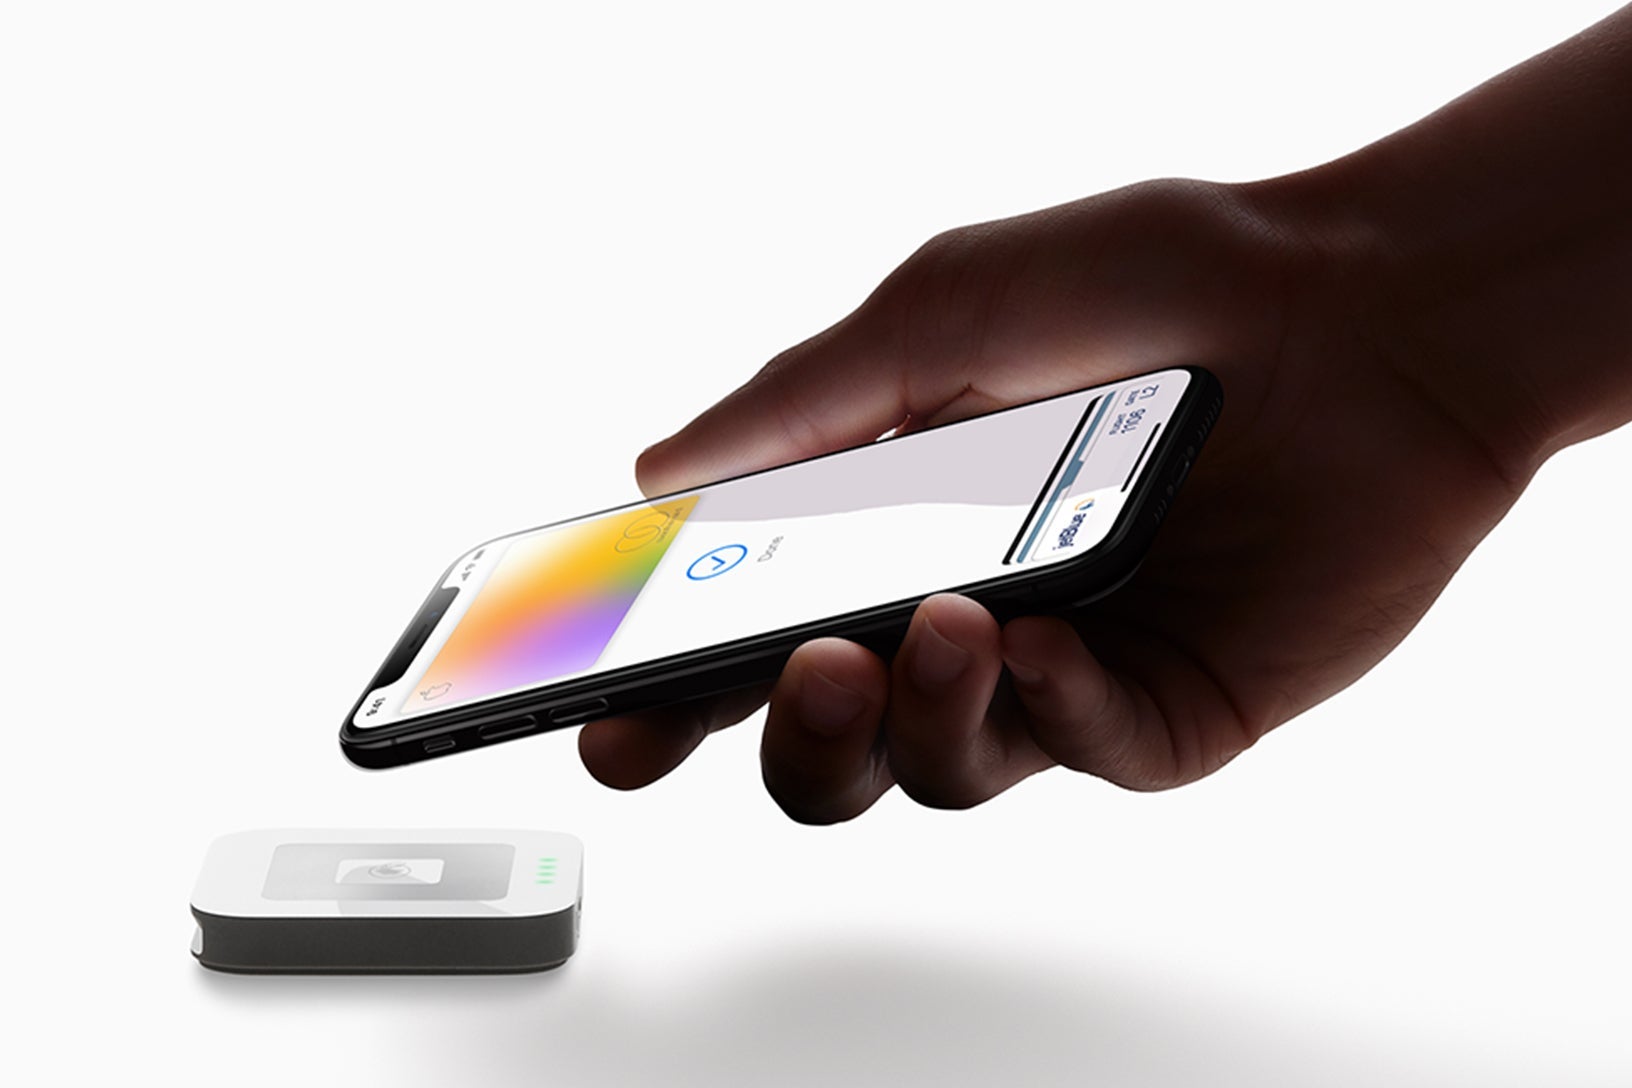
Maximize your cash back by using Apple Pay with Apple Card. (Images courtesy of Apple)
When it opens to applicants in the summer of 2019, the Apple Card will have several things going for it. The first is sheer style. While you'd expect a rigid, sleek card if you're paying an annual fee, the Apple Card will be the first fee-free card to be constructed of titanium. You don't earn additional cash back just because your card is a looker, but fans of unique cards such as the yellow The Platinum Card® from American Express and rose gold American Express® Gold Card will appreciate adding this to their collection.
Then there's 3% cash back on purchases made directly with Apple. While we have covered ways to earn even more from Apple purchases, the Apple Card will no doubt be the simplest way to earn 3% back.
The Apple Card has the potential to earn 2% cash back on everything, but that's only in a distant world where Apple Pay is accepted everywhere. We aren't quite there yet, though Apple Pay is widely accepted in major metropolitan areas. In instances where a purchase would fall under a non-bonus category for even top-tier premium credit cards (typically earning 1%), the mere act of making that purchase via Apple Pay would net Apple Card users a full 2% back.
Finally, there's the tight integration with Apple's iPhone. While credit card apps have come a long way, nothing quite compares to the beauty and simplicity of Apple's spend-tracking software. For devout Android users, this will not apply.
Is This Card For Me?
If you make frequent purchases from Apple, and/or you live in an environment where you can easily pay for most items with Apple Pay, you may want to take advantage of Apple Card's large cash-back categories.
Citi® Double Cash Card
One of the simplest and most rewarding cash-back cards is the Citi® Double Cash Card. This card gives you two opportunities to earn cash back: 1% when you buy and then another 1% when you pay, for a total of 2% cash back. You only need to make the minimum payment each month to earn the second reward, but we strongly recommend always paying your balance in full.
The biggest drawbacks of the card are the lack of a sign-up bonus and a 3% foreign-transaction fee. Still, 2% cash back on every purchase with no limit on the amount of cash back you can earn is a pretty solid value proposition.
Is This Card For Me?
If you’re looking for a cash-back credit card with no annual fee and you don’t want to worry about category bonuses and figuring out the best credit card to use for each purchase, the Citi® Double Cash Card may very well be the right card for you. In particular, it’s great for those that don’t use their credit card internationally (since there’s a 3% foreign-transaction fee) and don’t have a Chase Ultimate Rewards-earning credit card that would boost the earning rate of the Chase Freedom Unlimited.
Capital One SavorOne Credit Card
(Photo by Ali Inay on Unsplash)
The SavorOne card is the no annual fee version of the Capital One Savor Cash Rewards Credit Card, which is a super attractive offer for people who spend a lot on dining and entertainment and like cash back. The standout feature of the SavorOne card is its 3% cash back on dining, entertainment, popular streaming services and at grocery stores, plus 1% on all other purchases. The information for the Capital One Savor Cash Rewards Credit Card has been collected independently by The Points Guy. The card details on this page have not been reviewed or provided by the card issuer.
If you take a look at your spending habits and see that dining out, engaging in entertainment (think concerts, museums, etc.) and stocking up at the grocery store make up a big chunk, you'll be hard-pressed to find another fee-free card that makes it this simple to earn this much. While we generally recommend cards like the Chase Sapphire Preferred Card ($95 annual fee) for international purchases, the SavorOne also charges no foreign transaction fees — a rare find in a no annual fee card.
Is This Card For Me?
If you're looking to keep things simple and don't have the time to learn the ins and outs of extracting maximum value from transferable points and miles, the SavorOne is an excellent choice for those who spent a lot on dining, entertainment and groceries. That said, it works best in concert with other cards which maximize other purchases — things like gas stations and travel.
Bottom Line
The Apple Card delivers strong cash-back potential in two distinct ways. If you're the type who upgrades their iPhone and/or iPad annually, it may be worth holding this card just to earn 3% back on those big-ticket purchases. With no annual fee, the only notable downside to adding it to your collection is the impact to Chase's 5/24 rule, which causes the bank to automatically reject you for any new Chase card if it detects that you've procured 5 new personal cards within the past 24 months. If you've already opened 3-4 new cards in the past 24 months, be careful before applying for another. We recommend maximizing that final slot and use it for a card with a robust welcome bonus.
When it comes to no annual fee cards, there's no single card that maximizes all purchases. The upside is that you won't pay any dues to have several fee-free cards in your wallet. Adding the Apple Card makes a lot of sense for city dwellers who can pay for practically anything using Apple Pay, as all of those purchases will earn 2% cash back. Even better, use it alongside specialty cards like the SavorOne, which maximizes cash back on dining and entertainment.
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.