The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Guides
Should you sign up for credit cards with loyalty programs you don't use?
Senitra is a credit cards expert and TPG contributor. Senitra spent seven years working in marketing, has been a freelance writer for numerous websites and worked as a full-time reporter and editor for several daily and weekly newspapers in Texas, New Jersey and Pennsylvania. She has been quoted on her credit card expertise in MarketWatch, Consumer Reports and Kiplinger.
April 21, 2021 • 11 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
Travelers often focus on credit cards linked to airlines or hotels they use most, but there can be value in considering cards from unfamiliar loyalty programs.
Bank restrictions may limit your ability to get new cards from familiar programs, making alternative options worth exploring.
Some lesser-known programs offer valuable redemption opportunities, especially through airline alliances and sweet spots with lower award rates.
However, points in unfamiliar programs may expire quickly or require more effort to maximize, so these cards may not suit everyone.
What to consider
Certain programs have strict expiration policies, with points expiring after periods of inactivity or after a set number of years.
Learning the nuances of new loyalty programs can be time-consuming and may not be worthwhile if you don't plan to redeem the rewards.
Opening additional cards may impact your eligibility for other popular products due to application restrictions.
What you'll miss from the article
A detailed analysis of when it makes sense to pursue cards from unfamiliar loyalty programs and how to weigh the pros and cons for your travel goals.
Generated by AI with support from our editorial team.
Update: Some offers mentioned below are no longer available. View the current offers here.
As travel rewards enthusiasts, we hear a lot about credit cards from airlines such as Southwest, United, Delta and American. Same goes for hotel credit cards from the World of Hyatt, Hilton Honors, Marriott Bonvoy and IHG Rewards. If you’re an avid or frequent traveler, there’s a good chance your journeys may involve one of these airlines or hotel chains. So it makes sense that these are the cards on most peoples’ radar.
But let’s say you live somewhere with no Alaska Airlines or JetBlue presence, for example. You never fly with those airlines, so why would you want their credit cards? As you’ll see, there are pros and cons to getting new credit cards from programs you haven’t used previously. Here are some of the reasons why you should — along with reasons why you shouldn’t — sign up for credit cards with loyalty programs you don’t use to help you decide if doing so might be right for you.
Why you should: Bank restrictions prevent you from some cards
Restrictions such as Chase’s 5/24 rule (where you will not get approved for a Chase card if you have more than five new cards in 24 months) limit the number of cards you can get from an issuer.
If you already have all the cards you can get with other programs due to bank rules, it’s time to look beyond Chase, Amex and Citi. Banks such as Barclays and Bank of America have several airline and hotel cards, although they may decline your application if you have too many recent inquiries or other new accounts on your credit report. Bank of America also has its own 24-month rule, with the terms and conditions on their credit cards mentioning, “This card may not be available to you if you currently have or have had the card in the preceding 24 month period.”
That’s not to say that all of these cards are great for everyone or worth having, but once you’re halted from other cards due to bank rules, it’s time to start thinking outside of the box and these are some cards to consider.
The information for the Best Western Rewards credit card has been collected independently by The Points Guy. The card details on this page have not been reviewed or provided by the card issuer.
Why you should: Airline alliances and partnerships
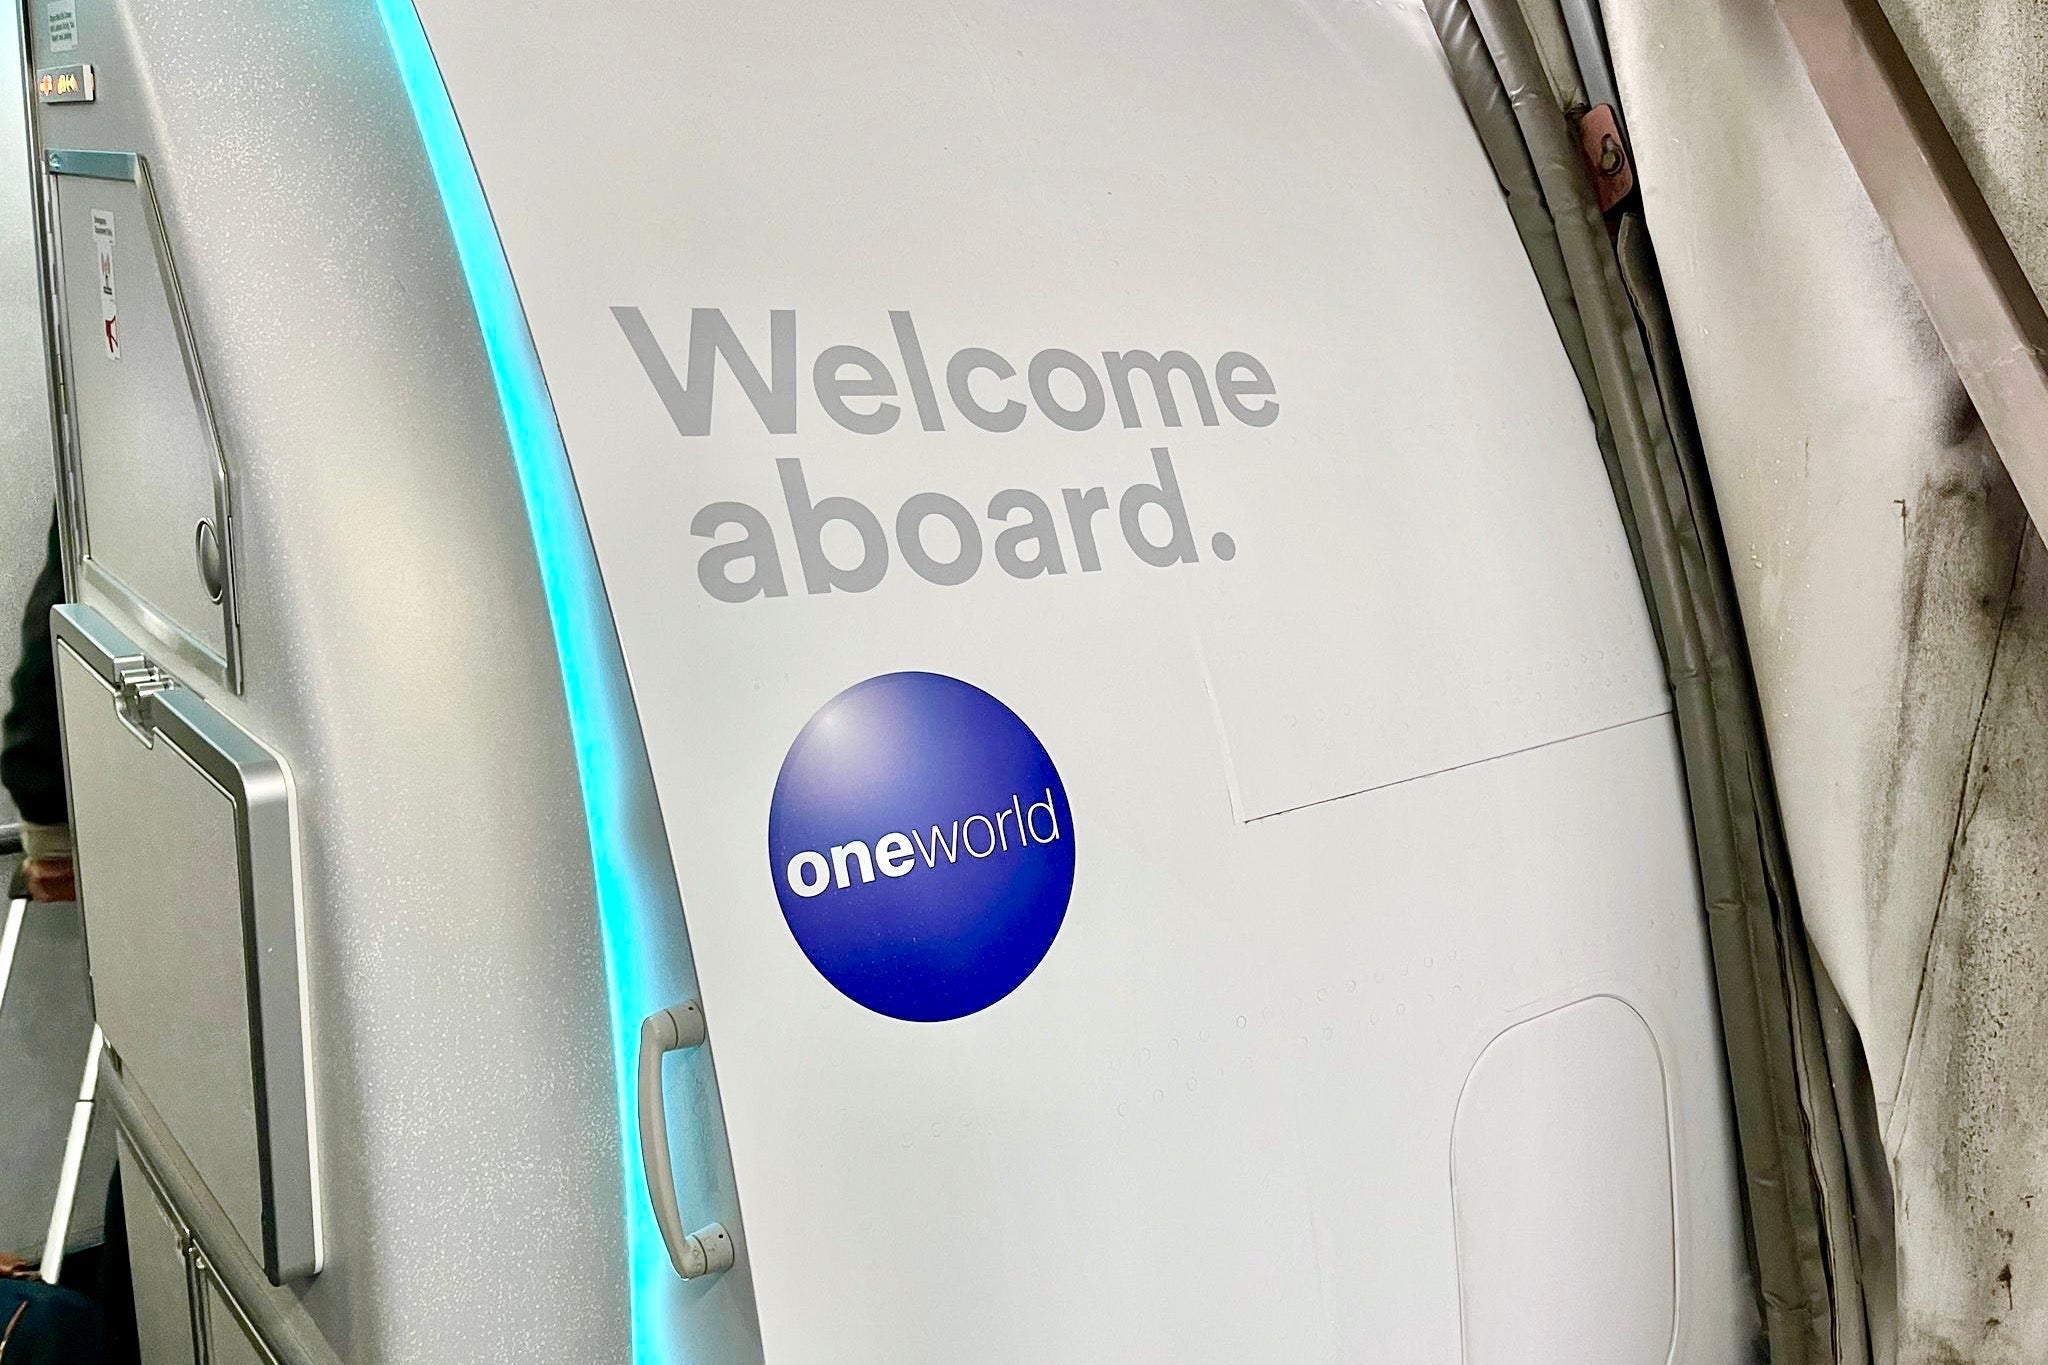
Alaska Airlines has joined the Oneworld alliance. (Photo by Benji Stawski/The Points Guy)
Don’t forget to consider the program’s alliances and partnerships with other airlines that you might use. For years, I had the Alaska Airlines Visa® credit card and had never actually flown on that airline. The benefit of the card for me was to earn Alaska miles and use them to fly on their partners, such as Cathay Pacific, Fiji Airways and Qantas. And since Alaska has joined Oneworld, there will be even more opportunities to use those miles on Oneworld partners.
The same is true for credit cards from international airlines. I’ve only flown British Airways once in the past, but since you can use its Avios to fly on any Oneworld partner, the British Airways Visa Signature Card is certainly worth a look for those who are under 5/24. If you live in an American Airlines hub city or just find yourself flying AA with some regularity, it’s often worth comparing the redemption price using BA Avios to AAdvantage miles, especially for short-haul domestic flights.
For example, BA’s distance-based award chart charges 9,000 Avios for nonstop economy flights between 651 and 1,151 miles in distance. On AA, the standard MileSAAver awards for the same routes are 12,500 miles. However, with AA’s Web Special pricing, award rates may be lower than 12,500 miles, so that’s why it’s important to compare.
Why you should: Program has sweet spots with low redemption rates
This goes along with the previous point about alliances and partnerships. Many times, some of the alternative programs offer lower redemption rates than the big programs, especially if you’re looking to fly in a premium class. This is known as a “sweet spot.”
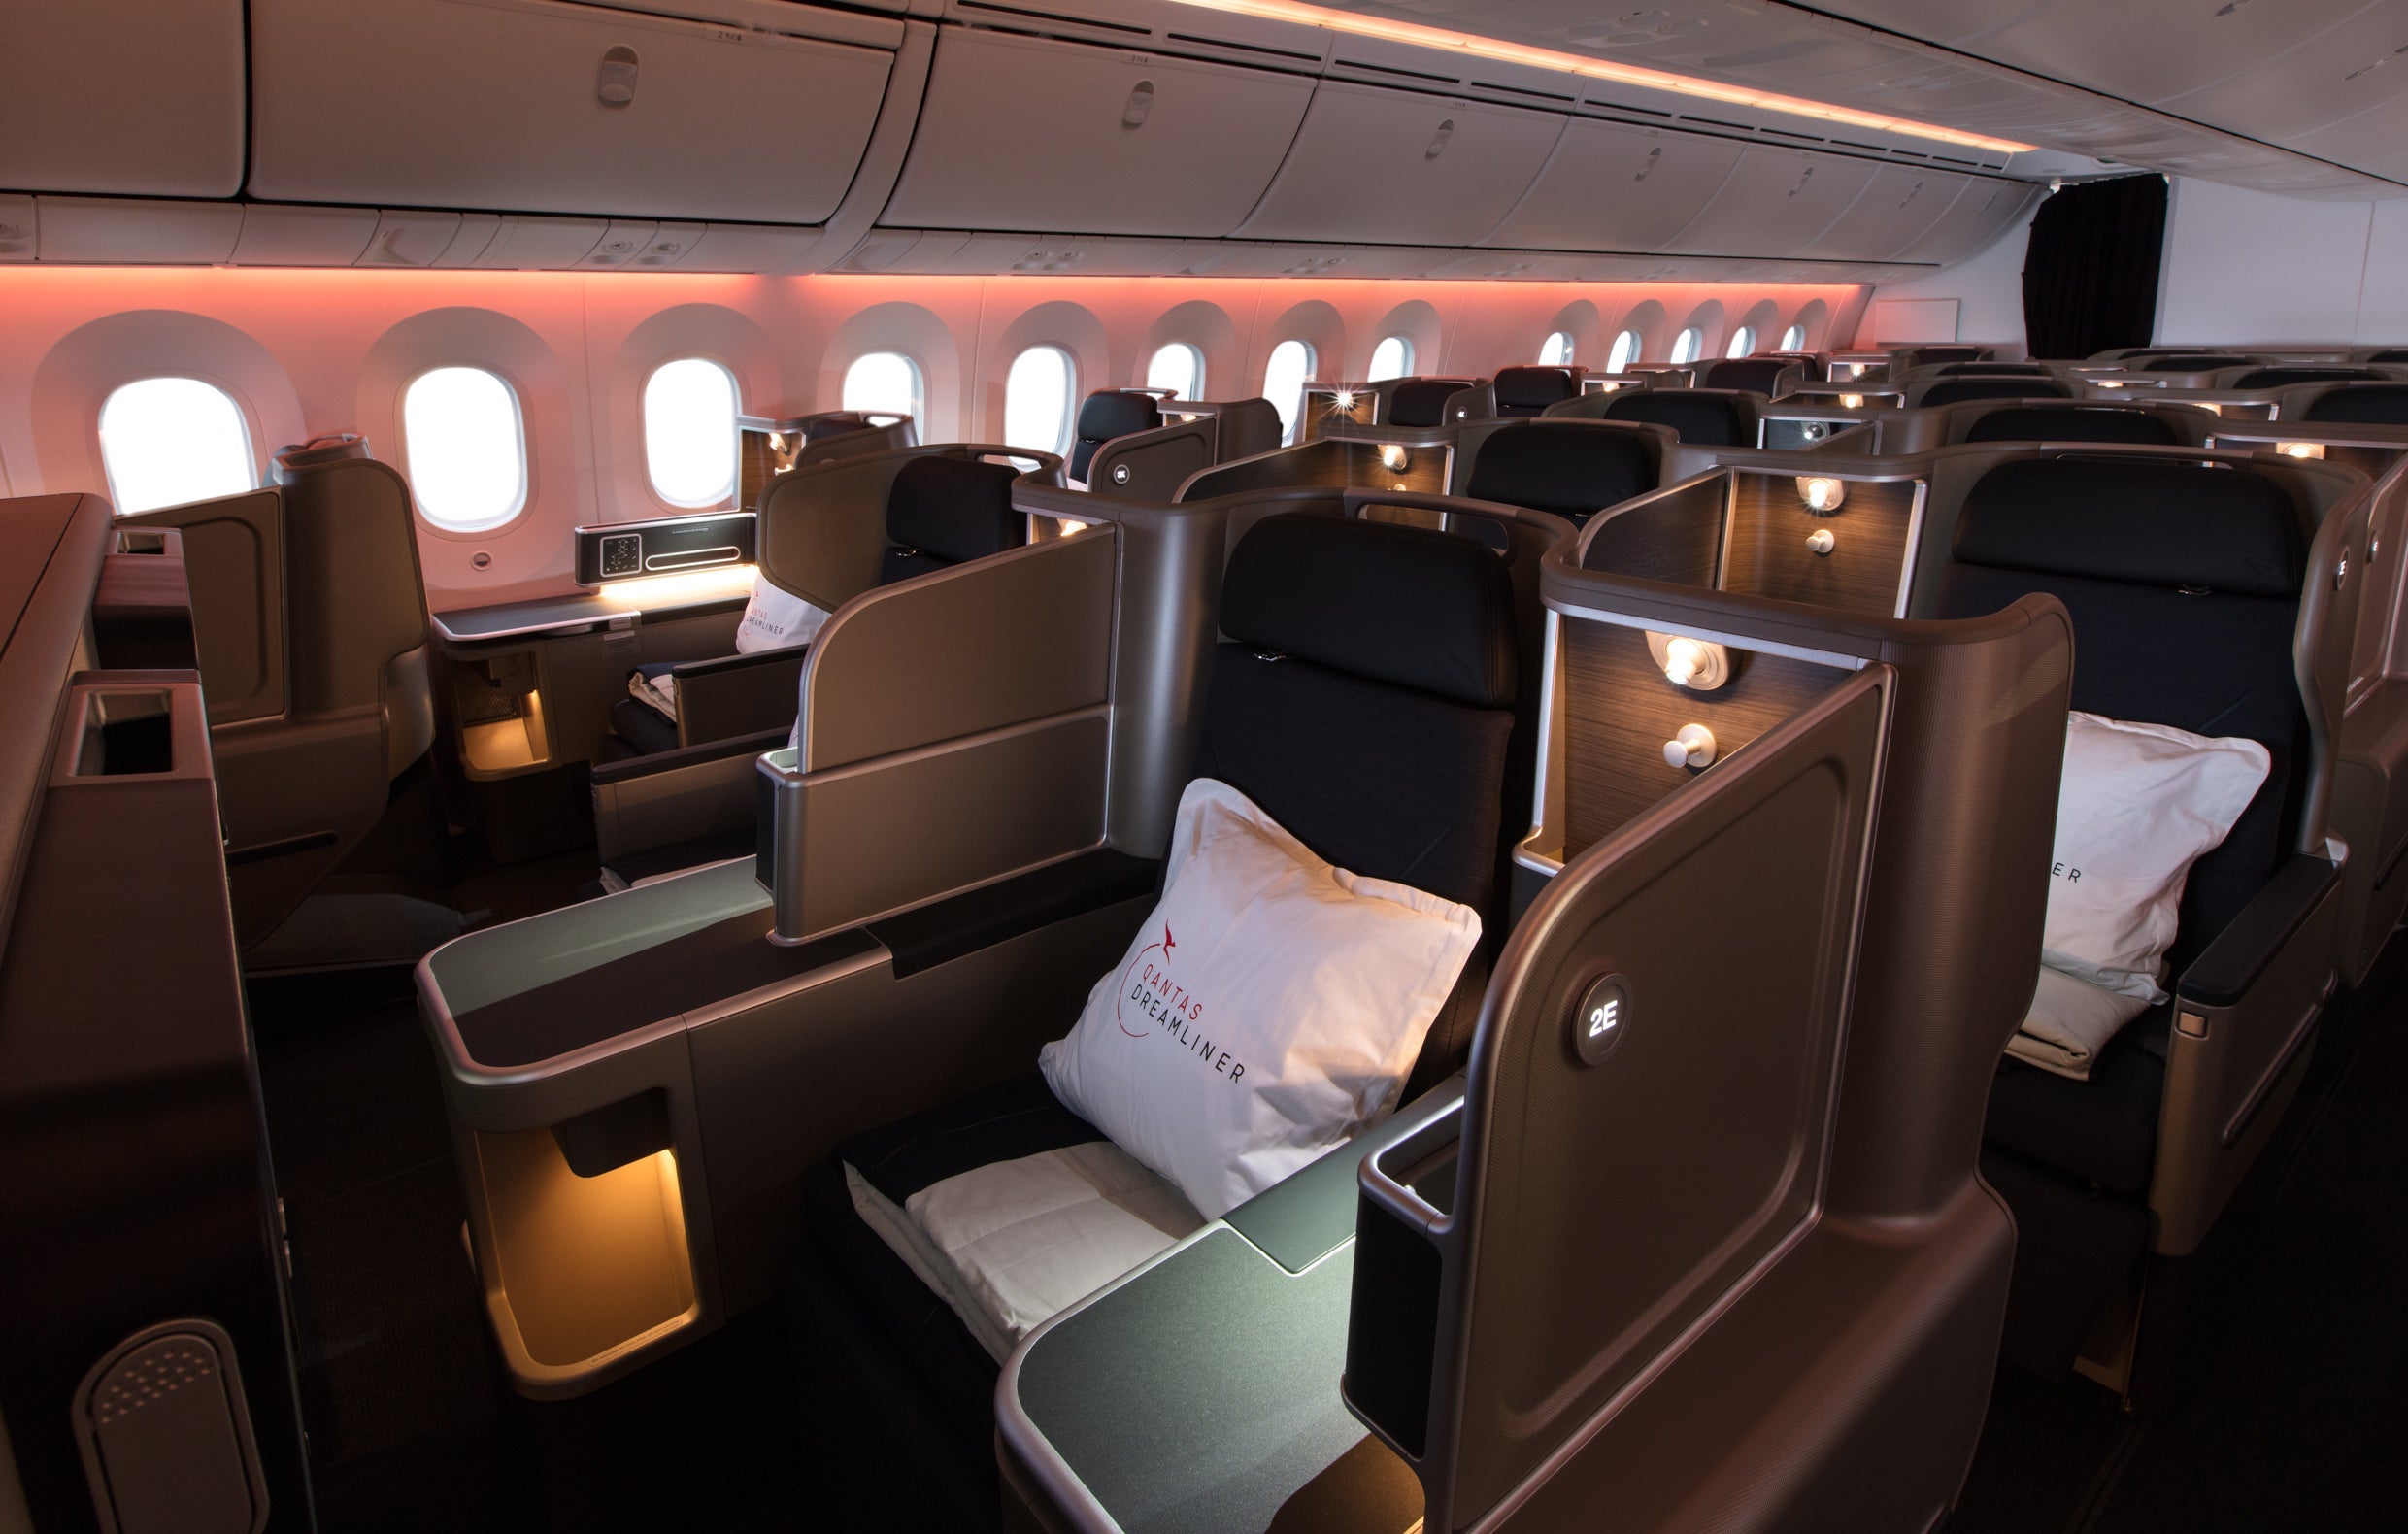
Use your Alaska Airlines miles to book a Qantas Boeing 787 business-class seat. (Photo courtesy of Qantas)
For example, you can use 55,000 Alaska miles to fly one-way business class on Qantas from North America to Australia or New Zealand. These awards using AAdvantage miles would be 80,000 miles for one-way business class at the lowest MileSAAver rate.
If you’re a Delta flyer, using Virgin Atlantic points to fly Delta One business class for 50,000 points each way to or from Europe can be considerably cheaper than using SkyMiles. Since Delta eliminated its published award chart in 2015, there’s no fixed redemption rates using SkyMiles and award pricing can have large variations. That 50,000-point redemption to Europe with Virgin Atlantic points could require 100,000, 200,000 or even 300,000 SkyMiles if booked with Delta.
Keeping this in mind, the Virgin Atlantic World Elite Mastercard® could be worth getting to boost your balance. A sudden devaluation to Virgin Atlantic points was announced in early 2021, but the airline backtracked and is still honoring its previous sweet-spot redemption rate.
With any new card you’re considering opening, it’s always important to gauge the sign-up bonus. An all-time-high bonus can be a compelling reason to apply for a card that previously wasn’t on your radar.
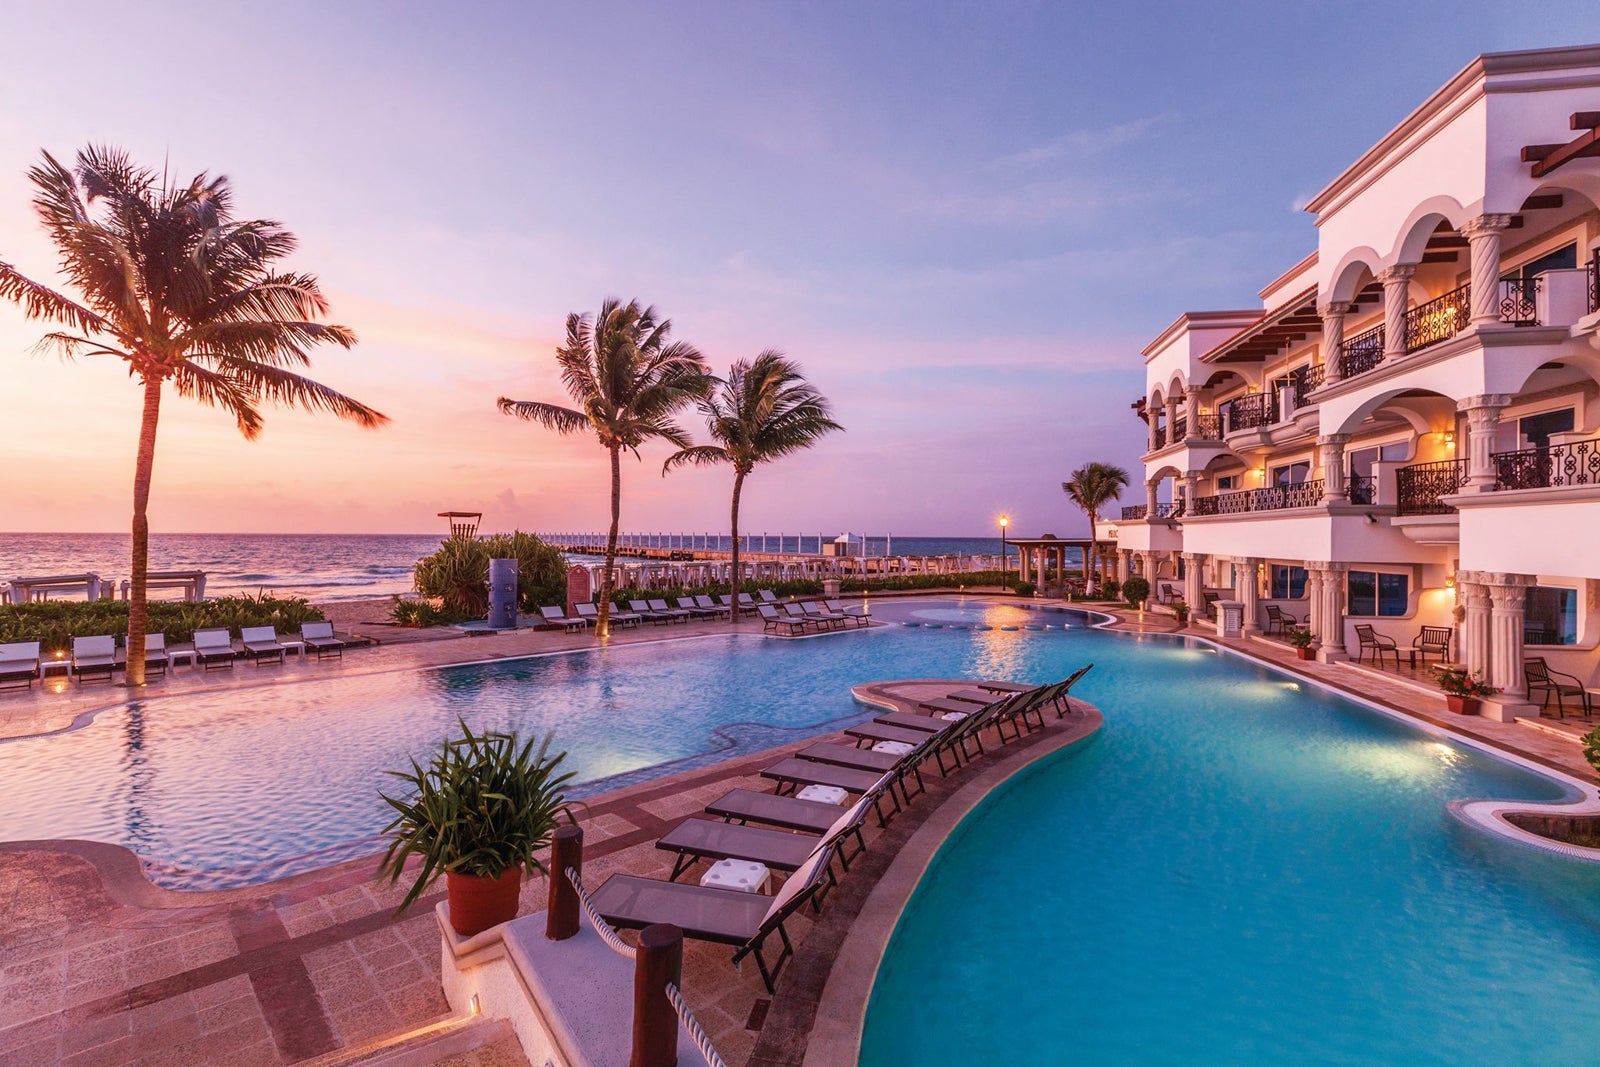
Redeem your Hilton Honors points for a vacation at the Hilton Playa del Carmen. (Photo courtesy of Hilton Playa del Carmen/Facebook)
Many years ago, when I was more of a newbie to travel rewards, I opened my first few hotel cards for Hyatt, IHG Rewards and Starwood Preferred Guest (now part of Marriott Bonvoy), and thought I was all set for my hotel stays with those cards. But when Hilton American Express cards began dropping six-figure welcome bonuses, I finally decided it was a good idea to add some Hilton points to my stash.
Why you shouldn’t: You know you absolutely won’t use the miles
Miles or points that have a short expiration date window may be particularly problematic if you haven’t identified an immediate redemption plan. Programs such as Spirit Airlines, Wyndham Rewards and Choice Privileges come to mind here.
With Choice, for example, points expire after 18 consecutive months with no qualifying account activity, such as a paid stay, redeeming points for a stay, spending on the Choice credit card or purchasing points. So if you just get the card, complete the minimum spending requirement to earn the bonus, sock-drawer the card and have no additional account activity, you could be at risk for your points expiring if you don’t keep a close eye on the calendar.
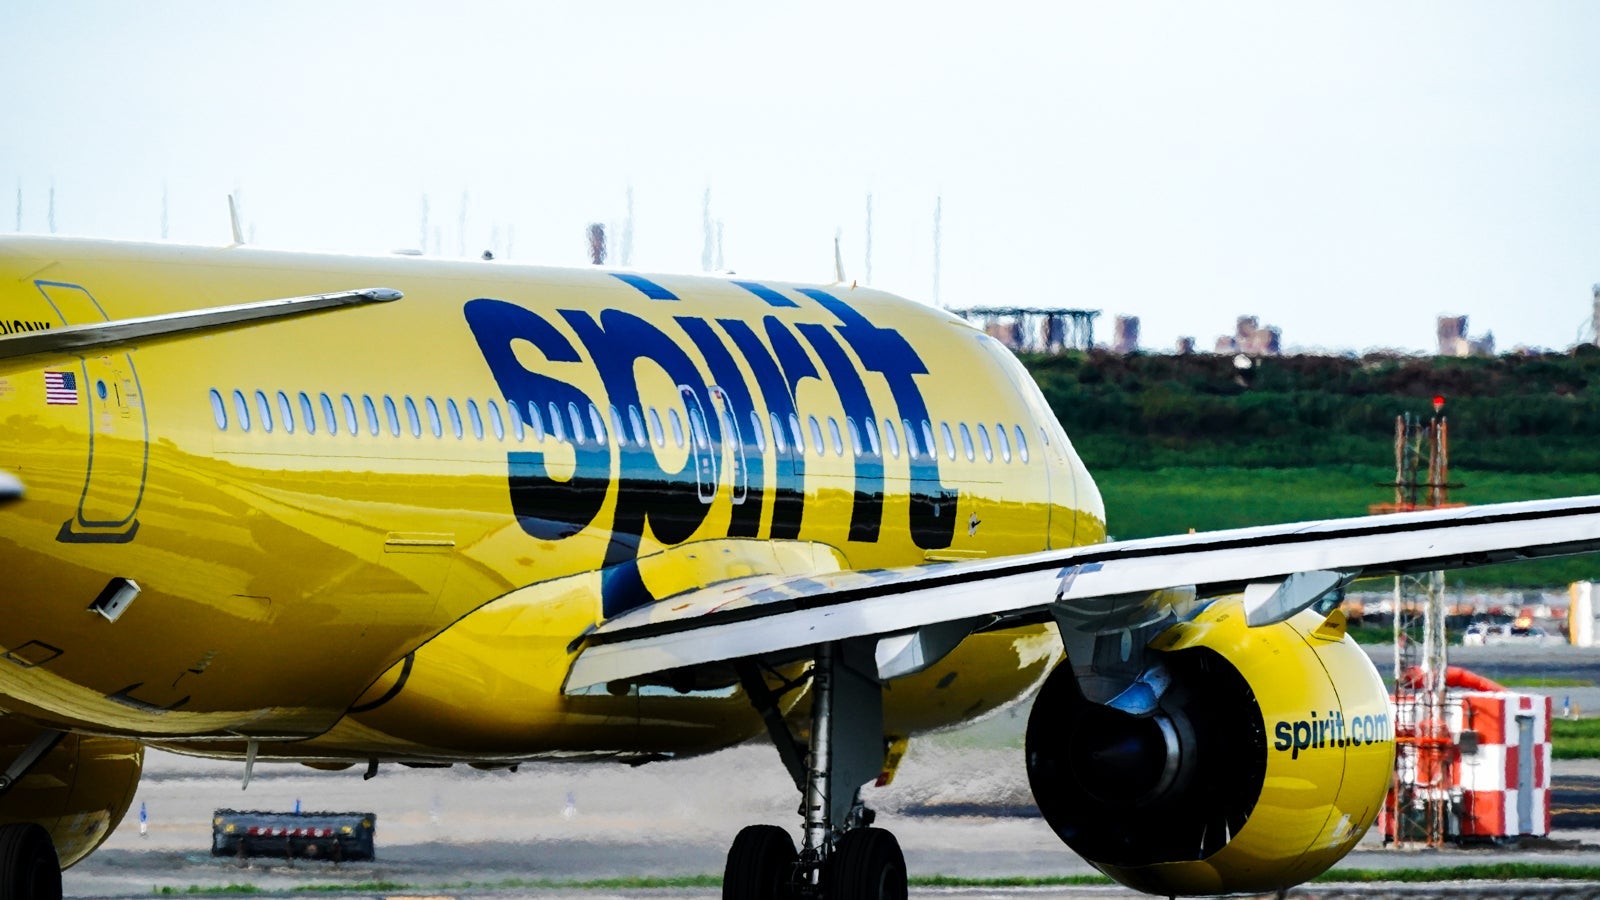
(Photo by John Nacion/SOPA Images/LightRocket/Getty Images)
With Spirit Airlines, points expire if you have no activity in 12 months. However, your points never expire as long as you have the Free Spirit® Travel More Mastercard®. And with Wyndham, points expire after 18 consecutive months without account activity, and all points expire after four years regardless of account activity.
Also, if you truly believe the chances of you flying an airline or staying at a certain hotel chain are slim to none, there’s not too many compelling reasons to get a card. For me, it’s highly unlikely I will fly Spirit Airlines or Allegiant Airlines based on my location and travel habits, so barring an eye-popping “deal of a lifetime” type of sign-up bonus, I’m going to pass on applying for those cards.
The information for the Free Spirit Travel More Mastercard has been collected independently by The Points Guy. The card details on this page have not been reviewed or provided by the card issuer.
Why you shouldn’t: You’re too busy to learn how to maximize redemptions in yet another program
Learning about miles and points can be time-consuming, especially if you try to get maximum value from every redemption. If you’ve got a few airline cards and a few hotel cards, you need to know how to redeem those points and miles you’re earning.
If you don’t have the time, energy or willingness to familiarize yourself with another loyalty program, it’s probably not worth signing up for a card if the miles are going to sit around unused. Airlines and hotels frequently devalue their programs, increasing the number of points or miles it takes to redeem an award, and the longer your points sit around, the more likely they are to be worth less in the future.
Why you shouldn’t: You’re trying to stay under (or get under) 5/24
While it’s true being over Chase’s 5/24 rule is a pro to signing up for cards beyond those offered by Chase, if you’re trying to remain or get back to being under 5/24, adding cards from other banks will prevent you from getting there. Keep in mind, though, that some of the alternative airline and hotel programs I’ve discussed, such as JetBlue, Alaska and Wyndham, have business card versions that you can apply for.
Whether or not you should sign up for cards with loyalty programs you don’t currently use is highly dependent on the program opportunities and the card’s sign-up bonus. For me, being way over 5/24, I found it beneficial to look for new credit cards and opportunities beyond the programs that are most frequently discussed.
Even if I wind up only using the card for a short time to meet the minimum spending requirement, receive the sign-up bonus and redeem the miles, I view it as one more travel experience that I likely wouldn’t have had otherwise.
Featured photo by Olleg/Shutterstock.
Updated 1/18/23
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.