The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Guides
Why I keep 2 United credit cards — even though United isn’t my primary airline
Matt Moffitt is a contributing editor and expert in getting the most out of credit cards and points (he carries at least 25 cards in his wallet at any given time). Originally from Sydney, Australia, he won the Green Card Lottery and lived in Austin, Texas for 10 years before relocating to Spain in 2025.
July 10, 2026 • 7 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
The article explores the author's rationale for keeping both a personal and a business airline credit card, despite not being loyal to the airline.
Holding both cards unlocks an annual bonus of 5,000 miles, valued at $65 as of July 2026 per TPG's valuations.
The business card delivers most of the value through hotel statement credits, expanded award availability, club passes and travel perks like free checked bags and priority boarding.
The personal card, which does not carry an annual fee, is kept mainly to remain eligible for the annual mileage bonus.
What to consider
To receive the annual 5,000-mile bonus, you must hold both an eligible personal and business airline card.
Expanded saver award availability is only accessible through the business card, unless you meet a high spend threshold on the personal card.
Redeeming miles through Pay Yourself Back can provide higher value toward the business card's fee than TPG's standard valuation.
What you'll miss from the article
A detailed breakdown of how pairing a personal and business airline card can maximize travel benefits and offset costs, even for infrequent flyers.
Generated by AI with support from our editorial team.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
That probably sounds strange coming from someone who carries between 25 and 30 credit cards at any given time. Most points and miles enthusiasts are looking for ways to simplify their wallets, and United isn’t even my primary airline. I only fly the carrier a couple of times a year, usually on domestic flights or trips to Mexico.
Yet for the past several years, I’ve continued renewing both my no-annual-fee United Gateway℠ Card (see rates and fees) and my United Business Card (which carries a $150 annual fee). While it may seem unnecessary to keep two United cards, this combination continues to deliver more value than it costs me.
Here’s why I haven’t been able to justify giving up either card.
It was a great fit when I first opened it, but over time, I found myself not using as many of its benefits. Rather than canceling the card outright, I downgraded it to the no-annual-fee United Gateway Card.
JGI/JAMIE GRILL/GETTY IMAGES
At first, I wondered whether it was worth keeping a card that spends most of its time in my sock drawer. Today, I only make a small purchase on the Gateway Card every six months to keep the account active.
Later, I added the United Business Card to my wallet. That’s when I realized there was actually a meaningful benefit to holding both a personal and a business United card.
Based on TPG’s July 2026 valuation of United miles, those 5,000 miles are worth roughly $65. That alone doesn’t justify paying an annual fee, but it certainly helps tip the math in favor of keeping both cards.
The information for the United Club Business has been collected independently by The Points Guy. The card details on this page have not been reviewed or provided by the card issuer.
Why the no-annual-fee Gateway Card stays in my wallet
The United Gateway Card isn’t a card I use for everyday spending, but that doesn't bother me.
Because it has no annual fee, there’s little downside to keeping this United personal card open and remaining eligible for the annual 5,000-mile bonus.
SEAN CUDAHY/THE POINTS GUY
Holding the Gateway Card also means I don’t have to keep paying the Explorer Card's annual fee simply to remain eligible for the anniversary bonus.
How the United Business Card does the heavy lifting
The United Business Card is where almost all of the value in this strategy comes from.
The annual 5,000-mile bonus is nice, but it’s the combination of ongoing perks that keeps me renewing year after year.
One of my favorite benefits is the two United Hotels statement credits (up to $50 each) I receive each cardholder year. I have a recurring calendar reminder to use both credits, and I usually book two separate one-night hotel stays to maximize the full $100 value.
I also appreciate having access to expanded MileagePlus saver award availability. Since I typically redeem my United miles for economy flights within the U.S. and to Mexico, I’ve been able to take advantage of lower award pricing that wouldn’t otherwise have been available.
This benefit is only available because I have the United Business Card. If I only held the United Gateway Card, I’d need to spend $10,000 on it each calendar year to unlock the same expanded award availability.
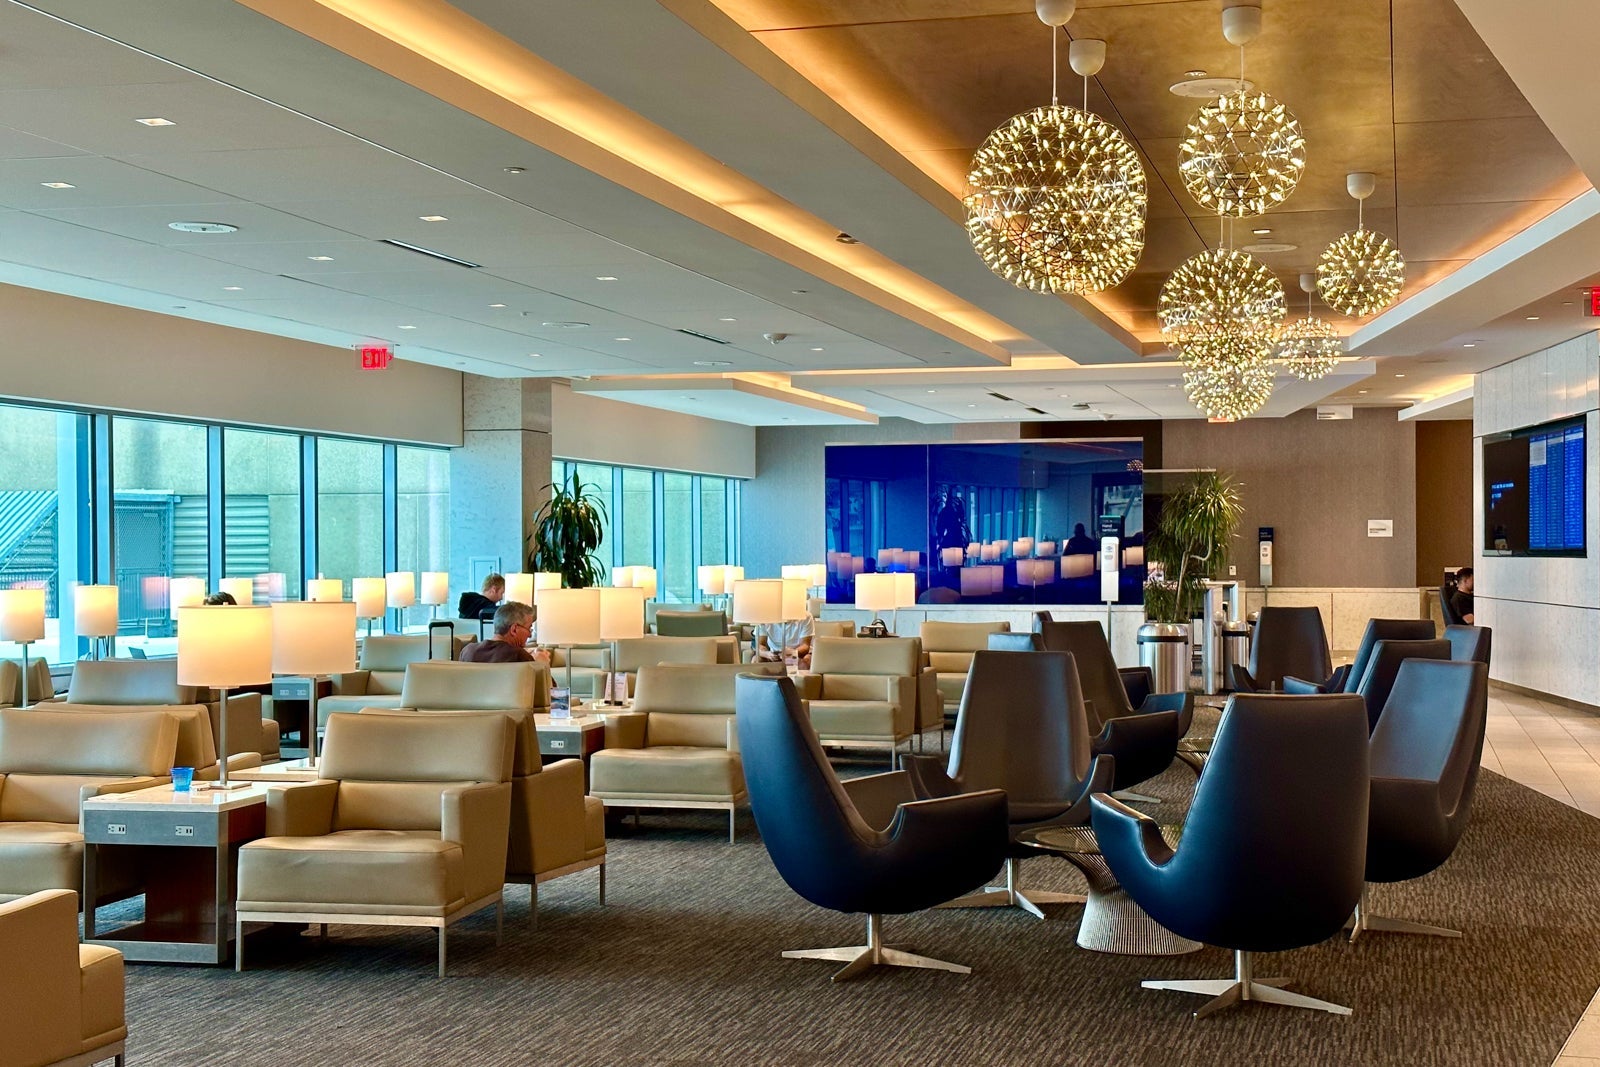
The two single-entry United Club passes I receive annually also come in handy. I used to like that they could be shared with anyone, but even after the benefit changed, I’ve still found them valuable while connecting through Houston’s George Bush Intercontinental Airport (IAH).
ZACH GRIFF/THE POINTS GUY
Another perk I use is Pay Yourself Back. Rather than paying the United Business Card’s annual fee out of pocket, I redeem MileagePlus miles to cover it. Since Pay Yourself Back lets me redeem miles at 1.5 cents apiece toward the annual fee, I’m getting more value than our valuation of 1.3 cents per mile.
I don’t get much value from some of the card’s other perks, like the credits for ride-hailing services and Instacart. That’s fine. I’d rather have a few benefits that fit naturally with the way I travel than feel like I need to go out of my way to justify keeping a card.
The overlooked value of airline-specific travel benefits
One lesson I’ve learned over the years is that you don’t need to be loyal to an airline to benefit from its cobranded credit card.
I only fly United a few times each year, but those trips are consistently better because I have the United Business Card.
CAROLINE TANNER/THE POINTS GUY
The free checked bag alone can save a meaningful amount if I’m traveling with luggage. (To receive your first checked bag free, you’ll need to pay for your ticket with your eligible United card or use that card to pay the taxes and fees on an award ticket.)
Priority boarding is another perk I enjoy, especially when overhead bin space starts filling up. (Unlike the free checked bag benefit, priority boarding doesn’t require you to pay with your eligible United card.)
Bottom line
At first glance, keeping both the no-annual-fee United Gateway Card and the United Business Card might seem like overkill, especially since United isn’t my primary airline. But together, they deliver enough value that I continue renewing them every June.
The Gateway Card quietly unlocks the annual 5,000-mile anniversary bonus at no ongoing cost, while the United Business Card provides the benefits I actually use, from United Hotels credits and expanded saver award availability to United Club passes and day-of-travel perks.
For my travel habits, it’s a combination that continues to earn its place in my wallet year after year.