The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Guides
When does it make sense to spend on a cobranded credit card?
Ethan's been a frequent flier for as long as he can remember, from studying abroad in Paris to moving to Shanghai after graduating college, where he served as TPG's eyes and ears for all things travel in the Asia-Pacific region. If you asked him where he wants to travel next he'd quote Anthony Bourdain and tell you "anytime I'm eating spicy noodles in a bowl, I'm happy."
Chris Nelson is a credit cards writer for TPG. He specializes in budget travel, hotels, earning elite status through minimal spending and redeeming points for maximum value.
also contributed to this story
August 18, 2024 • 9 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
Cobranded airline and hotel cards can be valuable in specific scenarios, such as acquiring hard-to-earn loyalty program miles or points.
These cards often provide brand-specific perks like free checked bags, priority boarding, anniversary nights or elite status, which may require booking directly with the card.
Hotel cards can offer higher rewards for stays at their respective chains compared to flexible points cards, potentially increasing overall value.
Using cobranded cards for small purchases can help prevent loyalty points or miles from expiring.
What to consider
Welcome bonuses on cobranded cards typically require meeting a minimum spend within a set timeframe.
Some perks, such as free checked bags or inflight discounts, only apply if travel is booked with the specific cobranded card.
Opportunity costs exist when directing spending to a single card, especially if chasing status or free night rewards.
What you'll miss from the article
A detailed comparison of when to use cobranded versus flexible points cards for maximizing travel rewards and benefits.
Generated by AI with support from our editorial team.
Update: Some offers mentioned below are no longer available. View the current offers here.
There are many benefits to using transferable points like Chase Ultimate Rewards points over using a specific airline or hotel currency, including flexibility, flexibility and... flexibility. You’ll get more value out of your points when you can pick which partner within a single alliance to transfer to and when you can explore alternate routings if there’s no award availability on your first-choice itinerary. And you can even decide whether to redeem your points for flights or hotels.
It should come as no surprise then that over half of TPG’s top travel rewards cards earn transferable bank points instead of individual airline or hotel points.
Still, that doesn’t mean there’s no value to be had in cobranded airline and hotel cards. While I put the majority of my spending on cards like the Chase Sapphire Reserve® and Chase Freedom Unlimited® (see rates and fees), there are a number of times when it makes sense to use a cobranded card over a more flexible alternative.
Here are the times I reach for a cobranded card rather than a transferable points earner.
Acquire hard-to-earn miles
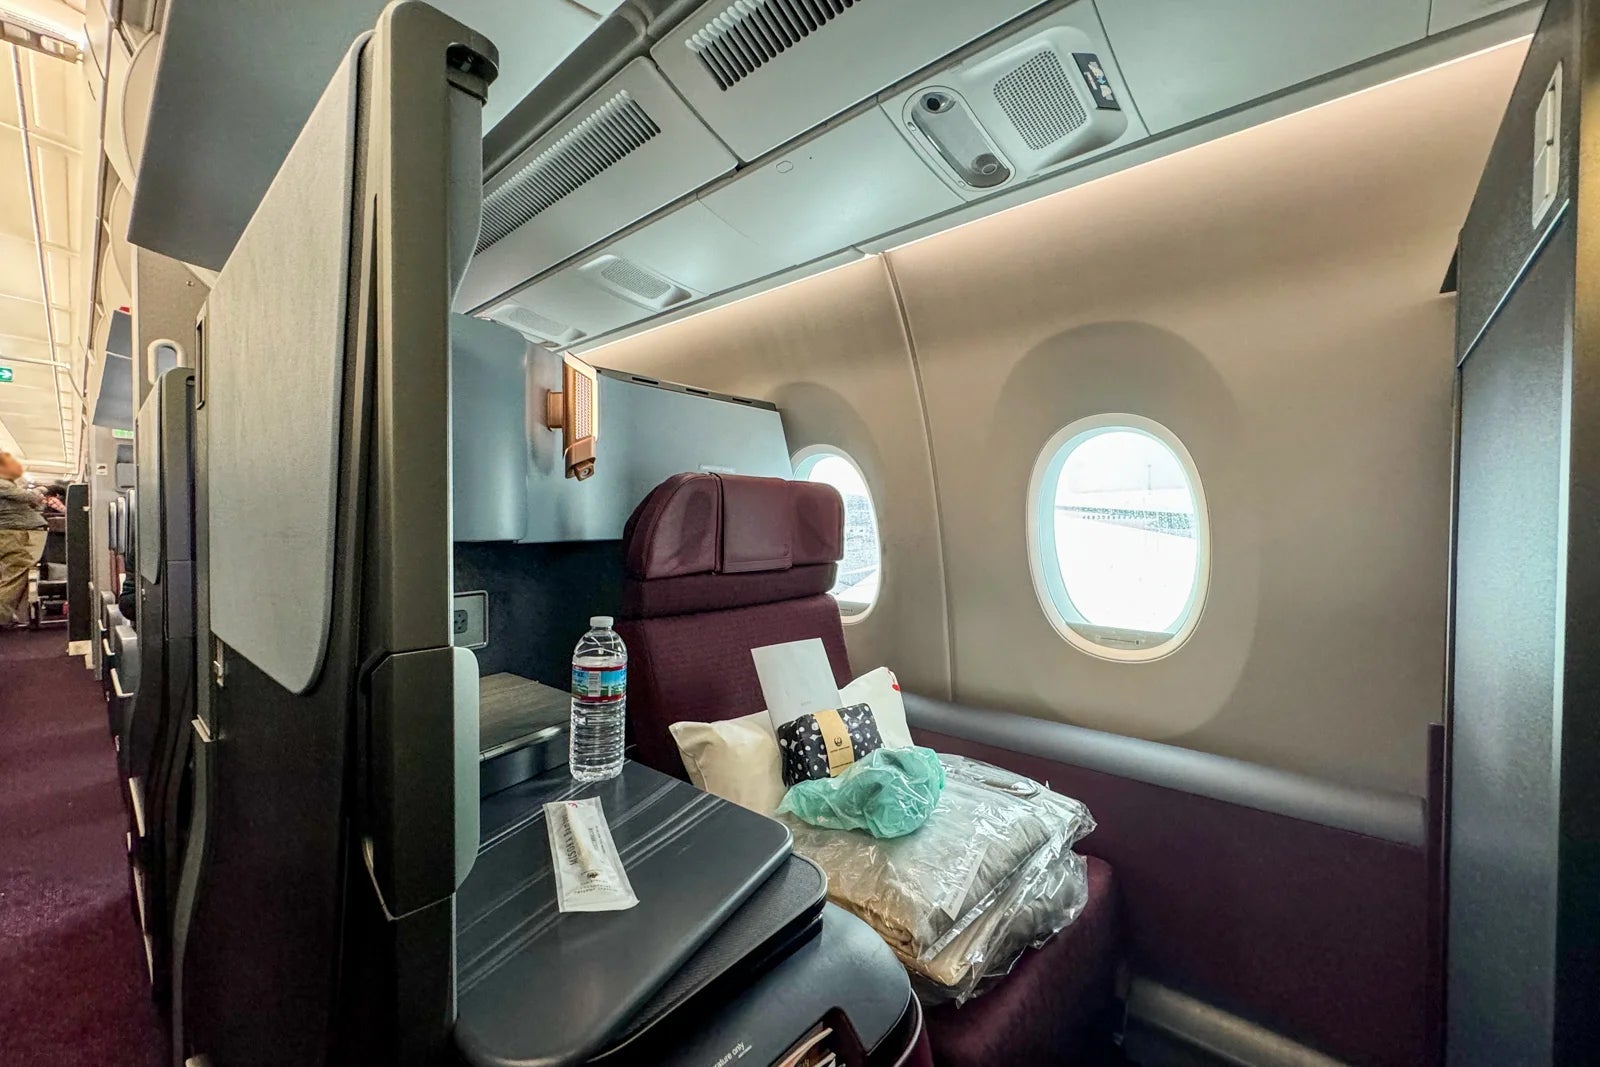
While Chase Ultimate Rewards points and Amex Membership Rewards points give you combined access to well over 20 hotel and airline transfer partners, not all miles can be easily earned from transferable cards. A prime example of this would be Alaska Mileage Plan miles. TPG's August 2024 valuations peg them at 1.55 cents each, just slightly below flexible Chase and Amex points (at 2.05 and 2 cents each, respectively). They earn this high mark because of the incredible sweet spot redemptions they can help unlock, including US-Asia in JAL or Cathay Pacific business class for only 75,000 miles one-way.
ERIC ROSEN/THE POINTS GUY
The only points that can be transferred to Alaska are Bilt Rewards Points and Marriott Bonvoy points, and you’ll come out ahead by spending directly on the Alaska Airlines Visa Signature® credit card. This card happens to be offering new applicants to earn 50,000 bonus miles plus buy one ticket, get one for just the taxes and fees ($0 fare plus taxes and fees from $23) after spending $3,000 or more on purchases within the first 90 days from account opening. This bonus is worth $750 based on TPG’s June 2025 valuations, which will get you more than halfway toward a luxury flight.
Speaking of Marriott points, they fall into a bit of a gray area in terms of terminology. While Marriott cards are “cobranded” (even though they are issued by Chase or Amex, they earn hotel points), those points are highly flexible and can be transferred to a whopping 45 airline partners. These cards are no longer as valuable as they used to be for everyday, non-bonus spending.
However, if you have a specific redemption in mind, like a dream flight in Emirates first class or an overwater bungalow somewhere far away, it might make sense to sacrifice an overall higher earning rate in order to earn the specific points you need.
In addition to annual fees, credit card issuers make a large chunk of their profits off interchange fees (swipe fees) and are constantly looking for ways to incentivize you to use your cards more. With cobranded cards, this often takes place in the form of welcome bonuses for new applicants.
ZACH GRIFF/THE POINTS GUY
Most cards offer a large welcome bonus if you spend a certain amount within a specified period of time. For example, the United℠ Explorer Card (see rates and fees) offers up to 60,000 bonus miles: Earn 50,000 bonus miles after spending $3,000 on purchases in the first three months from account opening. Plus, earn 10,000 bonus miles after adding an authorized user in the first three months from account opening.
This bonus is worth up to $810 (including the points from adding an authorized user), based on TPG's May 2026 valuations and can get you a Polaris business-class ticket to select destinations around the world.
If you have a large purchase coming up, you can open a new cobranded credit card and use the purchase to help you earn a stash of points or miles that could take years to earn through everyday spending.
Outside of welcome bonuses, one of the best reasons to keep cobranded credit cards open long-term is because of the brand-specific perks they offer. For cobranded hotel cards, this might be an anniversary-free night or elite status. For cobranded airline cards, these can include free checked bags and priority boarding with the airline. Many cobranded cards link these perks directly to your loyalty account, but for some, you actually need to charge your travel to the card to earn them. United, for example, generally won’t honor the first free checked bag that comes with the United Explorer card if you book your ticket with a different card.
Of the several airline credit cards that offer discounts on inflight purchases, all of them specify that you must use that specific card to receive the discount. A 20-25% discount handily beats the return you’d get from a flexible travel card like the Chase Sapphire Reserve, which comes out to 6.15% (3 points per dollar worth 2.05 cents each).
Another example of a good time to put spending on a cobranded card is when you need to spend to reach a free night reward or elite status. For example, the Hilton Honors American Express Surpass® Card offers a free night after spending $15,000 in a calendar year.
GRAND WAILEA, A WALDORF ASTORIA RESORT/HILTON
Keep in mind that this is a large chunk of spending, and for most of us, it would require careful planning throughout the year to reach. It’s important to consider the opportunity cost of putting that spend on a single card, and if you’re chasing status, how much value you’ll get if you aren’t able to qualify organically.
Most airlines cobranded credit cards offer measly double points on flights booked with that specific airline, and you can easily do better with a card like the Chase Sapphire Reserve or The Platinum Card® from American Express. But cobranded hotel credit cards offer much higher earning rates, and can end up being the most valuable way to book your stays.
To keep things simple, I’ll compare all of these cards to the Chase Sapphire Reserve and its 6.15% (3 points per dollar) return on hotel bookings (it offers 3 points per dollar on travel, which includes hotels). The chart below shows how rewarding hotel credit cards can be when used for stays at that specific chain.
Credit Card
Points Earned at Hotels (% return)
Hilton Honors American Express Aspire Card
14 points per dollar (8.4%)
World Of Hyatt Credit Card (see rates and fees)
4 points per dollar (6.8%)
IHG One Rewards Premier Credit Card (see rates and fees)
10 points per dollar (5%)
Marriott Bonvoy Boundless® Credit Card (see rates and fees)
6 points per dollar (5%)
Returns are calculated based on TPG's August 2024 valuations.
By not using the Sapphire Reserve, you would be sacrificing some perks like travel insurance, but the increased rewards might make it worthwhile. Even the Marriott cards (all of which earn 6 points per dollar at Marriott hotels) can be a better value than the Sapphire Reserve. While TPG 's August 2024 valuations peg those points at 0.6 cents each, it’s easy to get several times more value than that if you’re transferring to airline partners for premium cabin rewards.
One problem with travel rewards (that’s especially difficult for frequent international travelers) is keeping track of small mileage balances in different accounts and preventing them from expiring.
JUSTIN PAGET/GETTY IMAGES
Most airlines simply require you to have some kind of mileage activity every 1-2 years (terms vary by program), and so when someone’s miles are about to expire, I’ll often hear people suggest transferring the minimum 1,000 points from Chase or Amex to keep the miles active. This certainly works, but if you aren’t planning on using the miles anytime soon, you’ve just wasted 1,000 valuable miles that could have been used elsewhere.
A far simpler option, if you have the right cobranded card, is to simply walk into a convenience store and buy a pack of gum or any other small purchase. You’ll earn a few miles on your statement, which should be enough to reset the expiration date on your loyalty account. Just keep an eye on your calendar and make sure your statement will close/your miles will post before the expiration date.
Bottom line
We don't recommend building your rewards strategy on a cobranded card foundation, but there are scenarios where they can be useful even outside of the welcome bonus. You’ll find more generous perks and bonus categories with flexible points cards, but cobranded cards can offer uniquely valuable rewards at the specific airline or hotel that issues them. If you have loyalty to a single airline or hotel, engaging directly with their individual credit cards can help increase your returns.
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.