The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Guides
Can you pay your student loans with a credit card?
Emily Thompson specializes in beginner content as a credit cards editor. She taps into her prior experience as a high school English teacher to help others demystify credit scores and unlock experiences that credit card rewards can make possible.
Ariana has been writing about points and miles for almost a decade. She previously served as editor at FlyerTalk, Frugal Travel Guy and NerdWallet while running her own travel blog, PointChaser.
also contributed to this story
January 13, 2025 • 14 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.
Editorial note: This is a recurring post, regularly updated with new information and offers.
Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
Paying federal student loans directly with a credit card is not allowed, but third-party services can facilitate such payments for a fee.
Some private lenders may accept credit card payments, though most do not; third-party services may be an alternative.
Using a credit card for student loan payments can help meet spending requirements for certain bonuses, but fees may outweigh the benefits if not pursuing a bonus.
Selecting a card with strong rewards can maximize value, especially for large loan balances.
What to consider
Third-party payment services typically charge a fee, so calculate whether rewards earned will offset this cost.
Not all private lenders accept credit card payments; always confirm with your lender before proceeding.
Points or miles earned through these payments may have varying redemption values, with some worth more when transferred to travel partners per TPG's September 2026 valuations.
What you'll miss from the article
A detailed comparison of top cards for student loan payments, including which features and reward types best suit different borrower needs.
Generated by AI with support from our editorial team.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Student loans are a burden that many Americans have.
If you're currently repaying your student loans or if you're a recent grad facing the start of repayments, you may wonder if you can pay your loans with a credit card. Since student loan payments are often large, they could, in theory, be an easy way to hit spending requirements for welcome offers.
So, can you pay your student loans off with a credit card? Here's what you need to know.
You do not have the option to pay your federal loans directly with a credit card, but you can use a card to pay through a third-party payment service. These third-party services often charge a fee for each transaction, so read the fine print before picking a specific service.
FREEMIXER/GETTY IMAGES
A third-party service to pay student loans with a credit card is a great option if you're trying to meet a credit card spending requirement. If you earn a substantial credit card sign-up bonus, it's well worth paying a small fee. But if you're not working on a bonus, calculate whether the rewards you'll earn are valuable enough to offset the additional fee of paying your student loans with a credit card.
You'll need to check with your specific lender if you want to pay a private student loan with a credit card. While certain lenders will let you pay your private student loans with a credit card, most do not. If your lender doesn't accept a credit card as a form of payment, look into using a third-party service.
Benefits of using your credit card for your student loans
If your loans are through a private lender that allows you to pay them with a credit card, take advantage of the opportunity to earn some serious rewards. According to Forbes, the average borrower owes $35,210 in student loan debt.
If you paid that balance with a 2% cash-back card, for example, you would earn $704 in cash-back rewards.
HISPANOLISTIC/GETTY IMAGES
Using a points-earning card can be worthwhile, although you'll want to earn more than 1 point per dollar if you can.
The Capital One Venture Rewards Credit Card earns 2 miles per dollar spent on all purchases. If you paid off a $35,210 student loan with the Venture Rewards, you'd earn 70,420 miles. Those points are worth $1,303, according to TPG's September 2026 valuations.
Find out your offer and see if you are eligible for as high as 50,000 bonus points after spending $5,000 on purchases within the first three months of card membership. (Welcome offers vary, and you may not be eligible for an offer.)
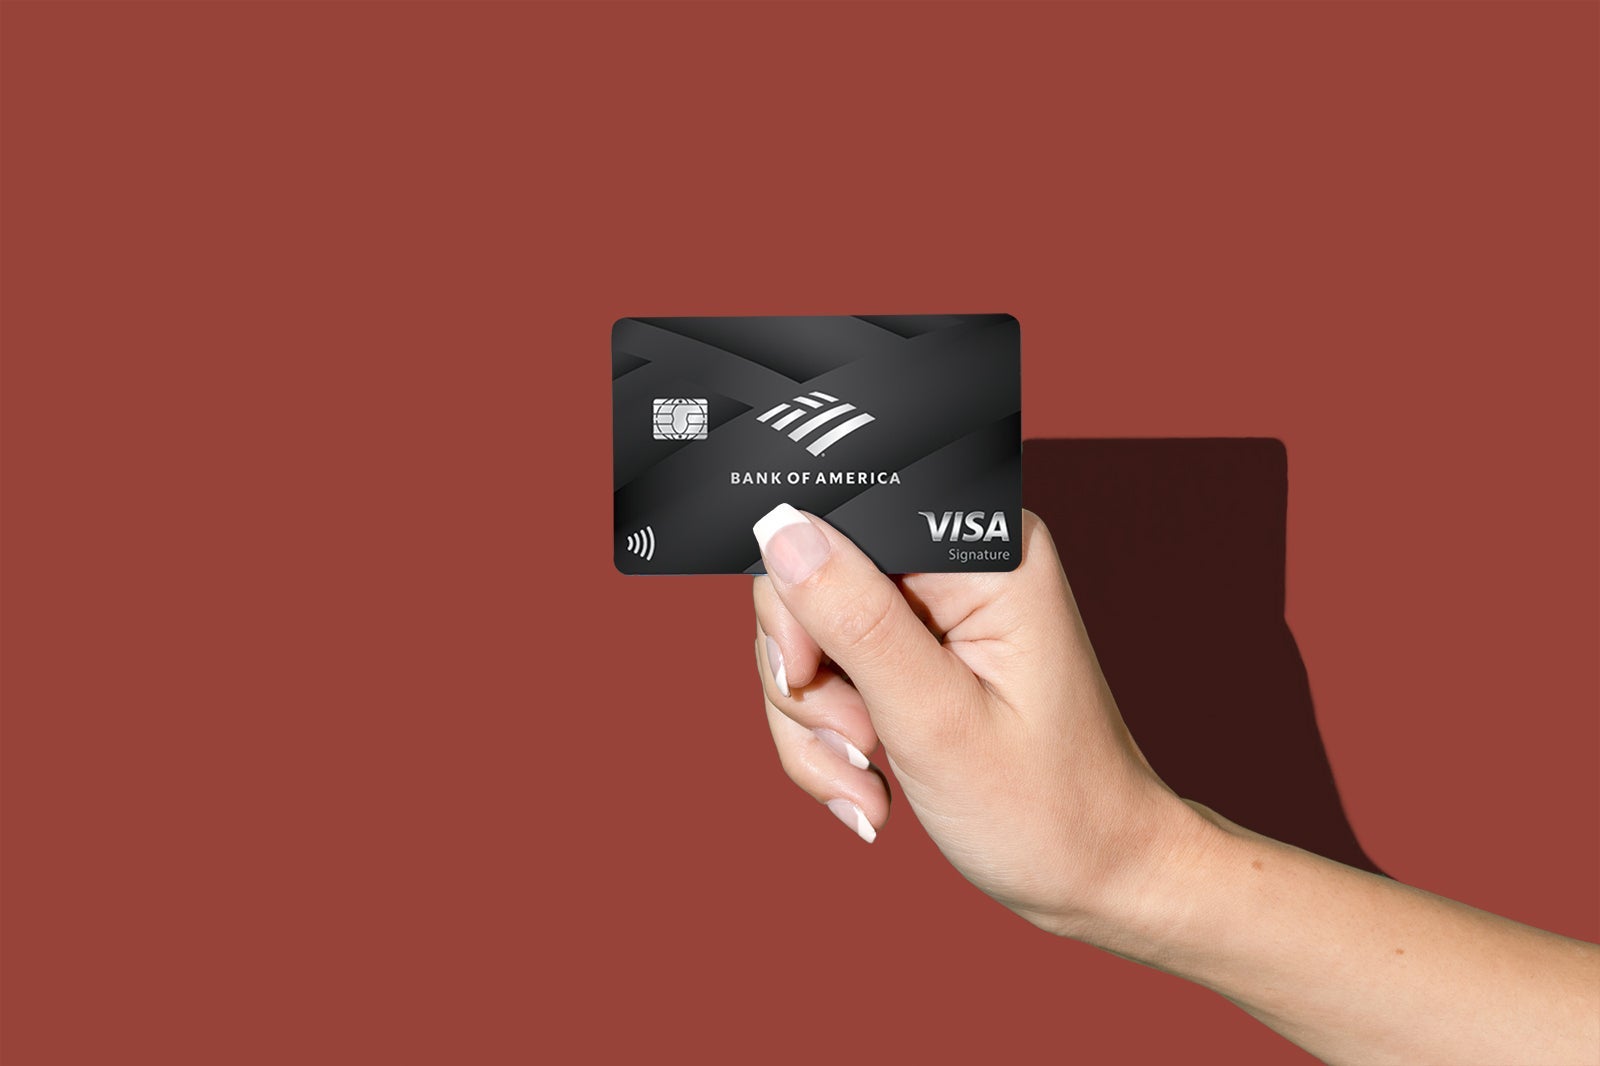
If you're already a Bank of America customer, the Bank of America Premium Rewards card may be a good fit for you.
Annual fee: $95
Sign-up bonus: Earn 60,000 bonus points after you make at least $4,000 in purchases in the first 90 days of account opening.
Rewards rates: 2 points per dollar spent on travel and dining; 1.5 points per dollar spent on all other purchases
THE POINTS GUY
Why we like it: The Bank of America Premium Rewards credit card is a great option for paying your student loans because it earns 1.5 points per dollar spent. If you're a Bank of America Premium Rewards® member, you'll earn 25%-75% more bonus points, meaning your student loan payments could earn you up to 2.62 points per dollar spent. You can redeem points at a rate of one cent each, making the 60,000-point welcome bonus worth $600.
While this card does carry a $95 annual fee, it's completely offset by an up to $100 airline incidental statement credit issued annually. Cardholders also qualify for up to $100 Global Entry/TSA PreCheck credit every four years, which is rare for a card with a $95 annual fee. Credits like these are normally offered by cards with annual fees of $450 and up, which is why the Bank of America Premium Rewards Credit Card is unique.
The Chase Freedom Unlimited is a great choice if you already own a card that earns Ultimate Rewards points or if you plan on opening one in the future.
Annual fee: $0
Sign-up bonus: Earn a $200 bonus after spending $500 on purchases within the first three months from account opening.
Rewards rates: Earn 5% cash back on travel booked through Chase Travel℠, 3% back at drugstores and on dining at restaurants (including takeout and eligible delivery services) and 1.5% back on all other purchases.
Blue Business Plus Credit Card from American Express
If you own your own business or have a side hustle, opening the Amex Blue Business Plus can give you another option to pay your student loans.
Annual fee: $0 (see )
Welcome offer: Find out your offer and see if you are eligible for as high as 50,000 bonus points after spending $5,000 on purchases within the first three months of card membership. (Welcome offers vary, and you may not be eligible for an offer.)
Rewards rates: 2 points per dollar on all spending, up to $50,000 per calendar year (then 1 point per dollar)
THE POINTS GUY
Why we like it: If you're looking for maximum rewards on student loan payments, the Blue Business Plus card is an excellent choice. The card earns 2 points per dollar on all spending, up to $50,000 per calendar year (then 1 point per dollar). The downside is that you may not be able to use an American Express card for student loan payments as readily as a card from one of the other major issuers. This is also a business card, and while you may qualify for a business card without realizing it, it's not ideal for everyone.
That said, the card does not carry an annual fee and can be useful for other expenses, such as shipping, advertising and business utilities.
If you're willing to pay the annual fee, the Capital One Venture Rewards is a great choice for paying your student loans.
Annual fee: $95
Sign-up bonus: Earn 75,000 bonus miles after spending $4,000 on purchases within the first three months from account opening, plus receive a $300 credit to use on hotel and vacation rentals booked through Capital One Travel in the first cardholder year.
Rewards rates: 5 miles per dollar on hotels, vacation rentals and rental cars booked through Capital One Travel and 2 miles per dollar on all other purchases
THE POINTS GUY
Why we like it: With a simple reward structure, the Capital One Venture Rewards card earned its place on TPG's list of best travel credit cards. The card earns 2 miles per dollar spent across all purchases. You can get great value by transferring your miles to airline partners and hotel loyalty programs. The high flat-rate earn rate and flexible redemption options make the Capital One Venture Card a great option for student loan payments.
The Citi Double Cash card, like the Capital One Venture Rewards, has a simple earnings structure that makes it appealing for paying off your student loans.
Annual fee: $0
Sign-up bonus: Earn $200 cash back after you spend $1,500 on purchases in the first six months of account opening.
Rewards rates: Earn 2% cash back on every purchase (1% when you buy and 1% when you pay your bill). Plus, earn 5% total cash back on hotel, car rentals and attractions booked on the Citi Travel℠ portal.
THE POINTS GUY
Why we like it: If you're looking for 2% cash back and the ability to convert your rewards to ThankYou points for no annual fee, look no further than the Citi Double Cash Card. The card earns 2% cash back on all purchases — 1% when you make a purchase and another 1% when you pay your card off every billing cycle. That's not only a great incentive to pay off your balance (something you should be doing regardless), but 2% is also a solid payout if you want to earn cash back on your student loan payments.
What's better than 2% cash back on your student loan payments? Two Citi ThankYou points per dollar spent. If you have a card in your wallet that earns Citi ThankYou points, you can convert your cash back rewards from the Citi Double Cash to Citi ThankYou points.
Not to be confused with the Capital One Venture Rewards, the Capital One VentureOne Rewards has no annual fee, making it a good option for anyone who can't afford an annual fee on their credit card.
Annual fee: $0
Sign-up bonus: Earn 20,000 bonus miles after spending $500 on purchases in the first three months from account opening.
Rewards rates: Earn unlimited 1.25 miles per dollar on every purchase.
THE POINTS GUY
Why we like it: If you want to earn Capital One miles on your student loan payments without paying an annual fee, the Capital One VentureOne Rewards Credit Card is a great option. The card earns a flat 1.25 miles per dollar spent on all purchases.
Not many rewards cards with no annual fee offer a sign-up bonus, which makes this card's 20,000 bonus miles unique. You can redeem these miles for $200 in travel purchases or transfer them to one of Capital One's 15-plus airline and hotel partners for even better value.
Picking the right card to pay your student loans depends on several factors. Most importantly, find out whether your student loan lender accepts credit cards and what the terms are. If you can use a card, consider the rewards you'll earn by paying your student loans with a credit card and whether you'll get enough value from your rewards to offset any fees the payment will incur.
For rates and fees of Blue Business Plus card, click .
Earn 75,000 bonus miles after spending $4,000 on purchases within the first three months from account opening, plus receive a $300 credit to use on hotel and vacation rentals booked through Capital One Travel in the first cardholder year.