The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Guides
Here’s how my husband and I maximize each dollar we spend on household expenses
TPG's director of travel content Eric Rosen has used points and miles to visit some of the world's most remote corners, including swimming with whale sharks off Western Australia's Ningaloo Coast, exploring the wilds of Botswana's Okavango Delta and tasting the high-altitude wines of Argentina's Mendoza region.
August 12, 2026 • 12 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
A couple shares their approach to maximizing rewards by coordinating their everyday spending across multiple rewards cards.
They focus on simplicity by assigning specific cards to major expense categories like groceries, dining, gas, travel and utilities.
Their strategy involves using cards with strong rewards or benefits for each category, periodically adjusting based on their current points goals.
They emphasize that a practical, easy-to-follow plan is more effective than chasing every possible point.
What to consider
The couple regularly revisits their card assignments to align with evolving rewards goals and balances.
Some expenses, like rent, may require additional tools or cards to optimize rewards, which they plan to address in the future.
Certain cards offer added protections or credits for specific categories, such as mobile phone coverage or travel statement credits.
What you'll miss from the article
A detailed breakdown of how to assign cards to each spending category and adapt your household rewards strategy over time.
Generated by AI with support from our editorial team.
When I got married last year, of course, I was excited about the wedding and gathering all our friends and loved ones. And I was even more excited about our honeymoon in Australia, which we’re finally taking this month after a year of planning.
But, as the points and miles nerd that I am, one of the aspects of married life I was most excited to start was combining our finances and supercharging our rewards through a simple everyday spending strategy. I was ready for two-player mode, as we like to say at TPG.
After all, we had to earn a lot of points to underwrite the aforementioned honeymoon (three weeks chasing kangaroos and swimming with whale sharks is expensive, mates!).
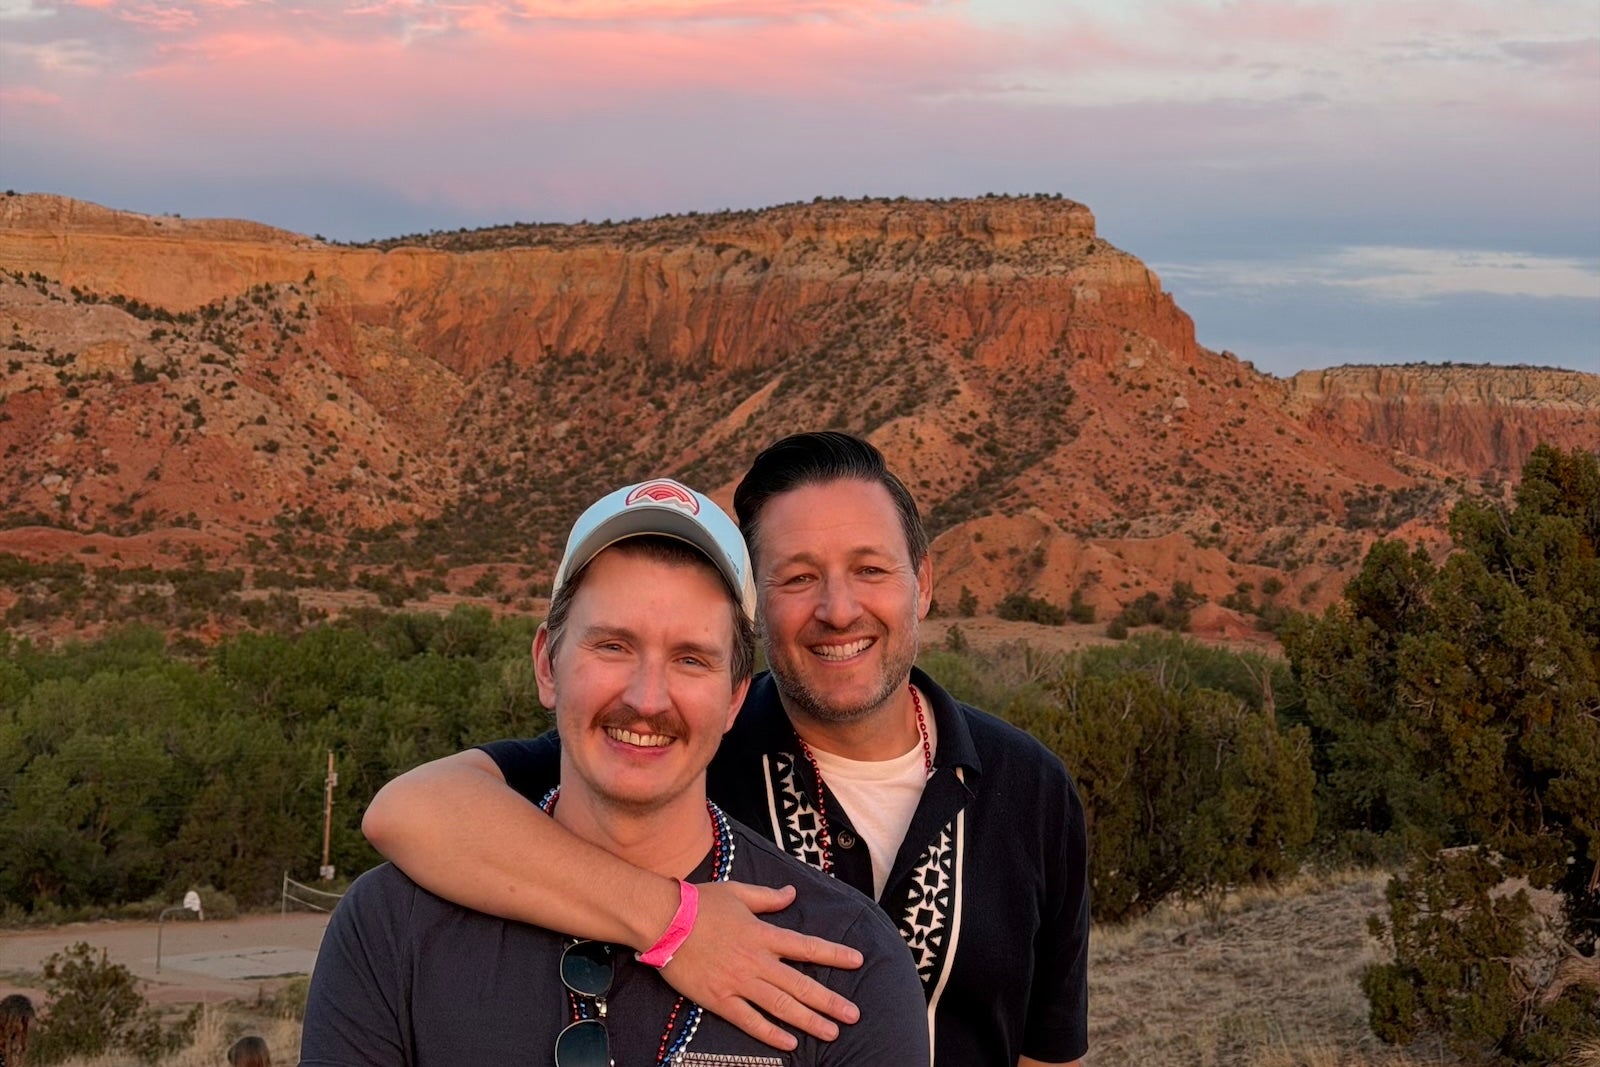
ERIC ROSEN / THE POINTS GUY
Our goal wasn't to earn the absolute maximum number of points on every purchase. It was to build a system simple enough that we'd actually follow every day.
Rather than drive my husband slightly batty by nonchalantly switching cards in and out of his wallet, we sat down to strategize which rewards credit cards each of us should carry and which we should use for our major spending categories.
Here's how we divided up our spending, the cards we each carry and the simple strategy that's helped us maximize nearly every dollar we spend.
Groceries are one of our biggest monthly expenses, so we wanted a card that consistently earns bonus rewards.
Right now, almost all of our supermarket spending goes on my husband's Citi Strata Premier. He added me as an authorized user, so we both carry the same card and earn 3 ThankYou Rewards points per dollar at supermarkets while building one shared points balance.
Before we were together, I put all of my grocery spending on my American Express Gold Card since it earns 4 points per dollar on up to $25,000 of purchases at U.S. supermarkets each calendar year (then 1 point per dollar after).
But we already have a healthy Membership Rewards balance, so we're focusing on Citi ThankYou Rewards for now. Once we hit our goal, we'll likely switch our grocery spending back to the Amex Gold.
We love eating out, especially in a city with as many incredible restaurants as Los Angeles has. And when we travel, we love exploring new destinations through their dining culture.
We have so many cards that offer solid spending bonuses on dining, so our strategy is a little more nuanced.
Most of the time, we focus on Chase Ultimate Rewards, thanks to the versatility of the points, their transfer partners and valuable features likePoints Boost when booking travel through the Chase Travel℠ portal.
For the most part, we put our dining expenses on his Chase Sapphire Preferred to earn 3 points per dollar spent and to track all our dining together in one place, as we do with our monthly expenses.
Every so often, if I want to switch to earning Citi ThankYou Rewards, we swap in the Citi Strata Premier since it also earns 3 points per dollar at restaurants.
When I’m on my own and looking to pad our Amex Membership Rewards account, you can be sure I charge meals to my American Express Gold Card since it earns 4 points per dollar on up to $50,000 in purchases at restaurants worldwide each calendar year (then 1 point per dollar).
Occasionally, if we're trying to top off our American Airlines balance or Marriott Bonvoy account, we'll temporarily switch to one of those cobranded cards instead.
Another of our main expenses is our joint mobile and home internet bill, which comes to around $350 per month. For that, I actually turn to my main business credit card, the Ink Business Preferred.
First, the card earns 3 points per dollar on up to $150,000 per calendar year in combined purchases across several categories, including internet, cable and phone services, so I know I’m getting a solid rate of return on those.
The other factor I consider, though, is that the Ink Business Preferred provides some of the best cellphone protection of any credit card.
When you pay your monthly bill with the card, you and eligible employees (my husband counts as an authorized user) can get up to $1,000 per claim for damage or theft of our cellphones. We are limited to three claims per 12-month period and there’s a $100 deductible per instance, but that’s a small price to pay. And luckily, we’re not accident- or theft-prone enough to max this out.
Believe it or not, we don't spend much on travel since we frequently use points for flights and hotels. When we do pay cash, I usually reach for my Chase Sapphire Reserve because it earns 8 points per dollar spent on all purchases booked through Chase Travel and 4 points per dollar on flights and hotels booked direct.
Plus, the Chase Sapphire Reserve has up to $500 in annual statement credits (split into two up-to-$250 credits) for stays of at least two nights booked through The Edit and a one-time up to $250 credit for prepaid stays at select hotel brands (available through Dec. 31).
That said, I also make sure to use my Capital One Venture X Rewards Credit Cardfor at least one trip, thanks to its $300 annual travel credit for bookings made via the Capital One Travel portal. Whatever I spend over that, it earns 10 miles per dollar spent on hotels and rental cars booked through Capital One Travel and 5 miles per dollar spent on flights and vacation rentals booked through Capital One Travel.
We have a lot of nonbonus categories each month that start to add up as well, including things like utilities, renters’ insurance, car insurance, dry-cleaning, food and toys for our dog and more.
This is the key missing element in our strategy. We’re renters in a family-owned building, so we just write a personal check every month to pay for our housing.
That said, we’re overdue to dive into the Bilt universe and start maximizing our earning on rent. Adding a Bilt card will likely be the next evolution of our strategy, but we're waiting until we're ready for another card application.
Although my husband and I carry more than 30 credit cards between us, the work of maximizing our everyday household expenses to earn the most points (and the points most valuable to us) is actually quite simple.
We identified our biggest spending categories, assigned one to two primary cards to each and revisit the plan every few months depending on which rewards currency we're trying to build.
That's the biggest lesson I'd pass along.
Your own everyday spending strategy can be as simple or as complex as you want. You don't need dozens of cards or a mathematically perfect setup to maximize your household spending. You just need a strategy that's simple enough that you'll actually stick with it. And don't be afraid to change things up when needed.
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.