The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Credit card writer Danyal Ahmed is an avid traveler, averaging about 100,000 aeronautical miles per year. He regularly applies that knowledge and his expertise in credit cards to his role as a credit card writer at TPG.
July 26, 2025 • 10 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.
Editorial note: This is a recurring post, regularly updated with new information and offers.
Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
Purchasing a car is a significant expense, but using a credit card for part or all of the payment can help you earn valuable rewards.
Some cards are better suited for large purchases due to flexible spending limits or higher rewards rates at certain thresholds.
Not all dealerships accept credit cards for full payment, and some may impose transaction fees or set maximum charge limits.
Using a credit card for a car purchase can also help meet minimum spending requirements for new cardholder offers.
What to consider
Dealerships vary in their willingness to accept credit cards and may limit the amount you can charge or impose transaction fees.
Carrying a high balance from a large purchase can impact your credit score due to increased credit utilization.
Introductory 0% interest offers can provide flexibility, but paying off the balance quickly is recommended to avoid interest charges.
What you'll miss from the article
A detailed comparison of which card types maximize rewards for car purchases and practical tips for negotiating dealership payment policies.
Generated by AI with support from our editorial team.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Purchasing a car is a huge expense. And unfortunately, it's usually a diminishing investment that loses value over time, starting with the moment you drive it off the lot.
The silver lining here is that a car purchase can earn you some serious rewards if you put some or — in rare cases — all of the cost on a credit card to earn valuable points and miles. A large purchase, such as a car down payment, is also a great way to meet the minimum spending requirements for a credit card welcome offer.
If you're considering purchasing a car with a credit card, here are some cards to consider and key things to be aware of.
Best cards for buying a car
Choosing the right card can earn you more rewards on your car purchase, making the process more rewarding. Here are some of the best cards to use when buying a car or making a down payment.
American Express Platinum: Best for large purchases
Annual fee: $895 (see )
Welcome offer: New cardmembers can find out their offer and see if they're eligible for as high as 175,000 bonus points after spending $12,000 on eligible purchases on the new card in the first six months of card membership. Welcome offers vary, and you may not be eligible for an offer.
THE POINTS GUY
Earning rate on car purchases: 1 point per dollar spent
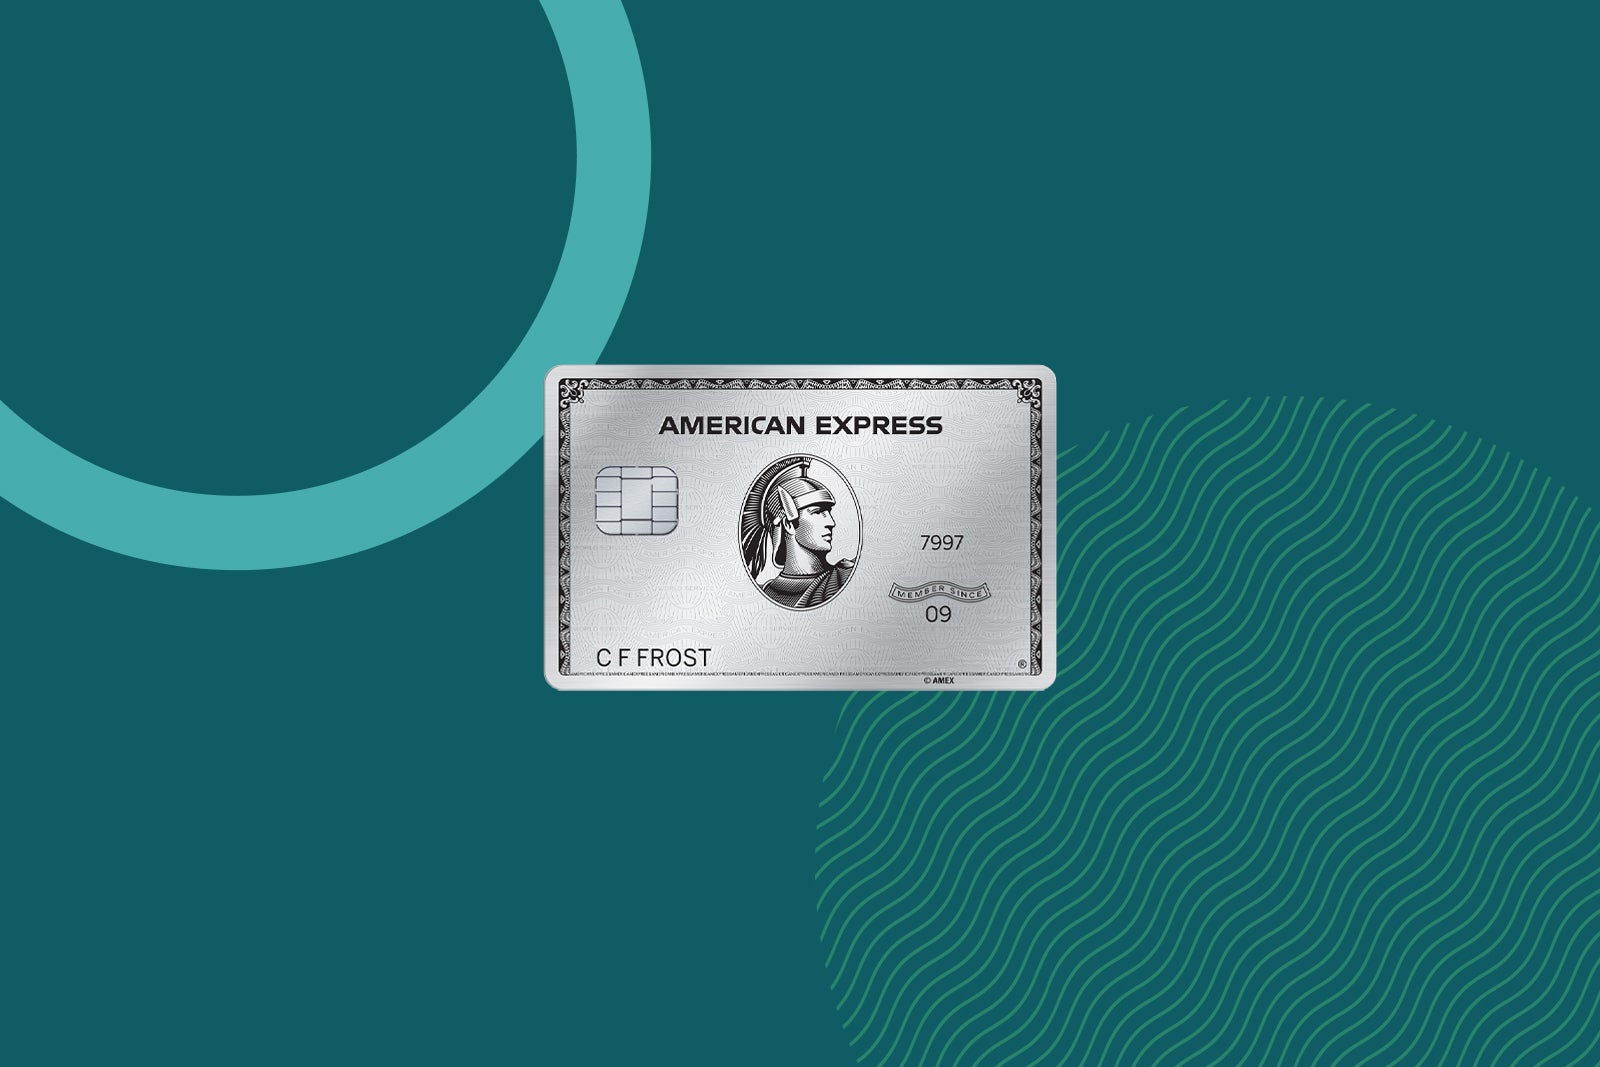
Why it's a good choice:The Platinum Card® from American Express is an excellent choice because it has , making it ideal for a large purchase like a new car. No preset spending limit doesn't mean unlimited funds, but if you're looking to make a large down payment or even purchase an entire car, this card is a better option than one with a fixed credit limit.
The amount you can spend adapts based on factors such as your purchase, payment and credit history.
The Amex Platinum requires the balance to be paid in full each month, but with Pay Over Time, cardmembers can carry a balance (though it accrues interest). If purchasing a car, it's recommended you pay off the card as soon as possible and avoid losing value you gained from earning a nice sum of points.
American Express Business Platinum: Best for big spenders
Annual fee: $895 (see )
Welcome offer: Find out your offer and see if you're eligible for as high as 300,000 bonus points after spending $20,000 on purchases in the first three months of card membership. Welcome offers vary, and you may not be eligible for an offer.
THE POINTS GUY
Earning rate on car purchases: 2 points per dollar spent on eligible U.S. purchases over $5,000 (on up to $2 million in purchases per calendar year)
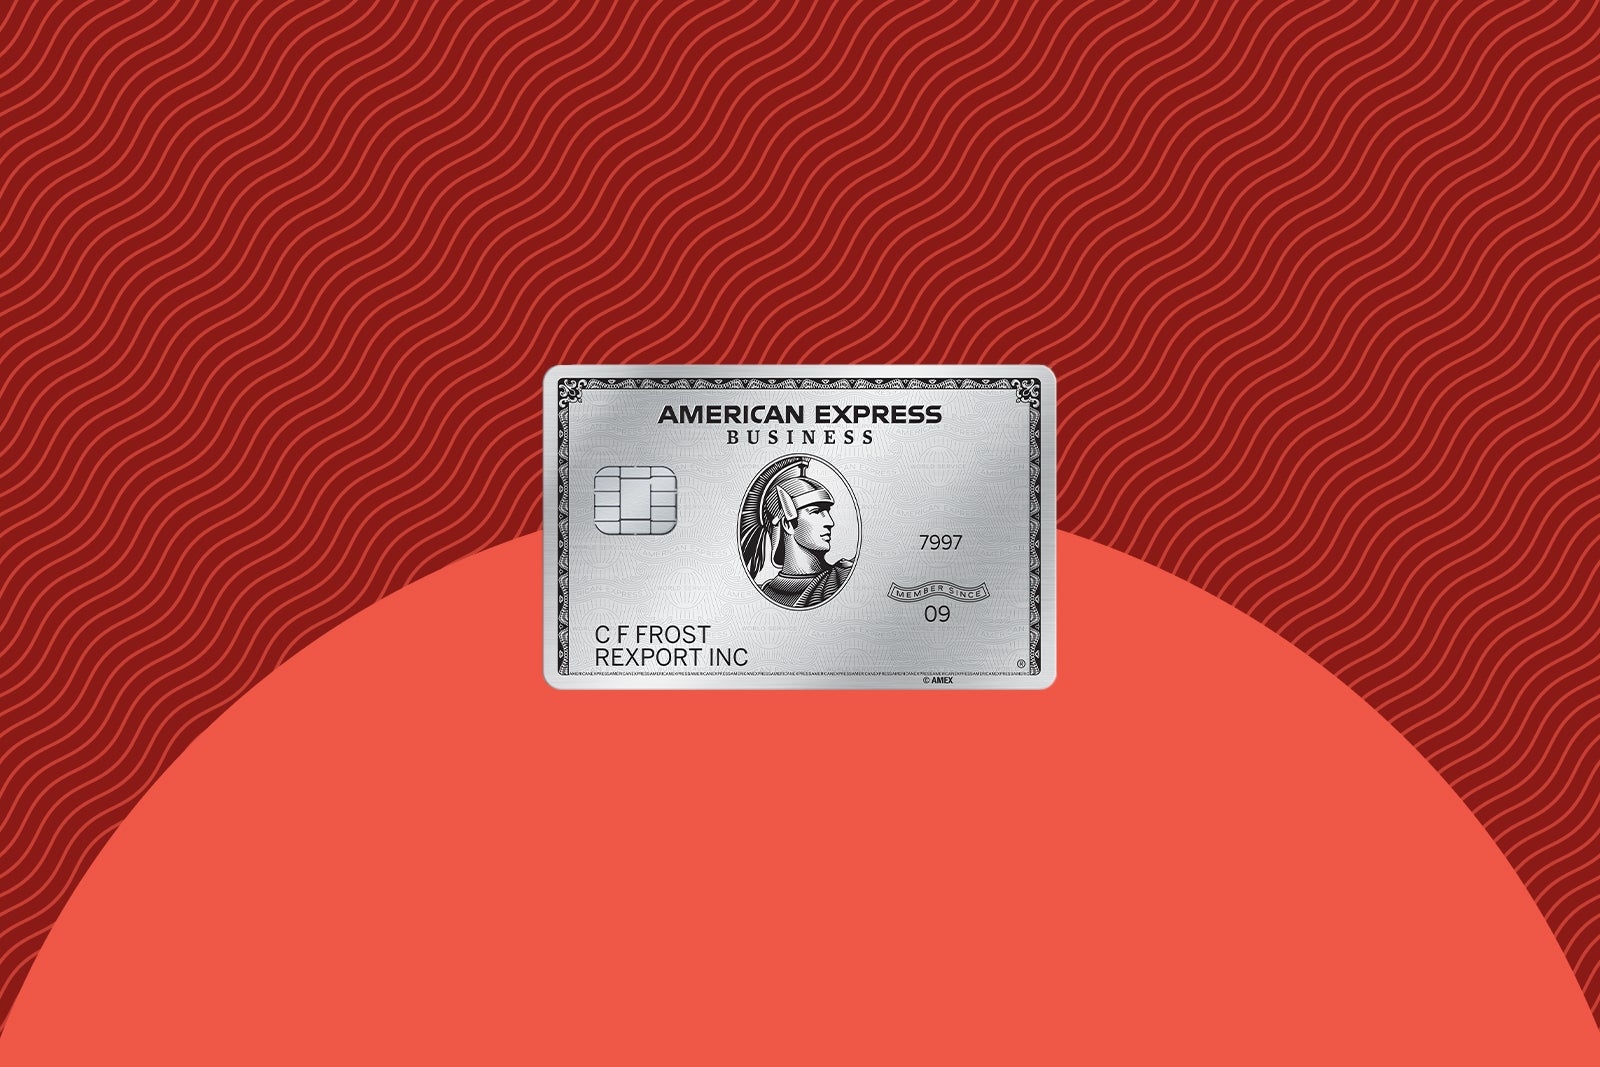
Why it's a good choice:The Business Platinum Card® from American Express is similar to the personal Amex Platinum and has no preset spending limit. This card is another ideal choice as it earns 2 points per dollar spent on purchases of $5,000 or more. A $10,000 down payment on a new car would earn you 20,000 Amex points, worth $400 according to TPG's July 2025 valuations. The amount you can spend adapts based on factors such as your purchase, payment and credit history.
To make the most of this card, make sure the car purchase or down payment is at least $5,000; otherwise, you're better off using a no-annual-fee card that provides rewards on nonbonus categories, such as The American Express Blue Business Cash® Card (see ), which earns 2% cash back (on the first $50,000 spent each calendar year, then 1%).
American Express Blue Business Plus: Best for maximum points
Annual fee: $0 (see )
Welcome offer: Find out your offer and see if you are eligible for as high as 50,000 bonus points after spending $5,000 on purchases within the first three months of card membership. (Welcome offers vary, and you may not be eligible for an offer.) Plus, receive a 0% introductory annual percentage rate for 12 months from the date of account opening (after that, the APR will be a variable rate from 16.99%-28.74%; see ).
THE POINTS GUY
Earning rate on car purchases: 2 points per dollar on the first $50,000 spent each calendar year (then 1 point per dollar)
Why it's a good choice: For a card with no annual fee, The Blue Business® Plus Credit Card from American Express earns an impressive 2 points per dollar spent on the first $50,000 in purchases each calendar year (and 1 point per dollar thereafter).
Since the card comes with a 0% introductory APR, it can be easy to make a purchase with it and pay it off within 12 months to avoid interest charges (variable APR from 16.99%-28.74% after).
Unlike the two Platinum cards, this one comes with a preset limit, so be sure you can cover the cost of the car or down payment before purchasing.
Chase Freedom Unlimited: Best for earning cash back
Annual fee: $0
Welcome offer: New cardholders can earn a $200 bonus after spending $500 on purchases within the first three months from account opening.
THE POINTS GUY
Earning rate on car purchases: 1.5% cash back
Why it's a good choice: The Chase Freedom Unlimited® (see ) can be a great way to earn cash back — and turn it into valuable points.
A $15,000 car purchase would earn you $225 cash back. However, if you have an Ultimate Rewards points-earning credit card, you can maximize your cash back by turning it into 22,500 points, which are worth $461, according to TPG's July 2025 valuations.
Cardholders also receive a 0% introductory APR on purchases and balance transfers for 15 months from account opening. After the introductory period, a variable APR of 18.49%-27.99% applies. This can give you time to pay off your car purchase without interest.
Citi / AAdvantage Platinum Select: Best for American Airlines loyalists
Annual fee: $0 introductory annual fee the first year, then $99
Welcome bonus: For a limited time, earn 80,000 bonus miles after spending $3,500 on purchases in the first four months from account opening.
THE POINTS GUY
Earning rate on car purchases: 1 mile and 1 Loyalty Point per dollar spent
Why it's a good choice: Although the Citi® / AAdvantage® Platinum Select® World Elite Mastercard® (see ) only earns 1 mile per dollar spent, the real benefit for American Airlines frequent flyers is that the card earns 1 Loyalty Point per dollar spent. If a dealership allows you to put a large down payment or the entire purchase on the card, you could earn a nice chunk of Loyalty Points toward elite status.
I put the down payment for my last car purchase on my wife's Citi / AAdvantage Platinum because she was a few thousand Loyalty Points short of Executive Platinum status, and this purchase helped her secure it.
Although buying a car with a credit card may seem easy, here are some things to keep in mind.
What is the maximum amount I can put on a credit card?
The maximum amount you can put on a credit card depends on the car dealership. You may be able to negotiate how much it can charge, as this was the case for me. I was able to negotiate with my local dealership to increase the maximum allowed charge on a credit card from $5,000 to $8,000.
Do all dealerships accept credit cards?
If you're looking to purchase a car entirely on a credit card, it's recommended to call ahead and speak to a finance manager at the dealership. Some may not accept credit cards for the entire vehicle purchase, while others will be happy to accept them. In my experience, a down payment when financing or leasing a car is usually payable with a credit card, provided it's within the allowed limit of charges.
What dealerships charge fees for using credit cards?
This varies by dealership, and while some can charge a fee for a credit card transaction, other dealerships may choose not to charge any fee. When I put a down payment on my car last year, the dealership did not charge me a transaction fee, even after I negotiated charging a higher amount of the payment to my credit card. The easiest way to find out is by calling dealerships in your area, but that may require more effort on your part.
MASKOT/ GETTY IMAGES
Can I pay a portion of the price with my credit card?
Again, this depends on the dealership, as some may only allow you to use a credit card for a down payment toward a lease or financed vehicle. Others may allow you to put the entire purchase price of the car on a credit card.
Do I need to pay my full balance?
If you make the car purchase on a card that is offering a 0% interest rate, then you can pay the minimum balance per month (usually 1% of the entire balance) or make enough of a payment to pay off the entire card within the promotional period. If you put the charge on a card that charges interest, your best course of action is to pay the balance in full to avoid interest.
Does buying a car with a credit card affect my credit score?
When purchasing a car on your credit card, your credit utilization will surely increase, and this can negatively affect your credit score. To keep your utilization down, pay off the balance as soon as possible, and you’ll minimize the long-term impact.
Bottom line
Purchasing a car with a credit card can be a great way to earn a large sum of points, miles or cash back. It’s also an easy way to meet the minimum spending requirement on a new card.
Just keep in mind that not all dealerships will allow you to charge the full purchase price — many only accept credit cards for down payments — so be sure to check ahead of time.
For rates and fees of the Amex Platinum, click . For rates and fees of the Business Platinum, click . For rates and fees of the Blue Business Plus, click . For rates and fees of the Amex Blue Business Cash, click .