The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Katie Genter is a digital nomad who has traveled full time since June 2017. She writes and edits stories about points and miles, and loyalty programs, often letting her personal experiences color these stories.
December 1, 2019 • 15 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
Low-cost airlines offer fewer services but can be enhanced with the right credit card strategies.
There are four main card types to consider: airline-specific cards, cards with travel protections, cards with high returns at airlines, and cards offering credits for incidental airline fees.
The best card for low-cost carriers depends on your travel habits, frequency and whether you value perks like free bags, priority boarding or travel protections.
Some cards require you to select your preferred airline for incidental fee credits, and benefits may only apply when booking directly with the airline.
What to consider
Eligibility for certain card perks may depend on booking directly with the airline and using the card for the purchase.
Incidental fee credits often require separate transactions from airfare and may need you to pre-select your airline each year.
Some offers mentioned in the article are no longer available.
What you'll miss from the article
A detailed comparison of card types and which benefits matter most for different low-cost airline travelers.
Generated by AI with support from our editorial team.
Update: Some offers mentioned below are no longer available. View the current offers here.
Low-cost carriers generally provide fewer services at a lower cost than legacy airlines like American, Delta and United. But just as select credit cards can help make your experience better when flying in basic economy on legacy airlines, certain credit cards can also make your experience better when flying on low-cost carriers.
In general, there are four types of credit cards to consider when booking travel on a low-cost airline:
Cobranded airline credit cards that get you perks with a specific airline (and may require you to book with your card to get the perks)
Credit cards that provide travel protections when you book flights using the car
Which type of card is best? As you'll see in this guide, this depends on your specific situation -- including the other cards you currently hold. So let's get started.
Cobranded Airline Cards
Each of the six main low-cost airlines in the US offers at least one cobranded card. Here are the details of some of these cards, including current sign-up bonuses, annual fees and benefits. Note that estimated returns described below are based on TPG's valuations.
Southwest Rapid Rewards Priority Credit Card
Sign-up bonus: Earn a Companion Pass® through 2/28/23 plus 30,000 points after you spend $5,000 on purchases in the first three months. You aren't eligible for this product if you have a current Southwest Rapid Rewards Credit Card or have received a new cardmember bonus for this card in the past 24 months (excluding business card and employee credit card products)
Annual fee: $149
Earning rate: 3x points spent on Southwest purchases, 2x points on Rapid Rewards hotel and car partners, 2x points on local transit and commuting (including rideshare), 2 points on internet, cable, phone services and select streaming, then 1x point per dollar on everything else.
Benefits: 7,500 bonus points after cardmember anniversary; four Upgraded Boardings per year; $75 Southwest annual travel credit; 25% back on inflight drinks and Wi-Fi; ability to earn tier qualifying points toward A-List status by spending on the card; points don't expire as long as the card account is open; no foreign transaction fees. See the full card review for more details.
Takeaway: If you can use the full annual travel credit and 7,500 points on each anniversary, this card easily provides more value each year than its annual fee. If you're looking for a cobranded Southwest card with a lower annual fee, there are a few other options including the Southwest Rapid Rewards Plus Credit Card ($69 annual fee) and Southwest Rapid Rewards Premier Credit Card ($99 annual fee).
Sign-up bonus: 40,000 bonus points after you spend $1,000 on purchases in the first 90 days and pay the annual fee. This one-time offer is valid for first-time cardmembers with new accounts only. TPG values this bonus at $520.
Annual fee: $99
Earning rate: 6x on JetBlue purchases (7.8% return); 2x at restaurants and grocery stores (2.6% return); 1x on all other purchases (1.3% return)
Benefits: 5,000 bonus points after each account anniversary (TPG values at $65); free first checked bag for you and up to three companions on the same reservation when you use your JetBlue Plus card to purchase the tickets; 50% inflight savings on cocktails and food purchases; 10% award-flight redemption bonus; Mosaic benefits after spending $50,000 or more on purchases each calendar year; annual $100 statement credit after purchasing a JetBlue Vacations package of $100 or more with your JetBlue Plus Card; no foreign transaction fees. See the full card review for more details.
Takeaway: The strong earning on JetBlue flights and free first checked bag can make this card appealing even if you only fly JetBlue infrequently. JetBlue charges $30 for a checked bag, so if you fly just four one-way trips each year and need to check a bag on each trip, you'd save $120 before even considering the other card benefits. Obviously, the potential savings are even more if you travel frequently or with companions.
Sign-up bonus: 15,000 bonus points -- equal to $150 off your next Allegiant trip -- after you make $1,000 or more in purchases within the first 90 days of account opening.
Annual fee: $59
Earning rate: 3x on Allegiant purchases (3% return); 2x on dining (2% return); 1x on all other purchases (1% return)
Benefits: Priority boarding; one free beverage each time you fly Allegiant; buy-one-get-one-free airfare anytime you use your card to purchase a vacation package from Allegiant with four or more hotel nights or seven or more rental car days on the same itinerary; points don't expire as long as your card account is open; no foreign transaction fees
Take Away: Since this card doesn't provide any free baggage allowance, the main benefit for most cardholders will be the buy-one-get-one-free airfare on select vacation packages. It's certainly possible to get far more than the $59 annual fee in value from this benefit, but only if you actually book eligible vacation packages from Allegiant.
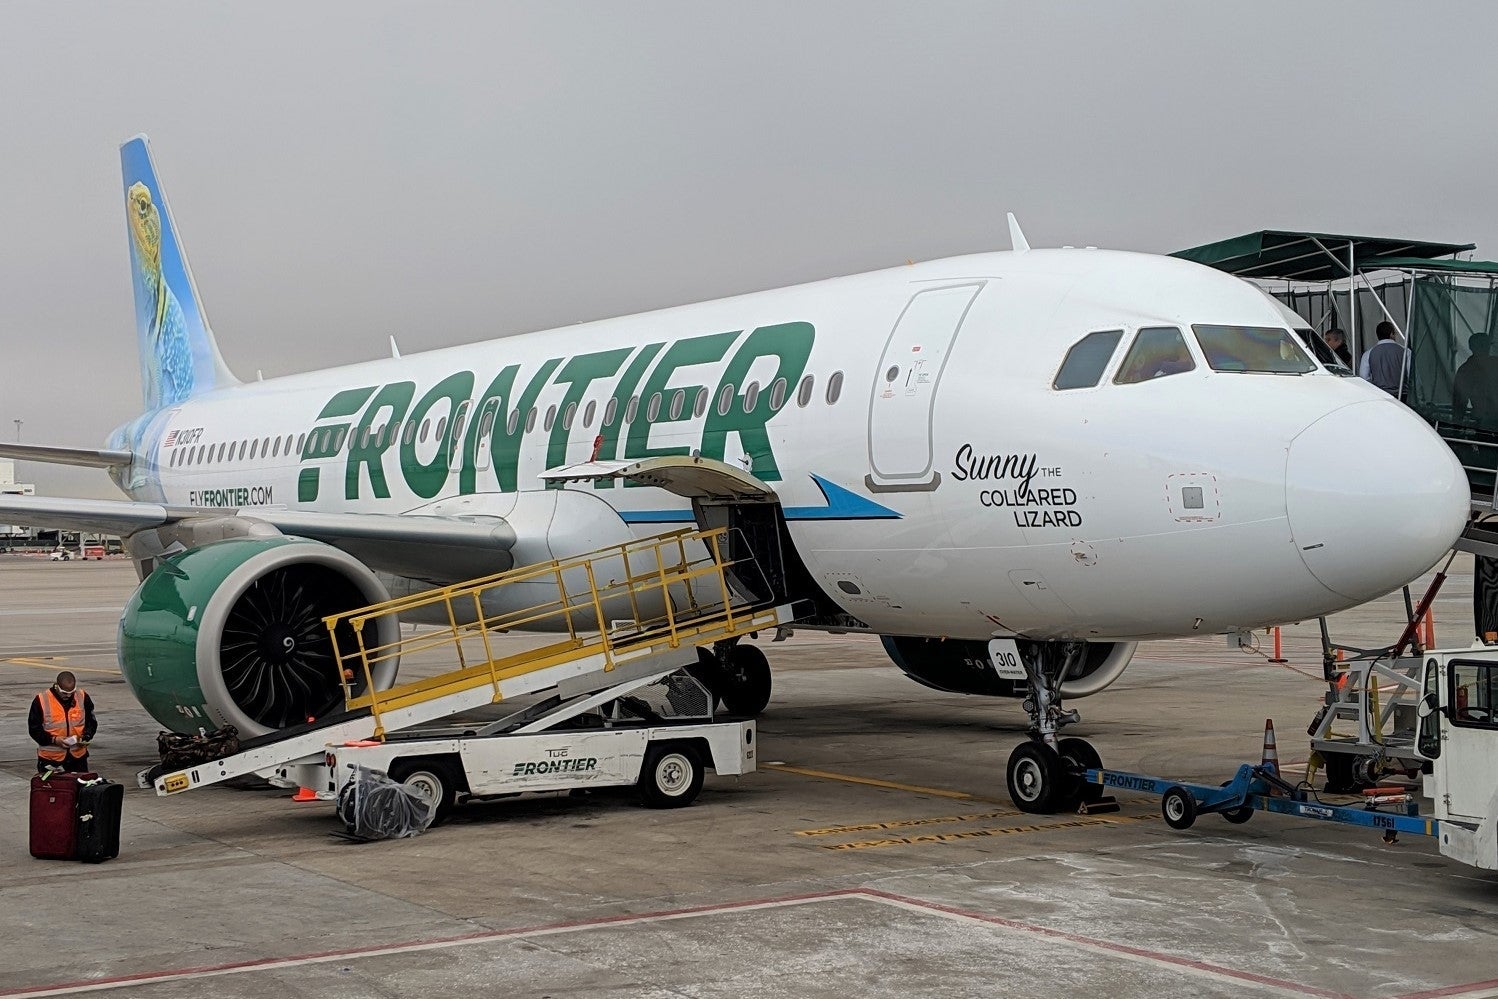
Frontier Airlines World Mastercard
(Photo by JT Genter/The Points Guy)
Sign-up bonus: 40,000 bonus miles after spending $500 on purchases in the first 90 days and paying the annual fee. This offer is available to new cardmembers only. TPG values this bonus at $440.
Annual fee: $79
Earning rate: 5x on purchases at flyfrontier.com (5.5% return); 3x at restaurants (3.3% return); 1x on all other purchases (1.1% return)
Benefits: Spend to elite status by earning 1 Qualifying Mile with every $1 spent on purchases; unlock Family Pooling to share miles; earn a $100 Flight Voucher after every account anniversary if you spend $2,500 or more in the previous cardmember year; keep Frontier miles from expiring by making at least one purchase every six months; waiver of award redemption fee when you book an award ticket and use your Frontier Mastercard to pay the related taxes and fees; Priority Zone 2 boarding for the primary cardmember; no foreign transaction fees. See our card overview for more details.
Takeaway: This card doesn't automatically provide any baggage benefits, so it is mainly useful for families who want to pool their miles and frequent Frontier travelers who can get value from being able to earn Frontier elite status -- including Elite100k Status that provides “the WORKS” bundle for the primary cardmember and up to eight traveling companions on the same reservation -- through spending on the card.
Sign-up bonus: 15,000 bonus miles after your first purchase plus 15,000 bonus miles after making at least $500 in purchases within 90 days of your account opening. TPG values the full 30,000-mile bonus at $120.
Annual fee: $0 for the first year, then $59
Earning rate: 2x on all purchases (0.8% return)
Benefits: Exclusive access to Spirit's lowest flight-redemption levels (such as 2,500 miles for off-peak flights under 1,250 miles); 5,000 anniversary bonus miles (TPG values at $20) when you spend at least $10,000 in purchases annually; no foreign transaction fees
Takeaway: This card will not improve your onboard experience and the earning rate is rather abysmal, based on TPG's valuation of Spirit miles at 0.4 cents each. But as Mommy Points notes: You can earn a one-way flight with just $1,250 of spending and get up to 12 off-peak flights from the sign-up bonus. For travelers who can take advantage of Spirit's off-peak flights, having this card can make sense -- but for most travelers, it will likely be difficult to justify the $59 annual fee.
Sign-up bonus: 35,000 points -- worth $350 in travel with Sun Country -- when you spend $1,500 or more in the first three billing cycles
Annual fee: $69
Earning rate: 3x on Sun Country purchases (3% return); 2x on gas and groceries (2% return); 1x on everything else (1% return)
Benefits: Priority boarding and one free premium drink per flight; 50% off seat selections and first bag for you and your travel companions when traveling on the same itinerary; 10,000-point anniversary bonus worth $100 when you spend $10,000 or more during each 12-billing-cycle period; points don't expire as long as your card account is active; no foreign transaction fees
Takeaway: Your first checked bag or a carry-on bag normally costs $30 on Sun Country -- although it may be cheaper if you purchase it while booking your ticket -- so you can expect to save about $15 per person per one-way flight. If you fly five or more one-way trips per year with Sun Country -- or fewer if you travel with family or friends on the same itinerary -- then having this card can make sense.
Don't sleep in the airport. Select credit cards will reimburse you for your hotel, meals and other expenses if you're stranded overnight while in transit. (Photo by SamuelBrownNG/Getty Images)
Chase Sapphire Preferred Card ($95 annual fee; see full card review)
Ink Business Preferred Credit Card ($95 annual fee; see full card review)
Paying for your airfare -- or even just the taxes and fees on an award ticket -- with a card that offers travel protections can pay off big-time. My husband and I once got a $1,000 reimbursement after being stranded in Nagoya, Japan for multiple days because of a typhoon.
Cards With High Returns
Low-cost carriers should, theoretically, be low cost. So you probably don't need to be overly concerned with earning bonus points or miles on your tickets. Instead, you might want to use a card that provides benefits while flying such as a free checked bag or earlier boarding, or a card that provides useful travel protections.
The Platinum Card® from American Express (5x on flights purchased directly from the airline or at Amex Travel for a 10% return on up to $500,000 in purchases per calendar year; $695 (See Rates & Fees) annual fee (see full card review)
The Business Platinum Card® from American Express -- 5x on flights purchased through Amex Travel for a 10% return; $695 (See Rates & Fees) annual fee (see full card review)
Citi® Prestige Card -- 5x with airlines and travel agencies for a 8.5% return; $495 annual fee (see full card review)
And, here are two cards with annual fees under $100 that feature a solid return on airfare and other travel expenses:
Ink Business Preferred Credit Card -- 3x on the first $150,000 spent in combined purchases in select categories, including travel, each account anniversary year for a 6% return; $95 annual fee (see full card review)
Citi Premier® Card -- 3x points per dollar on airfare, hotels, gas stations, restaurants and supermarkets for a 5.1% return; $95 annual fee (see full card review)
The information for the Citi Prestige Card has been collected independently by The Points Guy. The card details on this page have not been reviewed or provided by the card issuer.
Cards With Airline Fee Credits
Finally, if you have a card that offers an airline-incidental-fee credit, using this card to pay for incidentals such as baggage fees, seat selection fees and onboard snacks can be a good way to take advantage of the credit. Here are some of the cards that offer this type of credit:
Hilton Honors American Express Aspire Card -- up to $250 (see full card review)*
The Business Platinum Card® from American Express -- up to $200 (see full card review)*
The Platinum Card® from American Express -- up to $200 (see full card review)*
Bank of America® Premium Rewards® credit card -- up to $100 (via statement credit) (see full card review)
*Enrollment required for select benefits.
The information for the Hilton Aspire Amex card has been collected independently by The Points Guy. The card details on this page have not been reviewed or provided by the card issuer.
Note that the airline-incidental-fee transaction must be separate from airline ticket charges to be reimbursed. The positive of this is that you can use a card that provides airline benefits, travel protections and/or solid earnings for the airfare and another card for the incidental fees. But the downside of this is that you'll need to purchase these extras after completing your airfare purchase -- which may mean you'll pay a slightly higher fee for baggage or seat selection than if you'd purchased them at the same time as your airfare.
For the American Express cards with an airline-incidental-fee credit, there's an additional complication: You'll need to select the airline on which you wish to use the credit and you'll only be reimbursed for eligible incidental fees charged by your selected airline. You can make this section online or over the phone soon after getting your card, and then you can change your choice once each year in January.
Bottom Line
There isn't one best card for flying on low-cost carriers. Instead, the best card depends on how you travel and what you need. This includes what carriers you're likely to fly, how much flexibility you have in your schedule, how often you travel, whether you usually travel alone or as a group, what other credit cards you currently have and whether you generally purchase independent travel insurance that will cover you if your flight or baggage is delayed.
Did this guide help you determine what card is best for you on low-cost carriers? If so, tell us what card works best for you!
For rates and fees of the Amex Platinum, please click here. For rates and fees of the Amex Business Platinum, please click here. For rates and fees of the Hilton Aspire Card, please click here.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.