The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Guides
Why the Amex Gold is the perfect ‘in-between’ card
Featured image by KSENIYA OVCHINNIKOVA/GETTY IMAGES
Emily Thompson specializes in beginner content as a credit cards editor. She taps into her prior experience as a high school English teacher to help others demystify credit scores and unlock experiences that credit card rewards can make possible.
February 14, 2025 • 8 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.
Editorial note: This is a recurring post, regularly updated with new information and offers.
Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
Travelers often struggle to find a card that balances premium perks with manageable costs, as most options are either high-fee premium cards or lower-perk mid-tier cards.
Premium cards provide extensive benefits like lounge access and travel credits but require significant effort to maximize their value and come with high annual fees.
Mid-tier cards offer broader earning categories and lower annual fees but lack luxury perks such as elite status or lounge access.
One card stands out as an appealing middle-ground, offering robust dining and supermarket benefits, valuable monthly credits and a fee that sits between typical mid-tier and premium cards.
What to consider
Maximizing monthly credits for dining, rideshares and select restaurants is key to offsetting the cost of this in-between card, but enrollment may be required for some benefits.
Those who do not frequently use eligible merchants or live in areas without certain partners may find it challenging to fully utilize all available credits.
This card does not provide luxury travel perks like elite status or lounge access, which are common with premium cards.
What you'll miss from the article
A detailed comparison of how this in-between card stacks up against both premium and mid-tier options, including real-world scenarios for maximizing its credits and benefits.
Generated by AI with support from our editorial team.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
If you're looking for a new card, you may find yourself struggling to justify a hefty annual fee on a premium card but dissatisfied with the lower number of perks on most mid-tier cards. It can feel impossible to find a perfect "in-between" card.
And you're not imagining it. There aren't many cards that fit into the area between the two tiers. However, one card offers the perfect "in-between" balance — the American Express® Gold Card.
With a $325 annual fee (see rates and fees), the Amex Gold has a lower annual fee than premium cards, but benefits and bonus categories that outshine most mid-tier cards, the Amex Gold may be the "just right" card you're looking for.
Annual fee: $395 for the Venture X, $795 for the Sapphire Reserve and $895 for the Amex Platinum (see rates and fees)
Welcome bonus: $1,388 or more in value, according to TPG's February 2025 valuations. However, generally not much higher than mid-tier welcome offers.
ZACH GRIFF/THE POINTS GUY
Earning: Over 2% returns on select travel or other common bonus categories, according to TPG's February 2025 valuations.
Pros of premium cards: These cards have long lists of perks and benefits like elite status, airport lounge access, travel credits and insurance, as well as increased bonus-earning categories. If you can maximize the value of these benefits, you'll find that the perks far outweigh the cost of an annual fee for a premium card.
Cons of premium cards: Premium cards have high annual fees and somewhat limited bonus-earning categories. Since they don't have substantially higher welcome offers than other cards, you need to maximize a premium card's perks and benefits to justify paying its annual fee.
This means that in addition to the higher out-of-pocket cost, carrying one of these cards incurs the higher mental burden of keeping track of and redeeming all its perks.
Verdict: A premium card is a worthwhile investment for anyone who travels enough to maximize the card's benefits. However, you may find that the annual fee and work required to maximize the card's benefits are too high for your current lifestyle.
They have a reasonable annual fee and decent welcome bonuses and earning structures, but the perks they offer are fewer and less valuable than those on premium cards.
WESTEND61/GETTY IMAGES
Annual fee: $95 for both the Sapphire Preferred and the Venture Rewards
Welcome bonus: $1,688 or more in value, according to TPG valuations
Earning: 3.7%-10.3% returns on common bonus categories such as travel, dining, groceries and gas, according to TPG's February 2025 valuations.
Pros of mid-tier credit cards: These cards generally offer a solid welcome bonus and a relatively low annual fee. They also have broader bonus-earning categories like groceries, dining and streaming, giving you more opportunities to earn on your everyday spending.
Cons of mid-tier credit cards: You won't receive special treatment from elite status or strut into airport lounges with these cards.
Verdict: Mid-tier cards are great for anyone who wants to earn on everyday expenses, keep their annual fee costs low and still have some perks like travel insurance. However, anyone looking for luxury travel perks may find these cards lacking.
With a $325 annual fee and a list of perks that fall squarely between "mid-tier" and "premium," the Amex Gold is a TPG favorite for a reason.
Annual fee: $325
Welcome bonus: Find out your offer and see if you are eligible for as high as 100,000 Membership Rewards points after spending $8,000 on purchases within the first six months of card membership. Welcome offers vary and you may not be eligible for an offer.
Since Amex has a once-per-lifetime rule for welcome offers, it's important to ensure you get the best offer possible.
Earning: This card is a foodie's dream come true, earning 4 points per dollar at restaurants worldwide (up to $50,000 per calendar year, then 1 point per dollar) and 4 points per dollar at U.S. supermarkets (on up to $25,000 in purchases per calendar year, then 1 point). It also earns 3 points per dollar on flights booked directly with airlines and through amextravel.com or the Amex Travel App™, 5 points per dollar on prepaid hotels and other eligible purchases booked through amextravel.com or the Amex Travel App, 2 points per dollar on car rentals and cruises booked on amextravel.com or the Amex Travel App and 1 point per dollar on all other purchases.
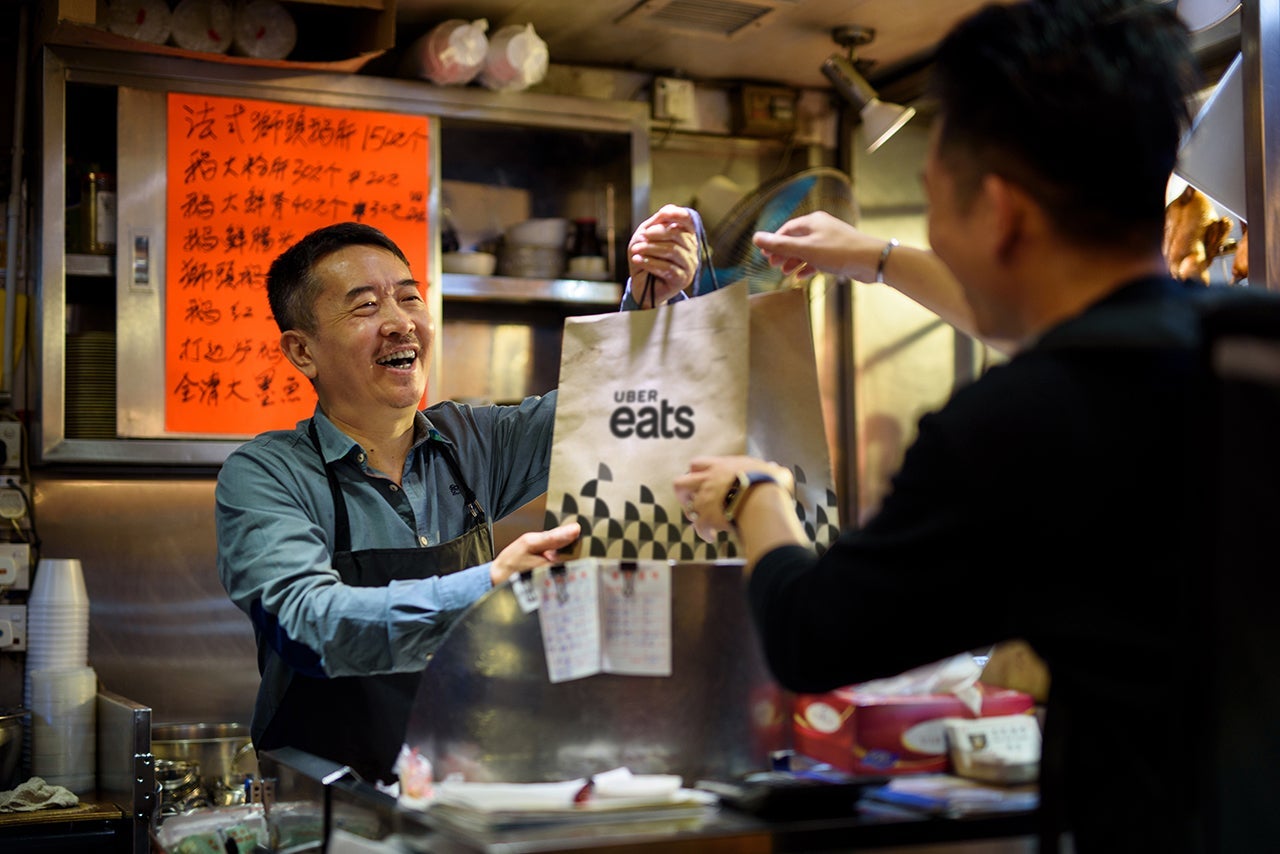
Pros of the Amex Gold card: Besides its impressive earnings on dining and U.S. supermarket purchases, this card comes with over $420 in annual statement credits. You'll get up to $10 in monthly dining credits when you use your Amex Gold to pay for eligible dining purchases, as well as up to $10 monthly Uber Cash credit when you use your card to pay for Uber Eats orders or Uber rides in the U.S. (up to $120 per calendar year for the dining credit, up to $120 per calendar year for the Uber credit).
Your Amex Gold card must be added to your Uber account and an Amex Card must be selected as the payment method for your Uber or Uber Eats transaction to redeem the Amex Uber Cash benefit. The dining credit may be used for purchases with Buffalo Wild Wings, Wonder, Five Guys, Goldbelly (ends June 30, 2026), Grubhub, The Cheesecake Factory and Wine.com (ends June 30, 2026).
Cardmembers can also receive up to $50 biannually (up to $100 in statement credits each calendar year) for purchases made at U.S. Resy-affiliated restaurants. Finally, cardmembers can get up to $84 per calendar year in statement credits for U.S. Dunkin' Donuts purchases (up to $7 per month).
If you're able to maximize these credits, you'll get more in value than what you'll pay in the annual fee from these benefits alone. Enrollment is required for select benefits.
UBER
Cons of the Amex Gold card: The perfect in-between card for some is still too much or not enough for others. If you want to keep your annual fee costs low and won't maximize the credits on this card, you may be better off with a mid-tier card with a lower annual fee.
At the same time, those who travel frequently and look for perks like elite status and airport lounge access in a card will be disappointed with the Amex Gold.
Verdict: The Amex Gold is a great fit for anyone who wants more benefits and earnings than most mid-tier cards but doesn't want to keep track of all the extras that come with a premium card. Foodies and frequent flyers alike will be pleased with the earnings structure and monthly credits this card offers, but of course, no card is perfect for everyone.
For instance, I order delivery more often than I eat out, and I live in a state with no Dunkin' Donuts locations. I'll only be able to use the Dunkin' Donuts credit when I travel, and I envision having some difficulty maximizing the Resy credit. Prospective cardmembers in a situation like mine may be better off opening a different card.
If you want better benefits and earnings than most mid-tier cards offer but are fine with skipping elite status and high annual fees, the Amex Gold is the perfect "in-between" card. Valuable credits, an impressive return on dining, supermarket and flight purchases and an annual fee that won't break the bank make this a card even Goldilocks would be happy with.