The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Advertiser disclosure
The Points Guy believes that credit cards can transform lives, helping you leverage everyday spending for cash back or travel experiences that might otherwise be out of reach. That's why we publish a variety of editorial content and card comparisons: to help you find a great card to turn your goals into reality.
Our site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened with our partners, and this may impact how or where these products appear. While we don't cover all available credit cards, our editorial team creates and maintains all of the analysis of these cards, and our content is not influenced nor subject to review by any credit card company, bank or partner prior to (or after) publication. Please view our advertising policy and product review methodology for more information.
Katie Genter is a digital nomad who has traveled full time since June 2017. She writes and edits stories about points and miles, and loyalty programs, often letting her personal experiences color these stories.
February 15, 2025 • 13 min read
The cards we feature here are from partners who compensate us when you are approved through our site, and this may impact how or where these products appear. We don't cover all available credit cards, but our analysis, reviews, and opinions are entirely from our editorial team. Terms apply to the offers listed on this page. Please view our advertising policy and product review methodology for more information.
Editorial note: This is a recurring post, regularly updated with new information and offers.
Editorial disclaimer: Opinions expressed here are the author's alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.
Related stories
Quick summary
The article reviews top cash-back cards that do not charge annual fees, highlighting their suitability for different spending habits and travel needs.
Some cards offer elevated cash back in specific categories, while others provide a flat rate on all purchases.
Foreign transaction fees are a key consideration, as some cards are better suited for international use than others.
Pairing multiple cards can help maximize cash-back earnings by covering various bonus categories.
What to consider
Certain cards impose foreign transaction fees, making them less ideal for international purchases.
Bonus cash-back rates often apply only to specific categories or up to a quarterly spending cap.
Some cards offer additional protections like extended warranty or travel insurance, but terms and exclusions vary.
What you'll miss from the article
A detailed comparison of which no-annual-fee cash-back cards best match different spending patterns and travel preferences.
Generated by AI with support from our editorial team.
Points and miles enthusiasts love to maximize their travel redemptions and relish in their cardholder benefits that help offset high annual fees. Others prefer a simpler approach, utilizing one card that gives them cash back on their purchases without annual fees.
If you’re one for the solo-card approach, one of your main considerations should be whether you’re going to use the card at home, abroad or a mix of both. Chances are, if you don’t like annual fees, you’re not going to like incurring foreign transaction fees either.
Discover it® Cash Back: Best for elevated cash back on rotating categories, both in your first year and with no foreign transaction fees
The information for the Citi Custom Cash card has been collected independently by The Points Guy. The card details on this page have not been reviewed or provided by the card issuer.
Bank of America Customized Cash Rewards credit card
Welcome bonus: $200 cash rewards bonus after making at least $1,000 in purchases in the first 90 days of your account opening.
THE POINTS GUY
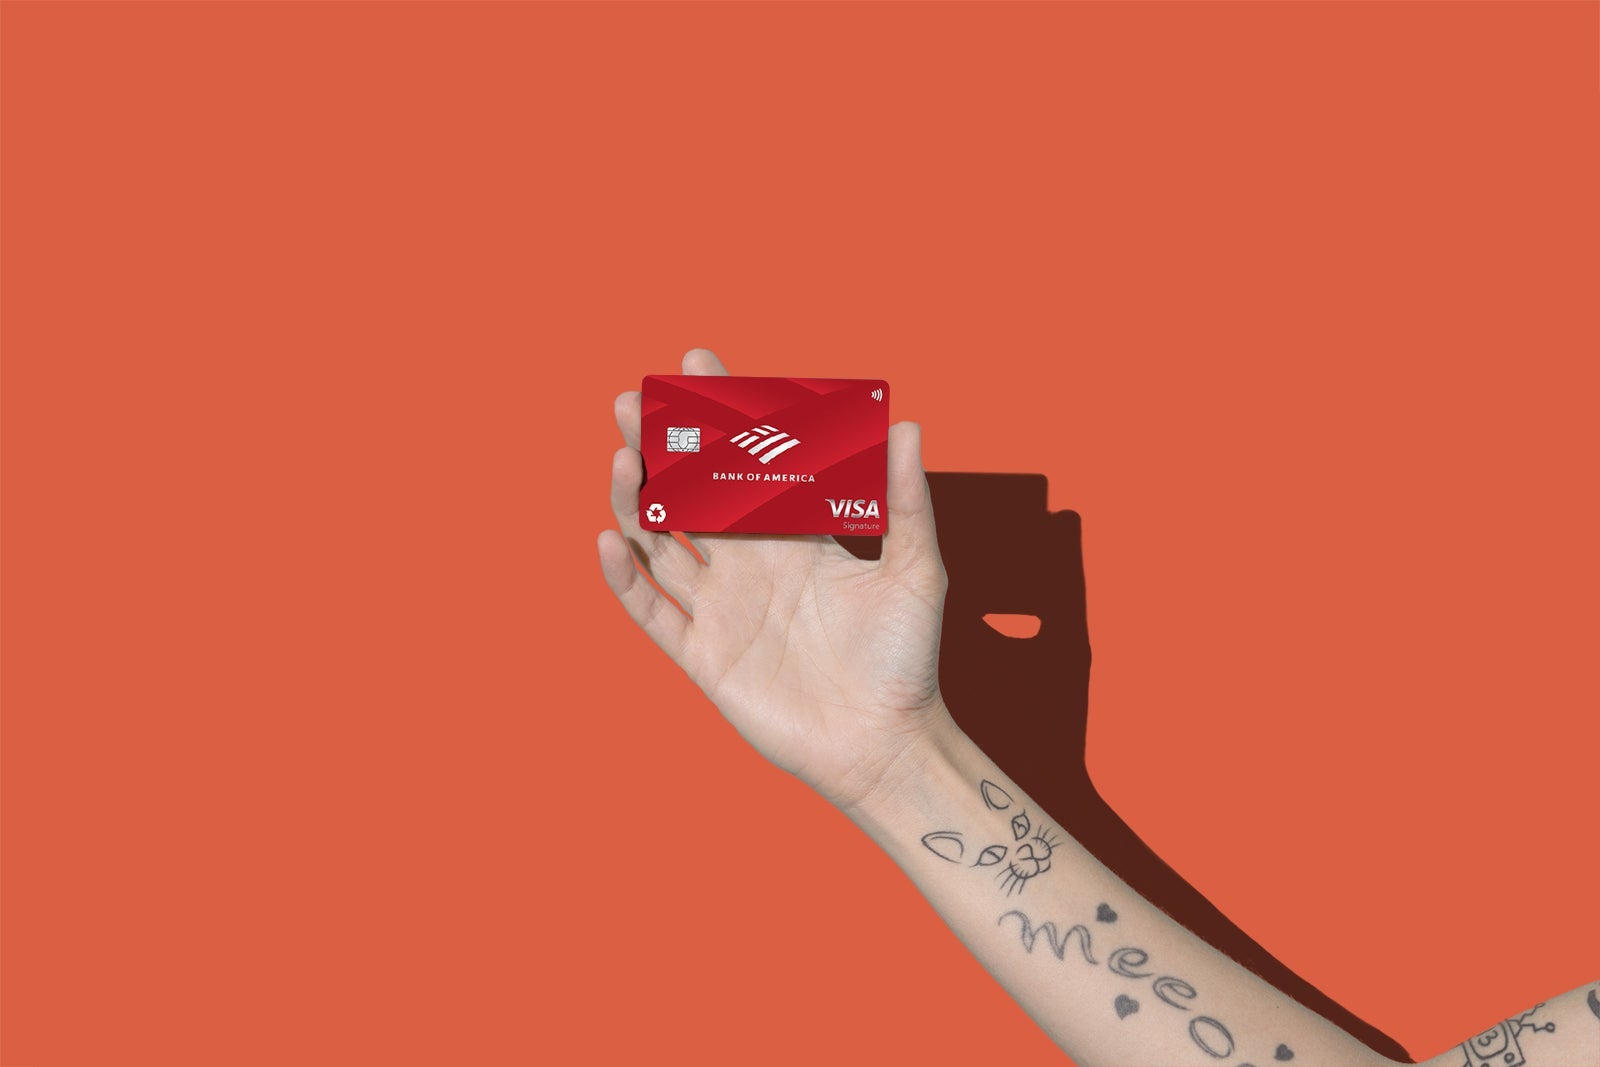
With the Bank of America Customized Cash Rewards credit card, you can earn 6% cash back (in the first year, then 3%) in one category of your choice: gas and EV charging stations, online shopping/cable/internet/phone plans/streaming, dining, travel, drugstores/pharmacies or home improvement/furnishings. You can also earn 2% cash back at grocery stores and wholesale clubs — but your elevated earnings are only on the first $2,500 of spending in these categories each quarter. These categories can be changed once a month. All other purchases earn 1% cash rewards.
BofA Rewards™ members can earn between 10% and 75% more cash rewards, though the BofA Rewards bonus is not applied to the 3% first-year bonus.
This card also offers extended warranty protection when you pay expenses with it. The downside is that it charges a 3% foreign transaction fee.
Welcome bonus: Earn a $200 cash bonus once you spend $500 on purchases in the first three months from account opening.
THE POINTS GUY
The Capital One Quicksilver Cash Rewards Credit Card earns unlimited 1.5% cash back on every purchase, with no foreign transaction fees and no annual fee. This makes it a good card for general spending while abroad. Plus, when you pay with this card, it provides extended warranty protection and travel accident insurance.
Welcome bonus: Earn a $200 cash bonus once you spend $500 on purchases in the first three months from account opening.
THE POINTS GUY
The Capital One Savor Cash Rewards Credit Card offers 3% cash back on dining and entertainment, popular streaming services, at grocery stores (excluding superstores like Walmart® and Target®) and 1% on all other purchases. There are no foreign transaction fees and the card offers extended warranty protection as well as travel accident insurance and an auto rental collision damage waiver. So, this card is a good choice if you tend to spend a lot on dining and entertainment, both at home and abroad.
Welcome bonus: Earn a $200 bonus after spending $500 on purchases within the first three months from account opening.
THE POINTS GUY
The Chase Freedom Unlimited earns 5% back on travel booked through Chase Travel℠, 3% back on dining (including takeout and eligible delivery services), 3% back at drugstores, 2% cash back on Lyft rides through Sept. 30, 2027 and 1.5% back on everything else.
Welcome bonus: Earn a $250 bonus after you spend $500 on purchases in your first three months from account opening.
THE POINTS GUY
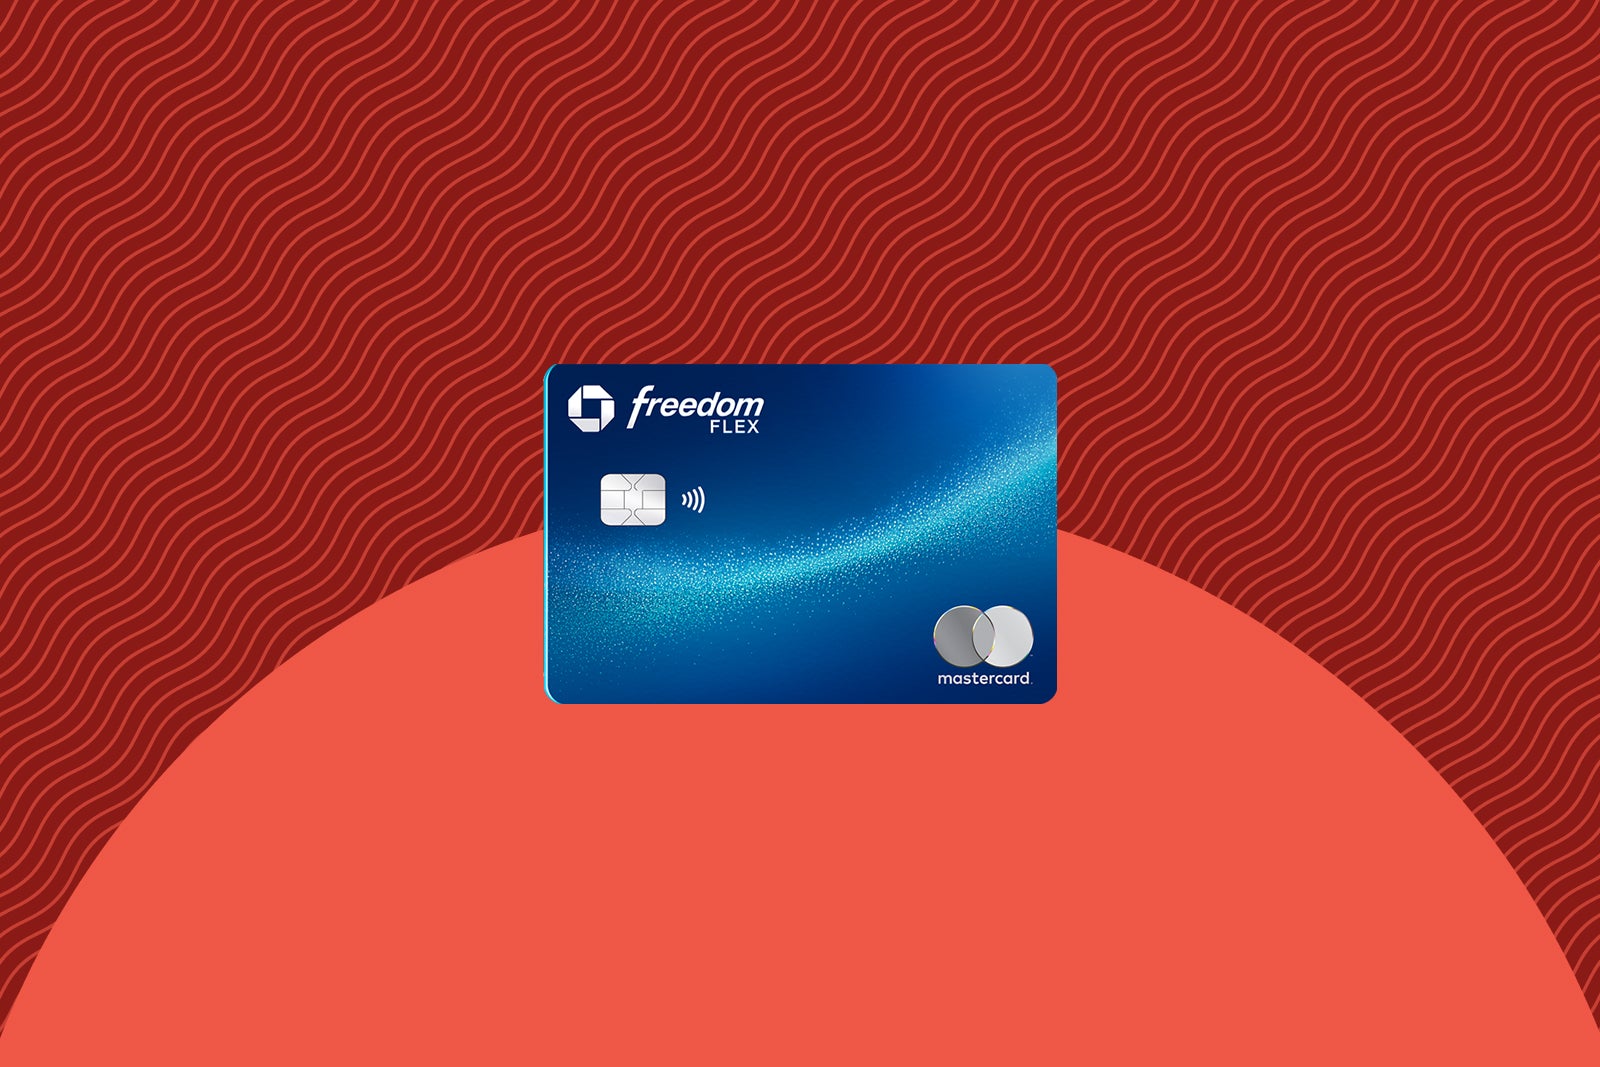
The Chase Freedom Flex earns 5% on up to $1,500 in combined purchases in bonus categories each quarter you activate, 3% cash back on dining and drugstore purchases, 2% cash back on Lyft rides through Sept. 30, 2027 and 1% cash back on everything else.
Welcome bonus: Earn $200 cash back after spending $1,500 on purchases in the first six months of account opening.
THE POINTS GUY
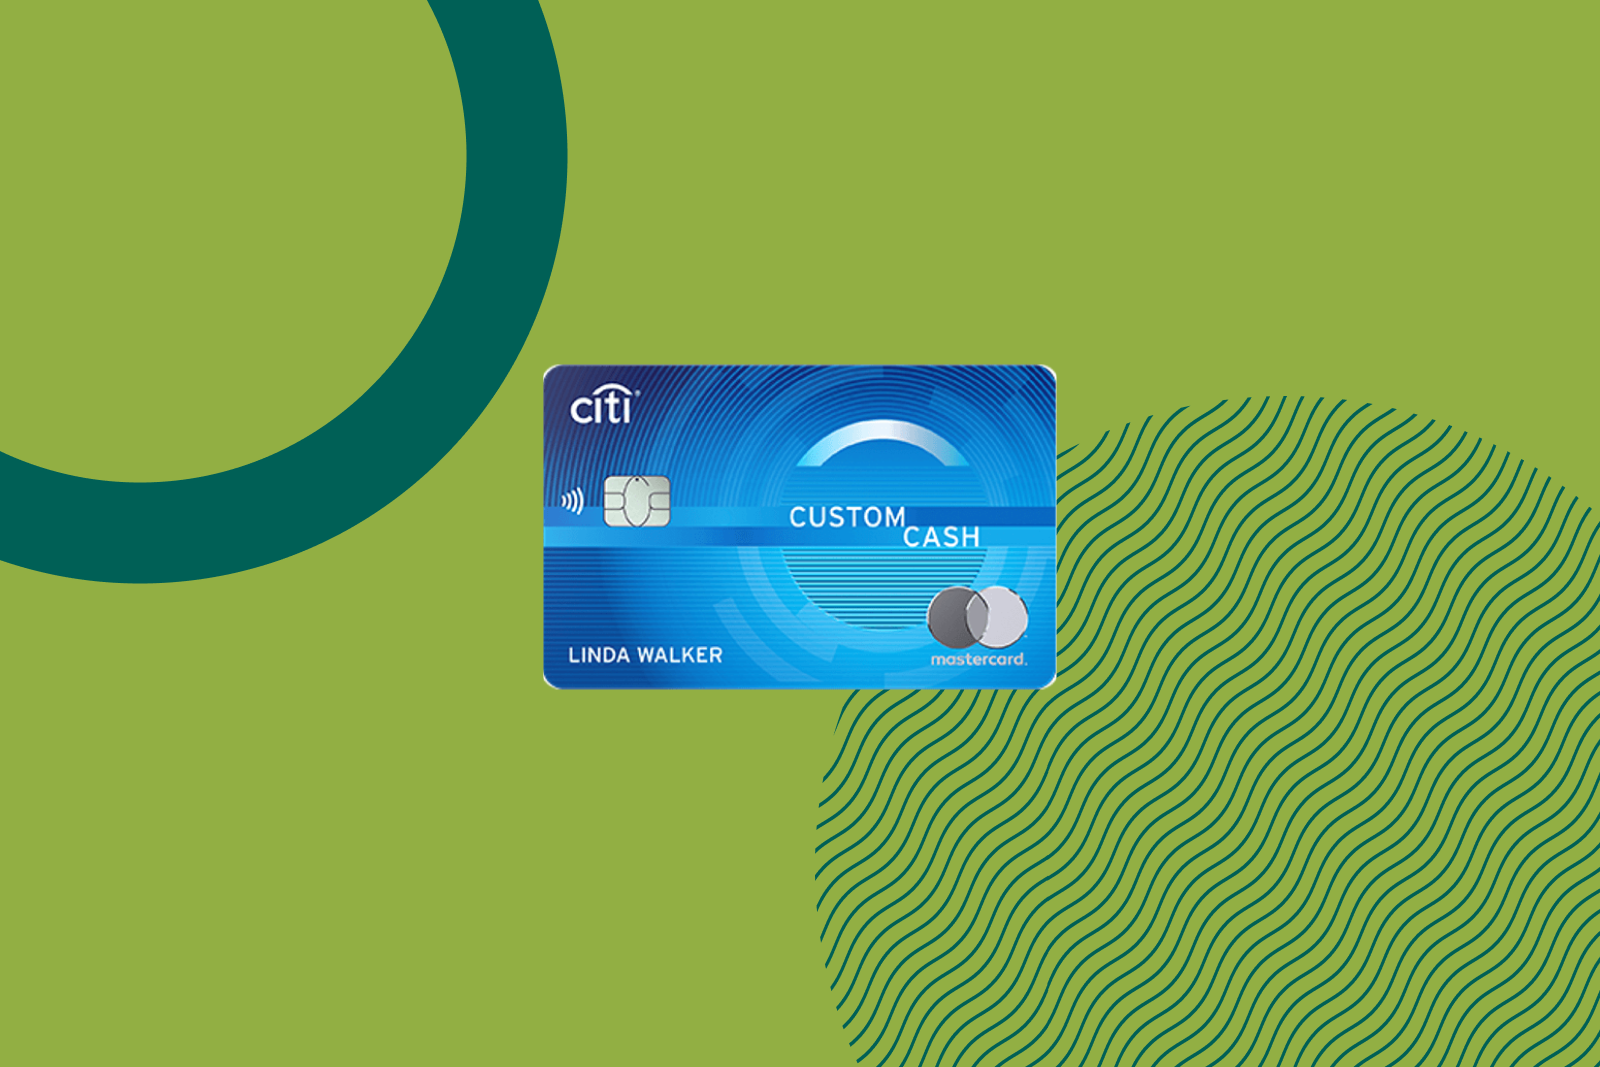
The Citi Custom Cash earns 5% cash back in your top eligible spending category each billing cycle, up to the first $500, 1% cash back thereafter and 1% cash back on all other purchases.
The categories include drugstores, fitness clubs, gas stations, grocery stores, home improvement stores, live entertainment, restaurants, select travel, select transit and select streaming services. Additionally, through June 30, 2026, you'll earn an additional 4% cash back on hotels, car rentals, and attractions booked through the Citi Travel portal.
You will not want to use this card internationally because it imposes a 3% foreign transaction fee. This card also includes access to Citi Entertainment, which can help you score tickets to some of the hottest events in town.
Welcome bonus: Earn $200 cash back after spending $1,500 on purchases in the first 6 months of account opening.
THE POINTS GUY
The Citi Double Cash card earns 2% cash back on everything (1% when you buy and 1% as you pay).
The Citi Double Cash Card earns up to 2% cash back on all purchases — 1% when you make a purchase and another 1% when you pay your statement — all with no annual fee and no limit on the cash back you can earn. This makes it a good choice for general spending while you’re in the U.S. But you’ll want to store it deep in your luggage when you travel internationally because it charges a 3% foreign transaction fee.
Welcome bonus: Earn a $200 statement credit after spending $500 on purchases in the first three months from account opening. Plus, Discover will match your first year's cash back.
THE POINTS GUY
With Discover it Cash Back, you can earn 5% cash back on up to $1,500 in purchases (per Discover’s Cashback Calendar after enrollment and activation) and 1% cash back on all other purchases.
The card has no annual fee and no foreign transaction fees, so it’s a good choice for spending in the quarterly bonus categories whether you’re in the U.S. or overseas.
Discover matches your total cash back after the first year of card membership, meaning bonus category purchases will effectively earn 10% cash back in your first year. Unfortunately, the card doesn't offer a welcome bonus.
If you refuse to pay any annual fees, or if you travel internationally and prefer the simplicity of cash-back rewards, you could sign up for the Capital One Quicksilver Cash Rewards card, which provides 1.5% back on everything.
If most of your credit card spending is on dining, entertainment and groceries, you may be better off with the Capital One Savor Cash Rewards card. Neither of these cards charges an annual fee nor any foreign transaction fees, which makes either card a good choice if you’re looking for one card for all your expenses at home and abroad.
If you don’t travel internationally, you may be better off getting the Citi Double Cash Card if you only want one card. But, depending on what types of expenses you normally put on your credit card, you may be better off getting the Bank of America Customized Cash Rewards card or the Capital One Savor Cash Rewards.
If you really want to maximize your cash back earnings, you can opt for getting multiple cards. I would start with the Citi Double Cash as a great card to start with, as it earns 2% cash back on all purchases (1% when you buy, 1% when you pay).
You can pair that with any of the other cards above to cover other bonus categories to maximize your spending.
There's no shortage of good cash back and travel rewards credit cards on the market. While travel rewards can offer outsize value, those looking for more flexibility will enjoy earning cash back. Luckily, there are several great options that don't charge annual fees, so you can hold onto these cards year after year without needing to pay to keep them in your wallet.
For Capital One products listed on this page, some of the benefits may be provided by Visa® or Mastercard® and may vary by product. See the respective Guide to Benefits for details, as terms and exclusions apply.
Updated 7/31/26
Comments
By commenting, you agree to our Community Guidelines to help create a positive space for conversation. The responses below are not provided or commissioned by the bank advertiser, our partners, or The Points Guy (“TPG”). They have not been reviewed, approved, or otherwise endorsed by any of these parties. All responses are submitted by individual contributors, and neither the bank advertiser, our partners, nor TPG are responsible for ensuring that all posts and/or questions are answered.